Debt Snowball Tool · Case studies

Debt Payoff Case Studies

Each study below takes a real-life total — $5,000 through $100,000 — picks a typical credit-card shape for it, and runs both the snowball and the avalanche method on the same engine. The headline number is the monthly payment that hits that study's target, and the target is not always twelve months: the $50,000 case is built around a two-year plan, and the $100,000 case is measured at three payment levels. The number most people miss is what happens if you do the minimum.

$5,000
$515/mo
12 months · 3 cards
$5,000
$934/mo
6 months · 3 cards
$10,000
$1,050/mo
12 months · 3 cards
$20,000
$2,100/mo
12 months · 4 cards
$25,000
$2,700/mo
11–12 months · 4 cards
$30,000
$3,150/mo
12 months · 5 cards
$40,000
$4,100/mo
12 months · 5 cards
$50,000
$3,013/mo
24 months · 5 cards
$100,000
$10,297/mo
12 months · 5 cards
$10,000
$1,868/mo
6 months · 3 cards
$15,000
$2,795/mo
6 months · 4 cards
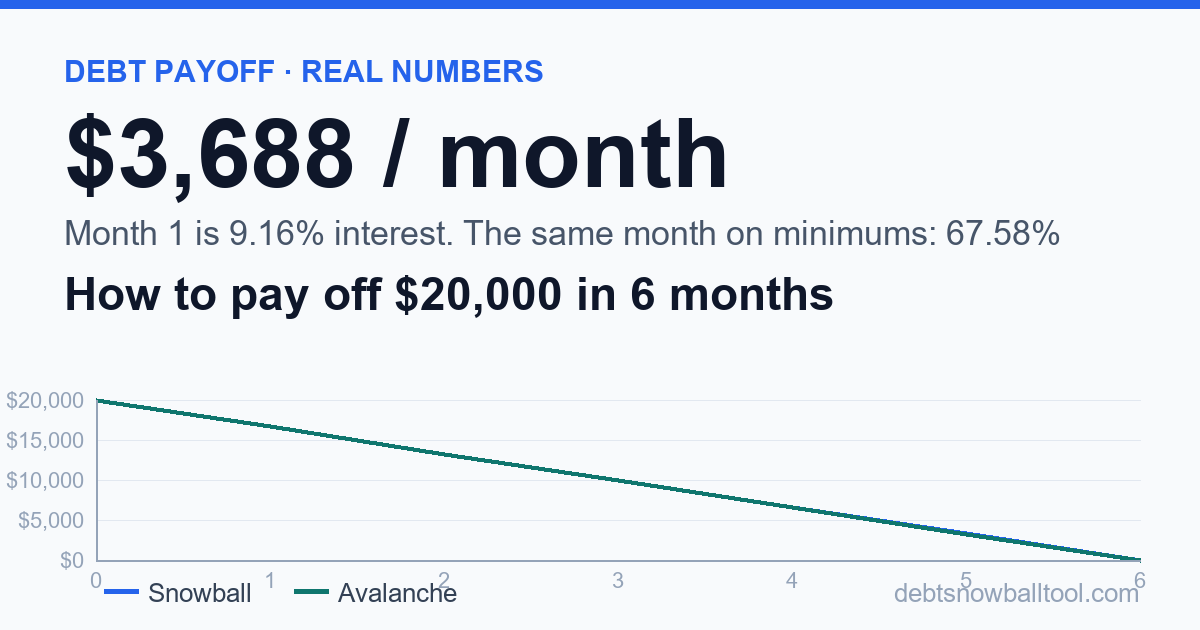
$20,000
$3,688/mo
6 months · 4 cards
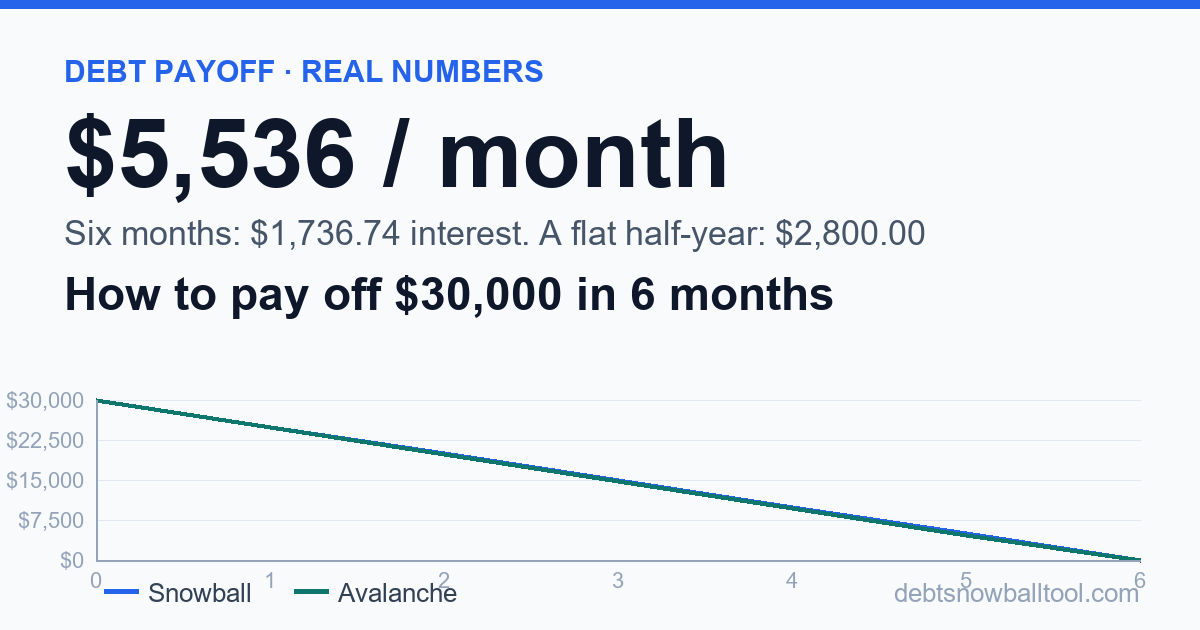
$30,000
$5,536/mo
6 months · 5 cards
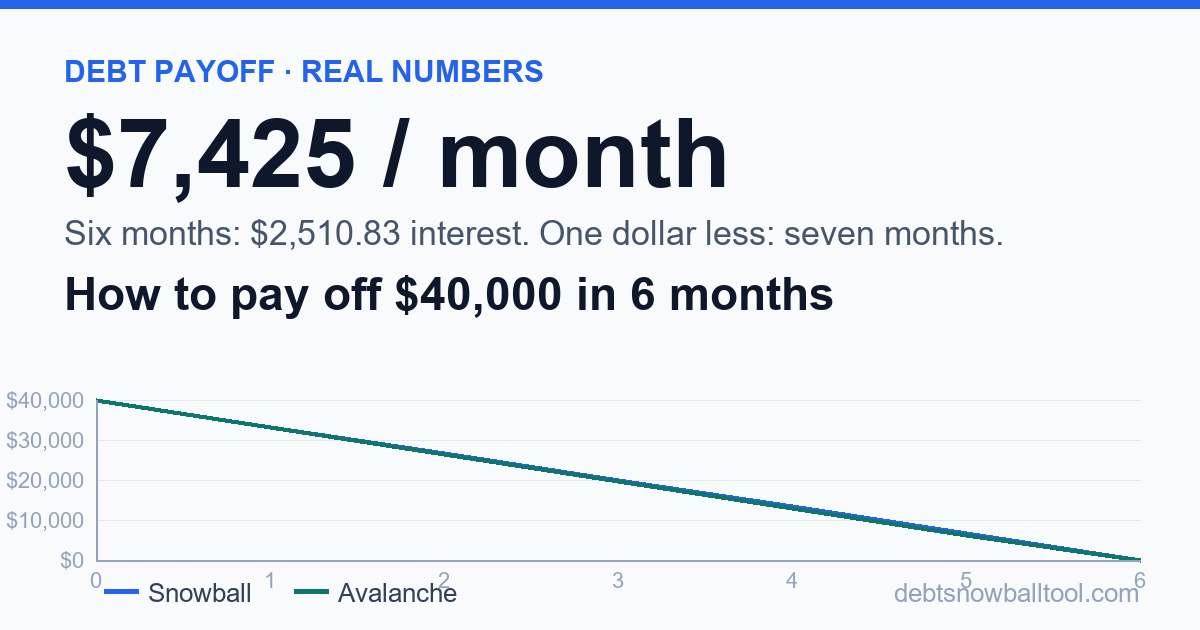
$40,000
$7,425/mo
6 months · 5 cards
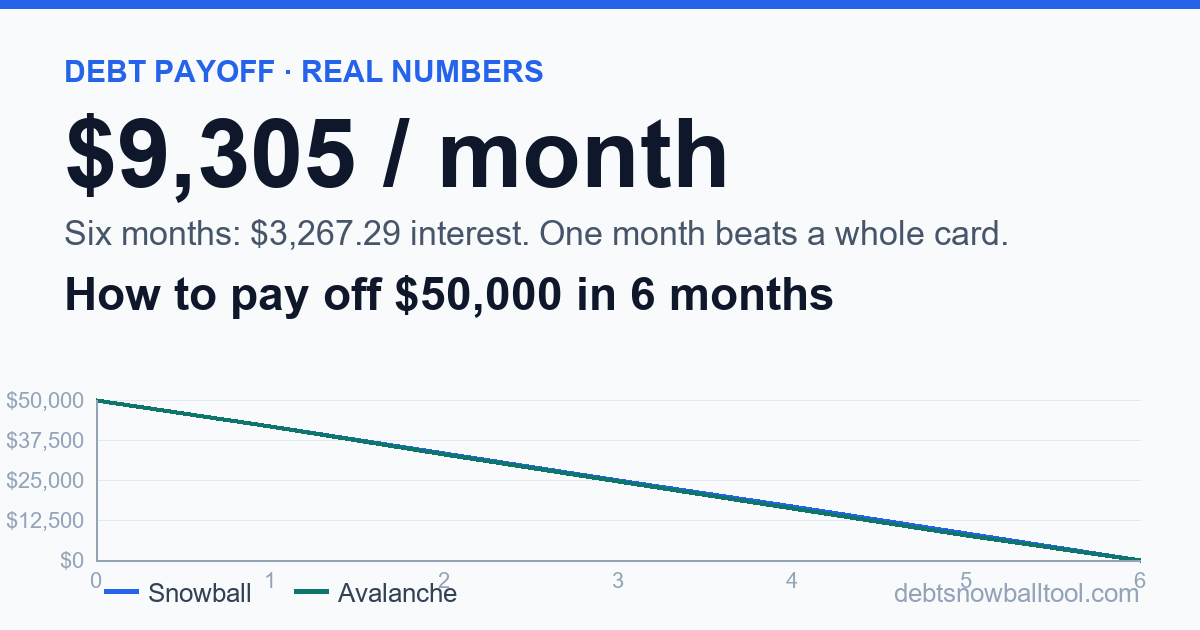
$50,000
$9,305/mo
6 months · 5 cards
$50,000
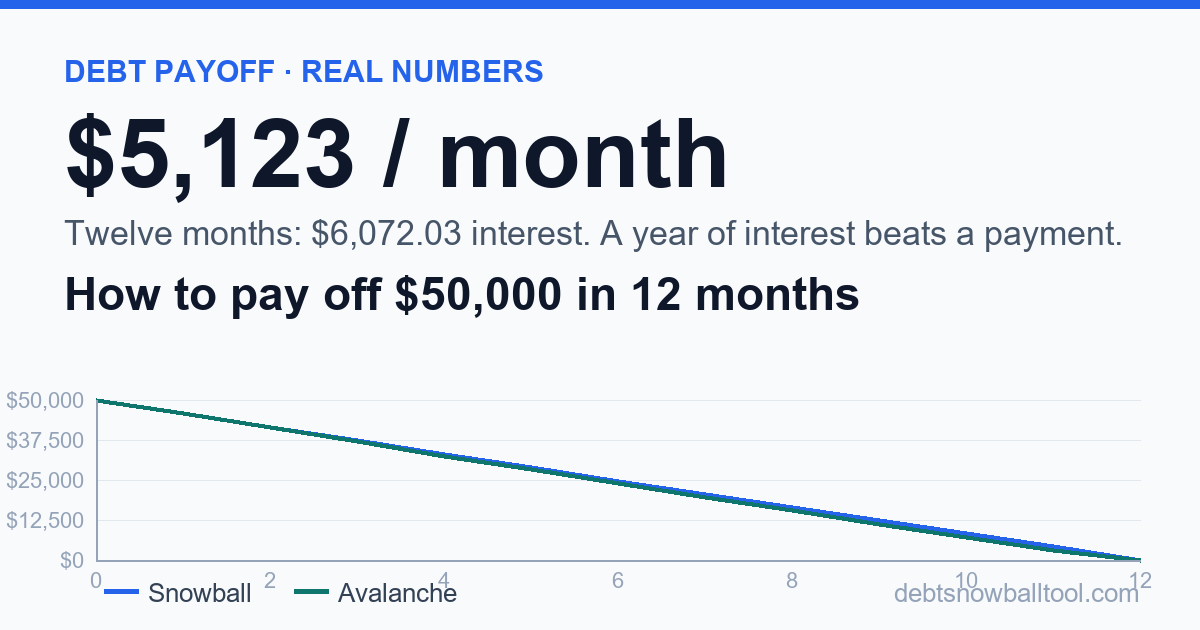
$5,123/mo
12 months · 5 cards
$60,000
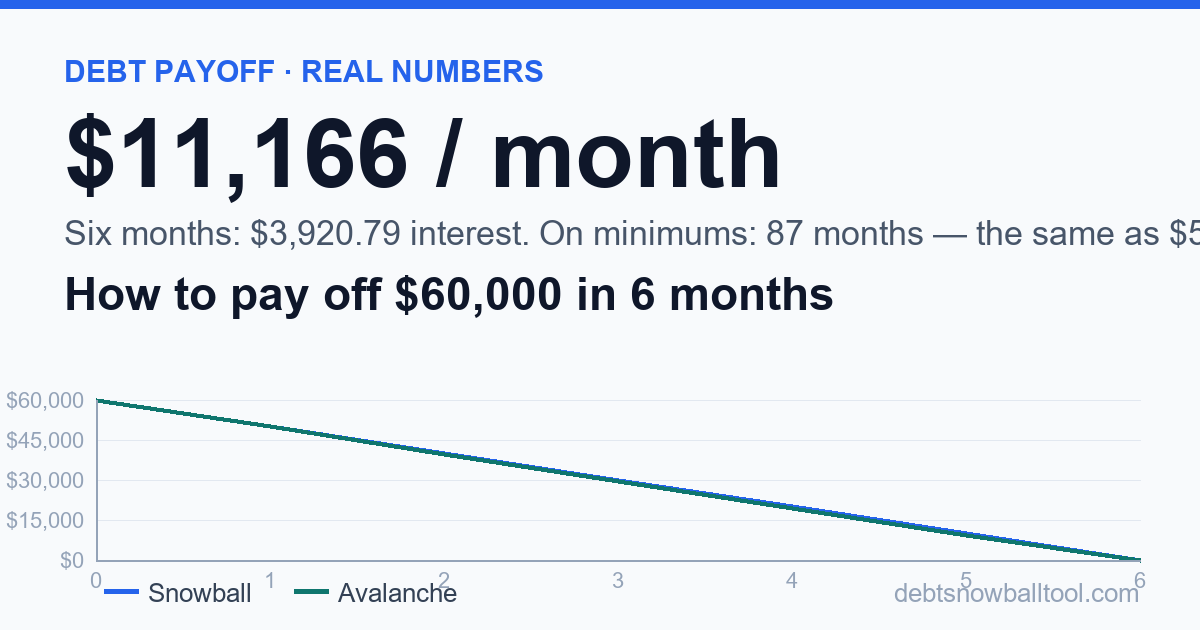
$11,166/mo
6 months · 5 cards
$60,000
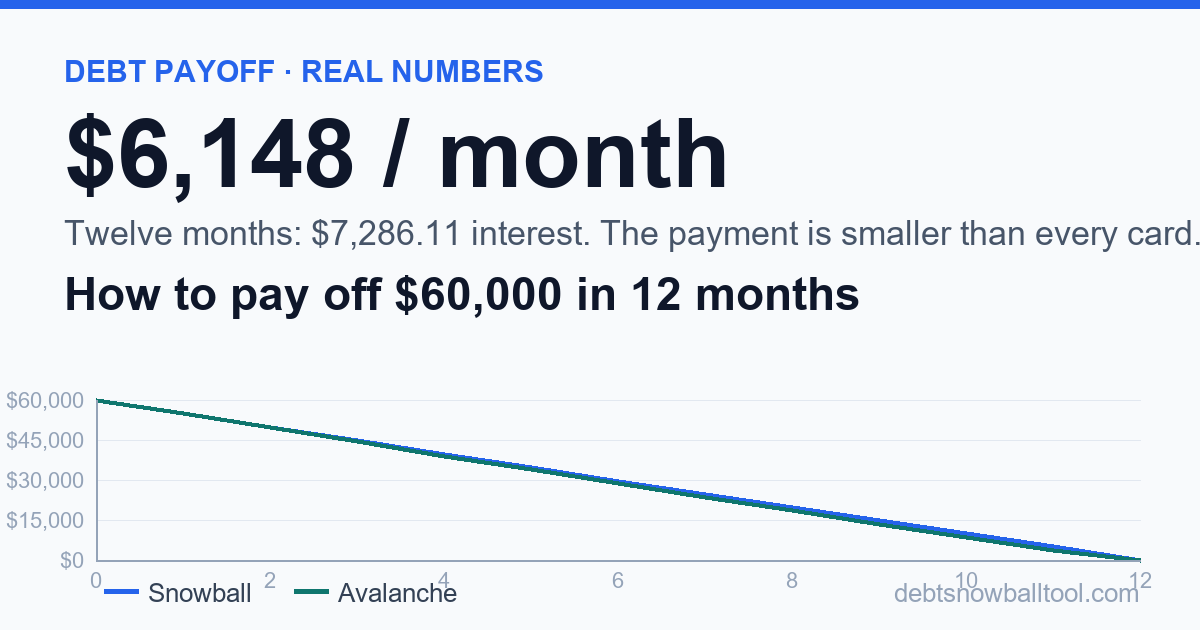
$6,148/mo
12 months · 5 cards
$60,000
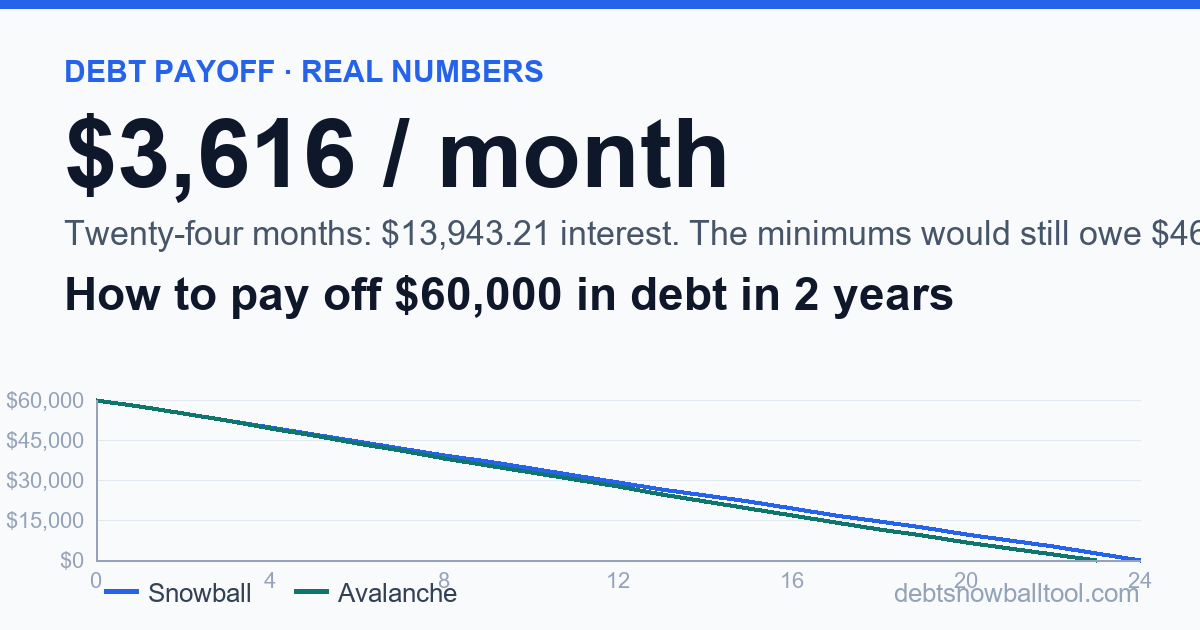
$3,616/mo
24 months · 5 cards
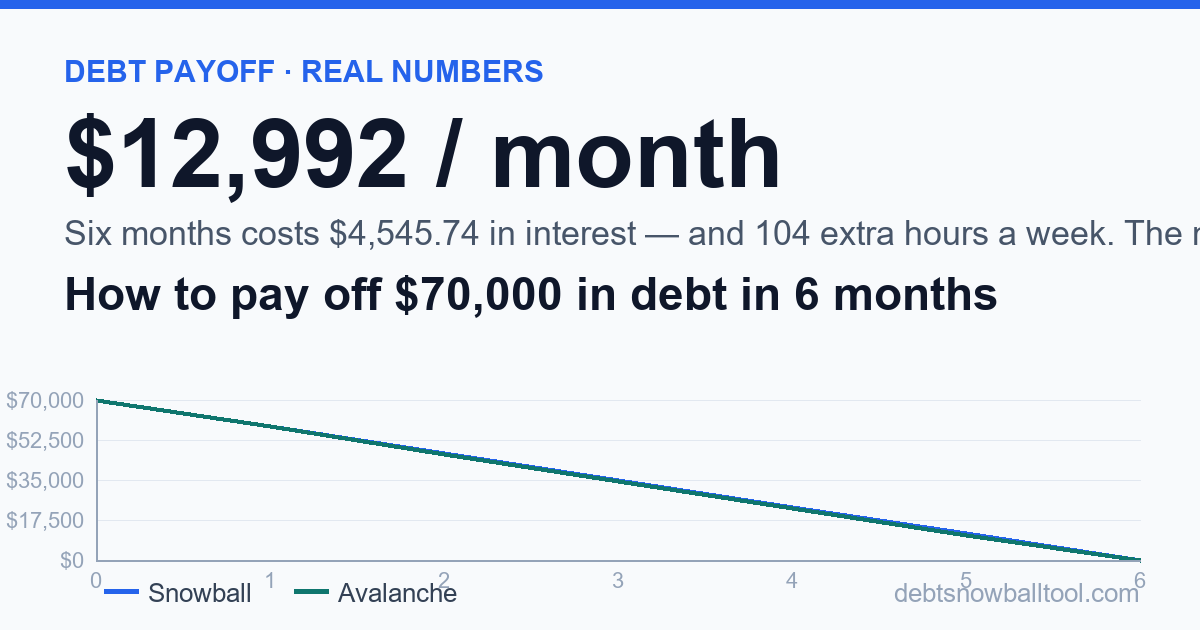
$70,000
$12,992/mo
6 months · 5 cards
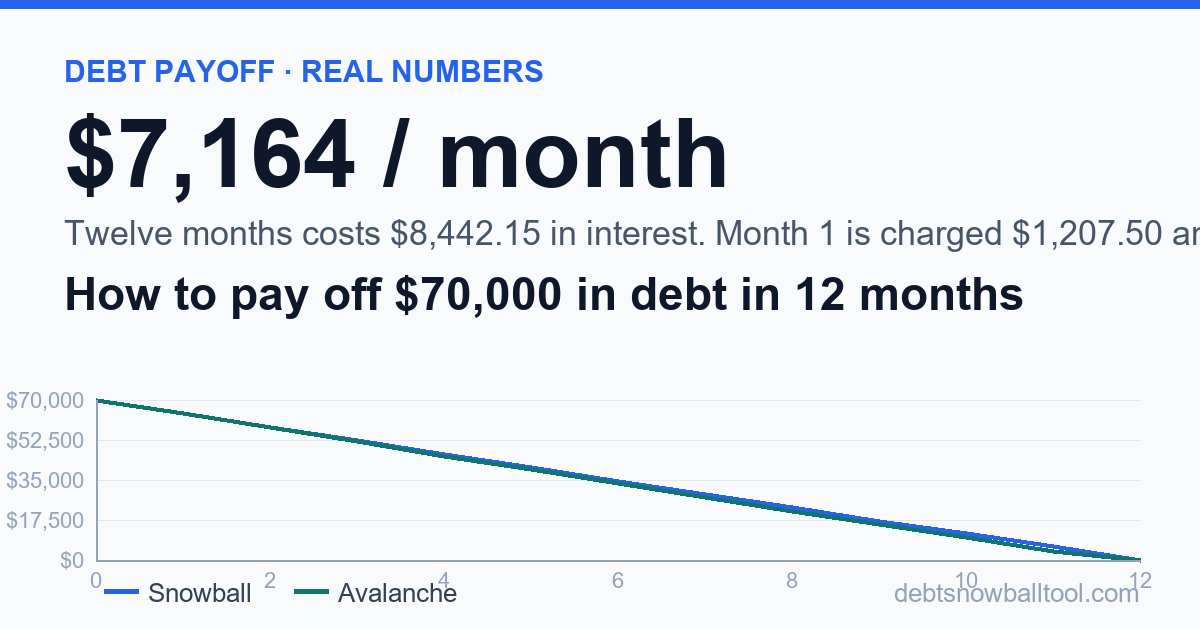
$70,000
$7,164/mo
12 months · 5 cards
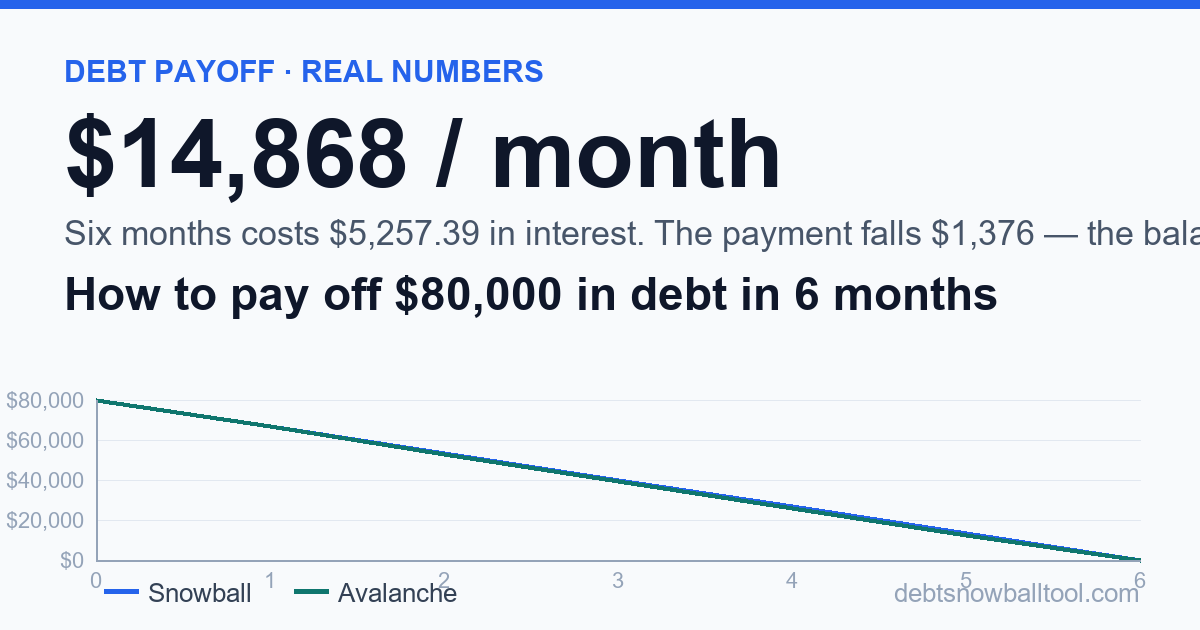
$80,000
$14,868/mo
6 months · 5 cards
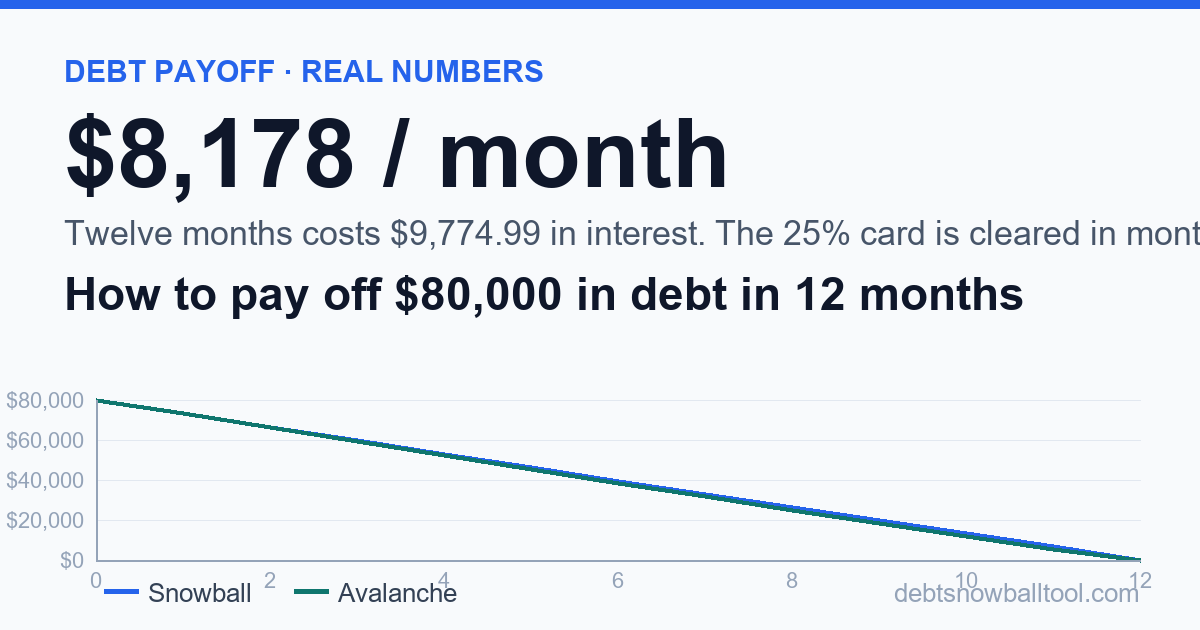
$80,000
$8,178/mo
12 months · 5 cards
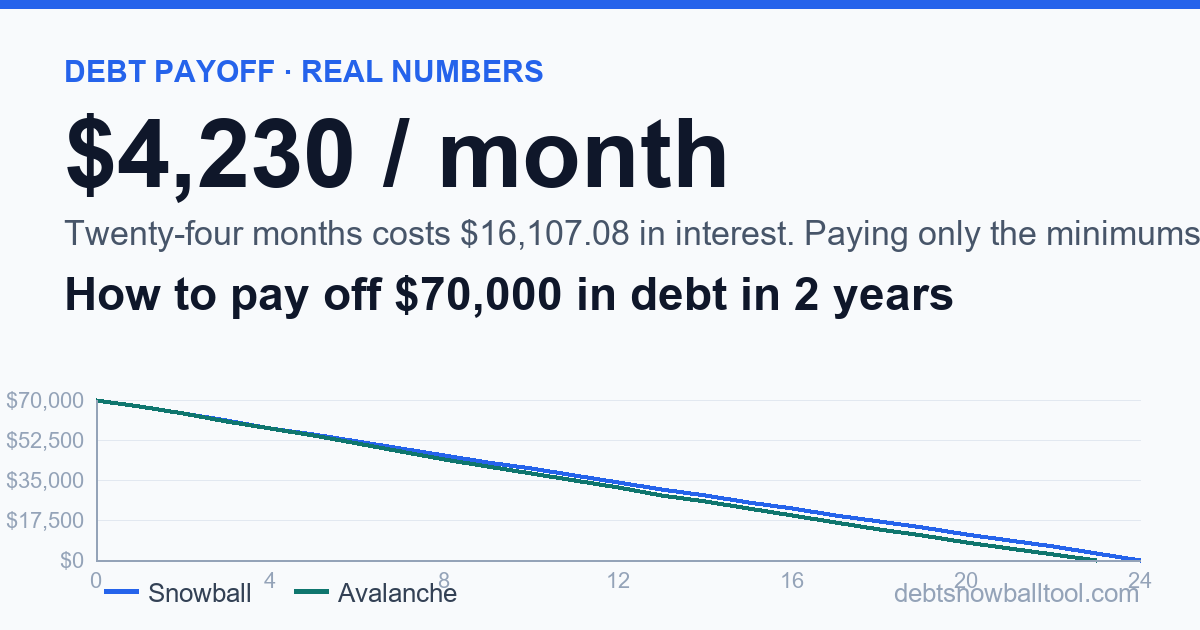
$70,000
$4,230/mo
24 months · 5 cards
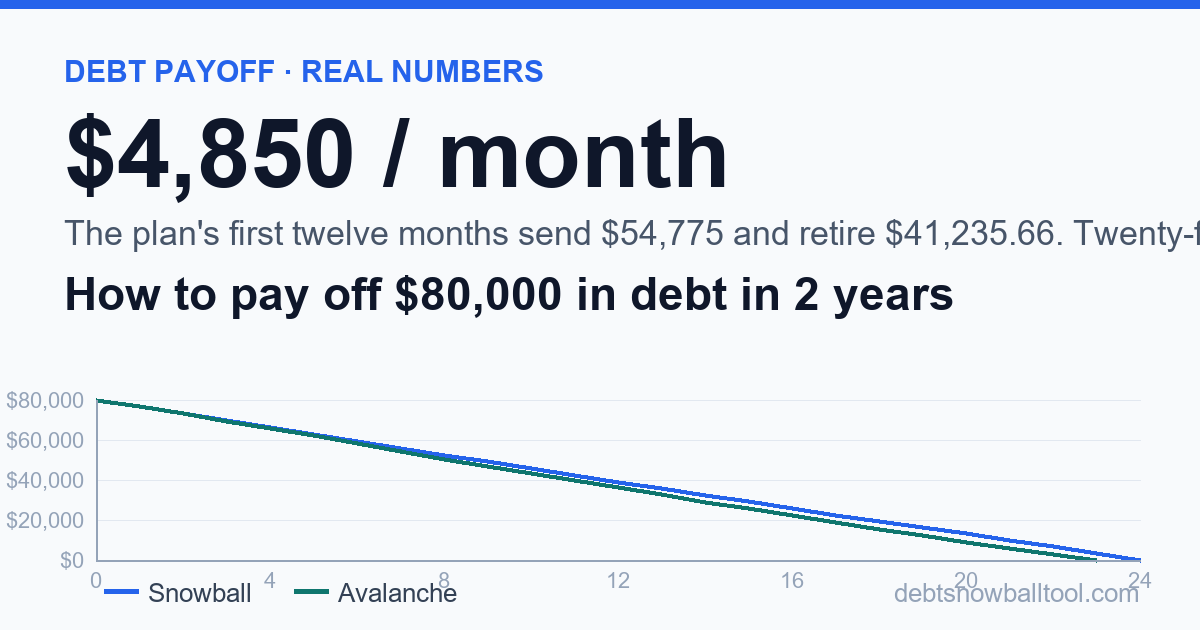
$80,000
$4,850/mo
24 months · 5 cards
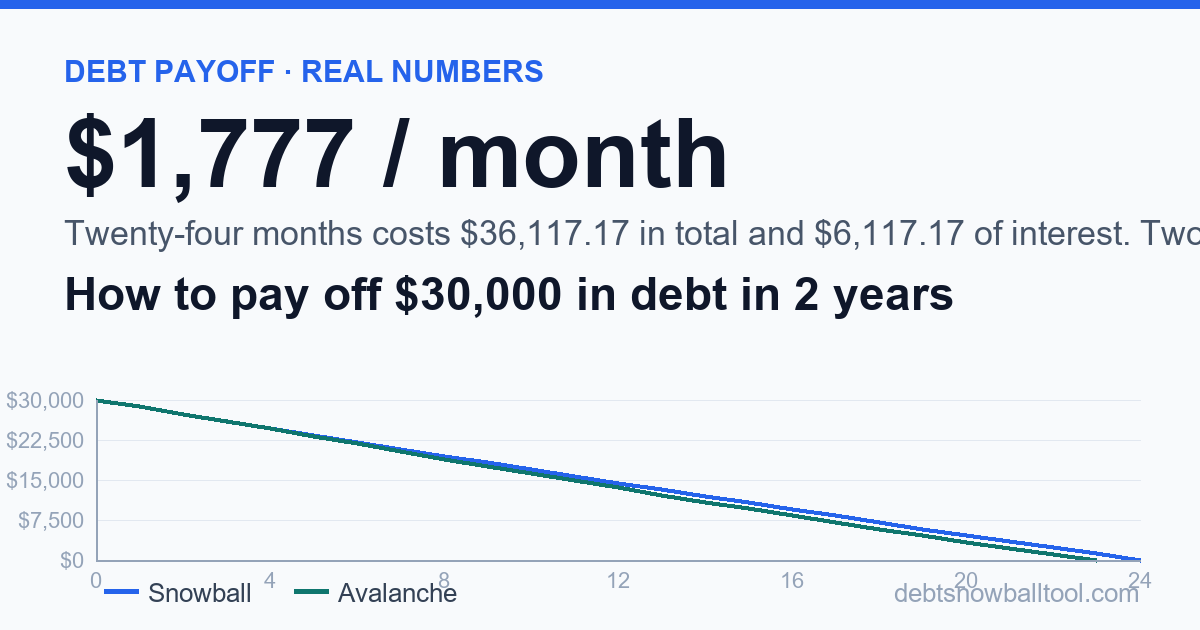
$30,000
$1,777/mo
24 months · 5 cards
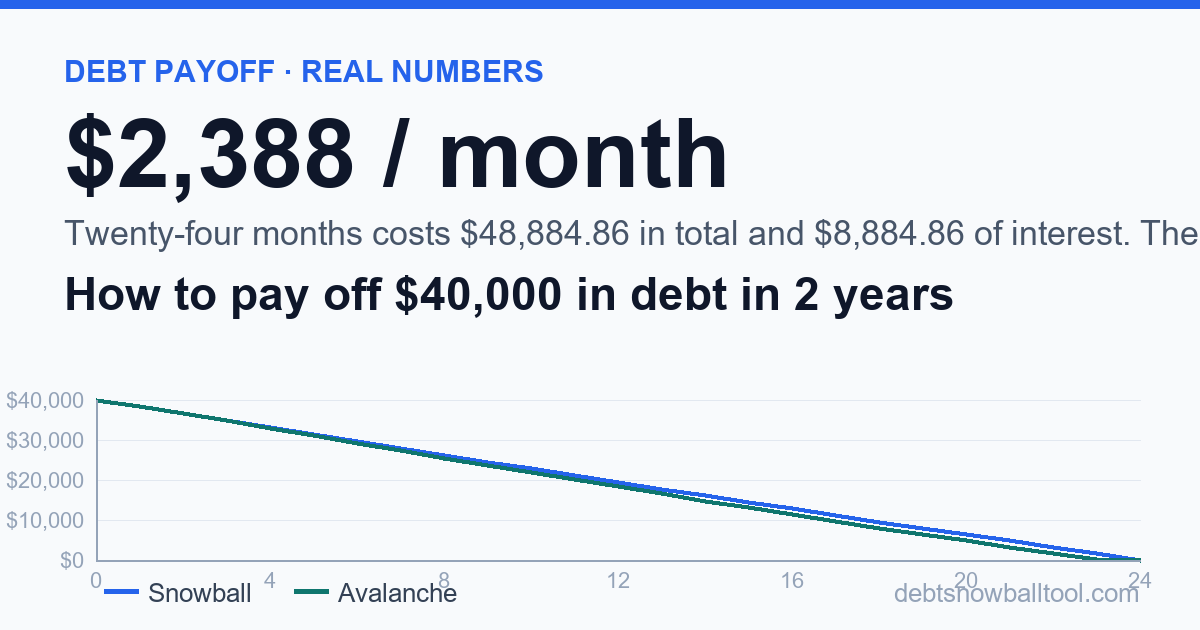
$40,000
$2,388/mo
24 months · 5 cards
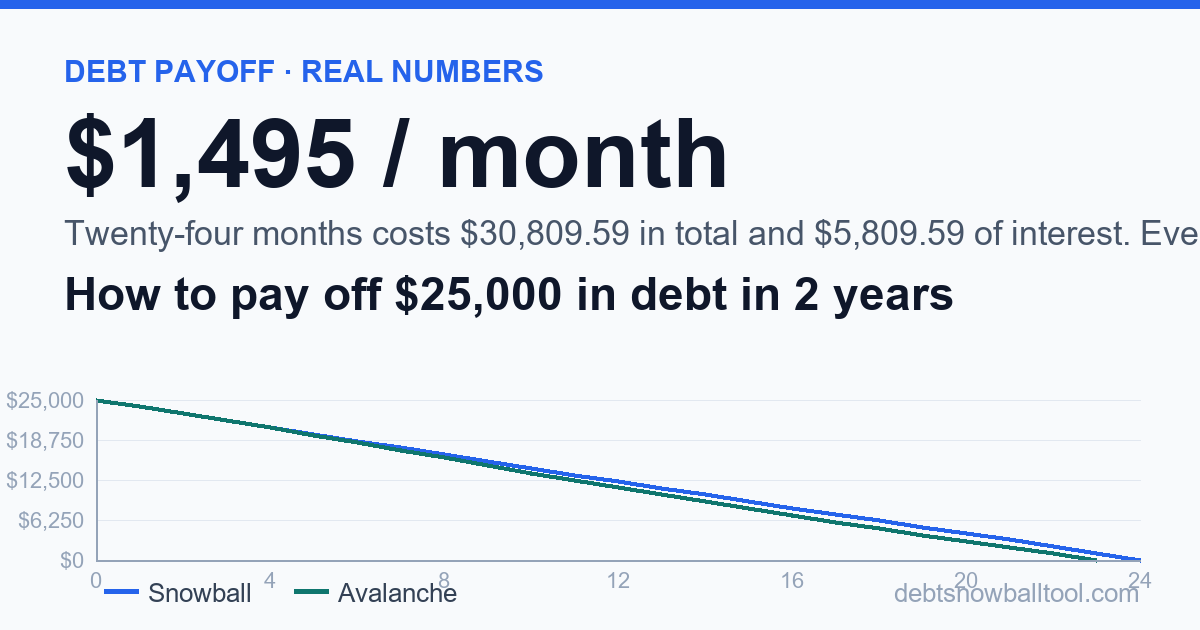
$25,000
$1,495/mo
24 months · 4 cards
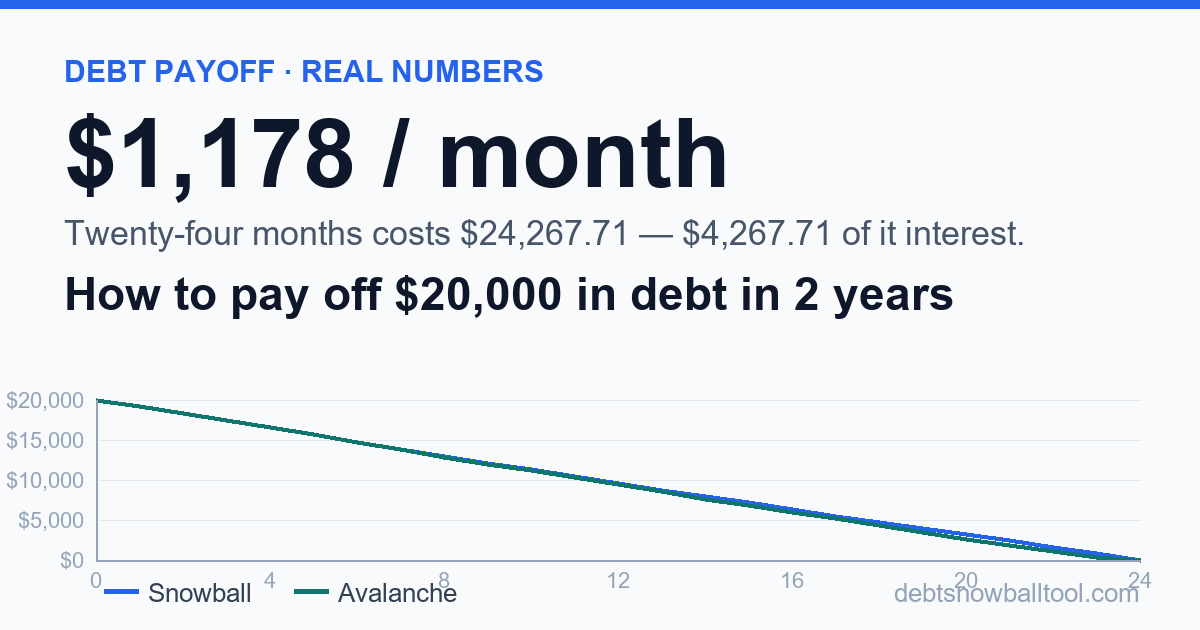
$20,000
$1,178/mo
24 months · 4 cards
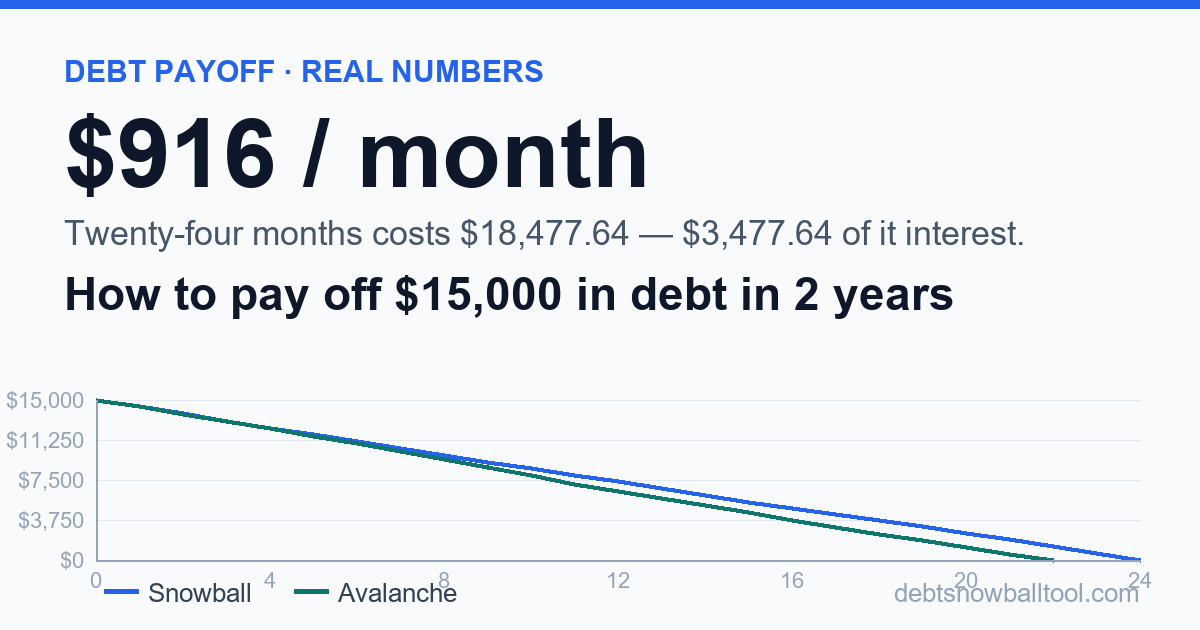
$15,000
$916/mo
24 months · 4 cards
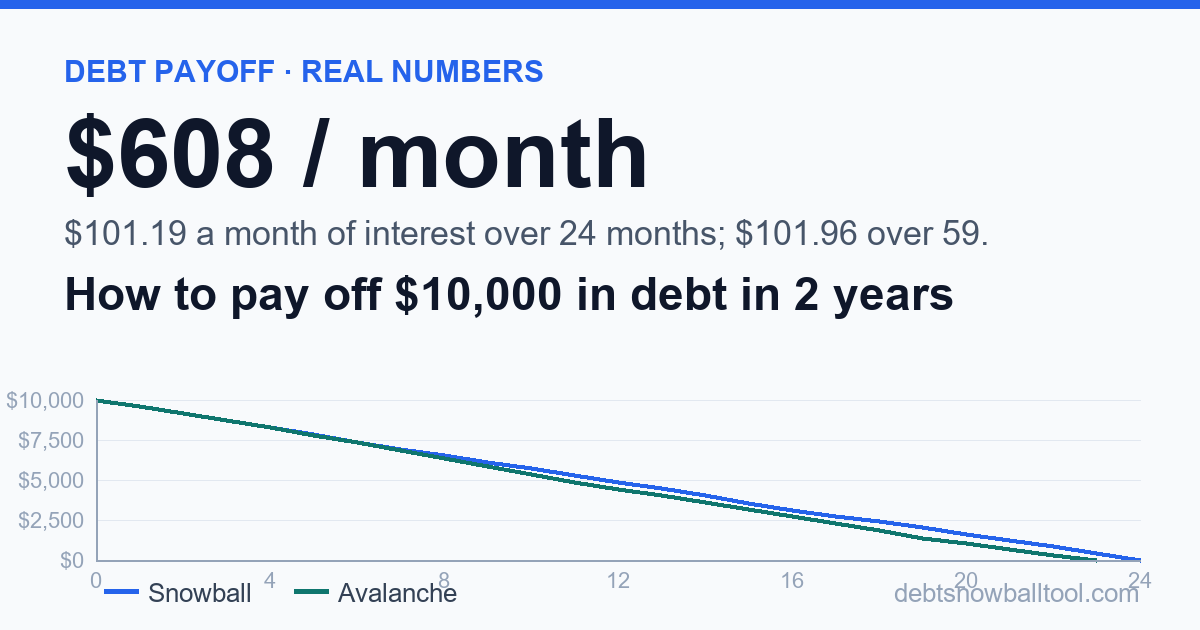
$10,000
$608/mo
24 months · 3 cards
$5,000
$304/mo
24 months · 3 cards
$25,000
$4,625/mo
6 months · 4 cards

Avalanche figures on each example portfolio. Open the API and you can run any of them yourself.

Published

How to pay off $25,000 in 6 months

Four cards totalling $25,000 at 16-24% APR, with $625 in minimums. At $4,625 a month the snowball plan clears it in six months for $1,561.95 in interest — 6.25% of the balance and 5.88% of everything sent. The layer is the principal share: of the first $4,625, $4,205.00 is principal — 90.92% — because the 20.16% rate only charges $420.00 in month 1, and the share climbs every month to 98.04% by month 6 as the interest falls to $81.12. The payments step down from $4,625 to $4,136.95 while the principal inside them stays in a narrow $4,055-$4,245 band, so what falls away is the interest, not the balance. Avalanche at the same $4,625 pays $1,360.13, a gap of $201.82. Paying the minimums alone takes 81 months and costs $17,844.20.
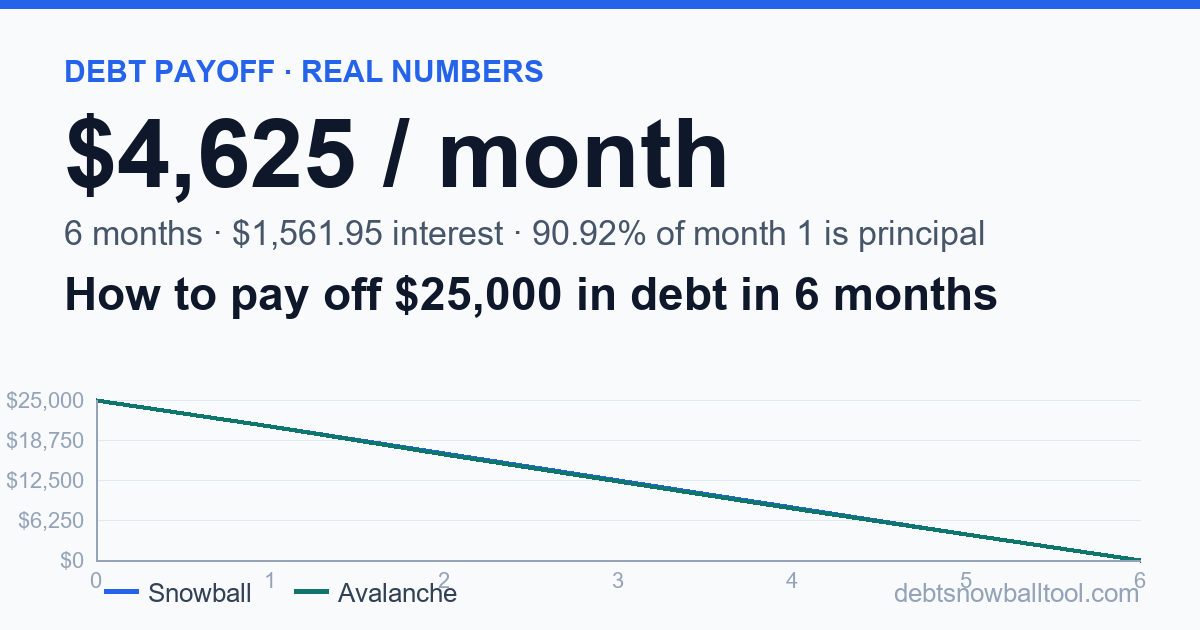
4 cards · $625 minimums · 16-24% APR · 6 months both methods

$25,000 in 6 months: of the first $4,625, $4,205.00 is principal — 90.92% — and the share climbs to 98.04% by month 6 as the interest falls to $81.12.

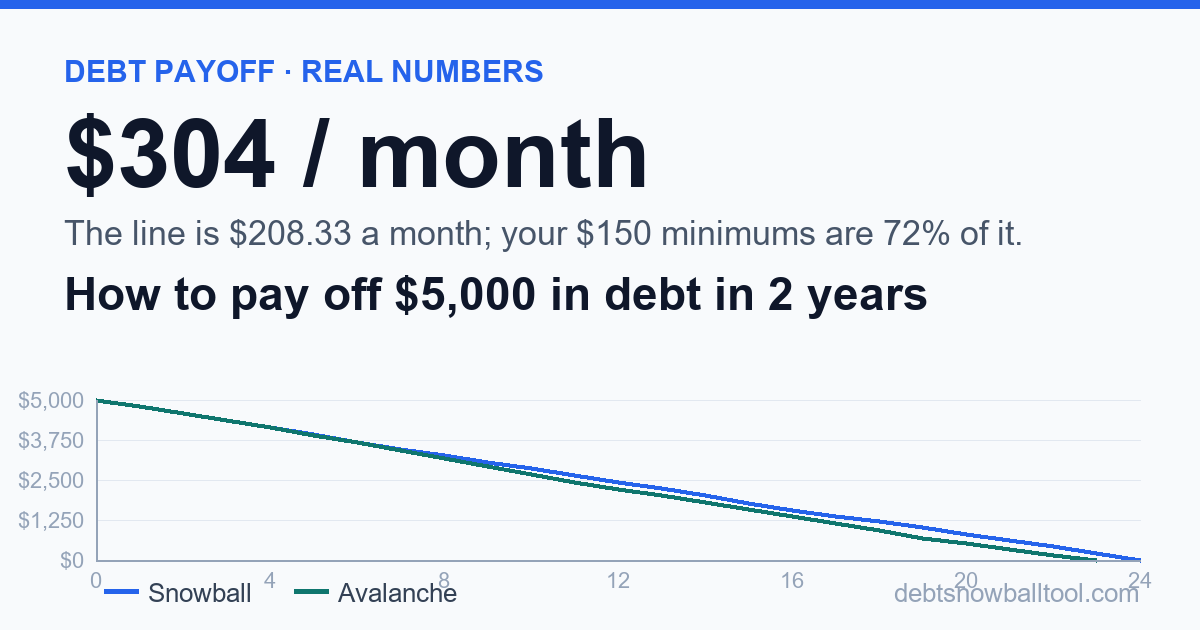
How to pay off $5,000 in 2 years

Three cards totalling $5,000 at 18-26% APR, with $150 in minimums. $5,000 spread over twenty-four months is $208.33 a month of principal with no interest in it — the line. The $150 in minimums is 72.00% of that line and the $304 two-year payment is 145.92% of it, so the plan opens 45.92% above the line and its final payment ends 1.89% above it — 145.92%, 126.72%, 102.72% and 101.89% as each card closes. The further out the deadline, the further above its own line the payment sits: 112.08% at six months, 123.36% at twelve, 145.92% at twenty-four, 166.32% at thirty-six, and 177.00% for the minimums-only run. The whole twenty-four months cost $1,214.28, and at the same $304 avalanche finishes a month early for $208.05 less.

3 cards · $150 minimums · 18-26% APR · 24 months snowball

$5,000 in 2 years: the principal line is $208.33 a month, the $150 in minimums is 72% of it, and the $304 plan is 146% of it.

How to pay off $10,000 in 2 years

Three cards totalling $10,000 at 18-26% APR, with $300 in minimums. At $608 a month the snowball plan clears it in twenty-four months for $2,428.57 in interest — 24.29% of the balance, and $12,428.57 in total. The number worth knowing is what that bill is per month of the run: $101.19 a month across the plan's twenty-four months, against $101.96 across the fifty-nine months the $300 minimums take — 0.76% apart, and the thirty-five months the minimums run longer are worth $3,587.17, which is $102.49 a month. Across five deadlines the bill spans 8.76 times while the price per month spans 1.168 times, because the interest is charged at a rate rather than sold at a price. The one thing that does move the price is the order of the cards: at the same $608, avalanche runs at $87.50 a month and finishes a month early for $416.10 less.

3 cards · $300 minimums · 18-26% APR · 24 months snowball

$10,000 in 2 years: the plan is charged $101.19 a month of interest over twenty-four months and the $300 minimums $101.96 over fifty-nine.

How to pay off $15,000 in 2 years

Four cards totalling $15,000 at 17-24% APR, with $400 in minimums. At $916 a month the snowball plan clears it in twenty-four months for $3,477.64 in interest — 23.18% of the balance, and $18,477.64 in total. The number worth knowing is what that bill is per card, counted in each card's own minimum payment: Card D, the first target, dies in month 4 and is charged $65.48, which is 0.94 of its own $70 minimum, while Card A is the last card in the order and is charged $2,288.11 — 15.25 of its $150 minimum. The four minimums span 2.14 times; what the plan charges them spans 16.3 times. Paying the minimums alone takes 81 months and costs $11,271.94.

4 cards · $400 minimums · 17-24% APR · 24 months snowball

$15,000 in 2 years: counted in each card's own minimum payment, the plan charges Card D 0.94 minimums and Card A 15.25.

How to pay off $20,000 in 2 years

Four cards totalling $20,000 at 15-24% APR, with $500 in minimums. At $1,178 a month the snowball plan clears it in twenty-four months for $4,267.71 in interest — 21.34% of the balance, and $24,267.71 in total. The number worth knowing is that two of the four cards start level at $4,500: Card C is the 22% one and Card D the 15% one. Left to the minimums Card C is charged $3,840.12 against Card D's $1,717.68 — 2.236 times as much — but on the plan it flips, because the plan reaches Card C first and kills it in month 7 for $297.43 while Card D waits until month 12 and is charged $492.59. The 15% card ends up the expensive one, at 1.656 times the 22% card. Paying the minimums alone takes 82 months and costs $14,727.64.

4 cards · $500 minimums · 15-24% APR · 24 months snowball

$20,000 in 2 years: two cards start level at $4,500, and the plan charges the 22% one $297.43 and the 15% one $492.59.

How to pay off $25,000 in 2 years

Four cards totalling $25,000 at 16-24% APR, with $625 in minimums. At $1,495 a month the snowball plan clears it in twenty-four months for $5,809.59 in interest — 23.24% of the balance, and $30,809.59 in total. The number worth knowing is what every payment actually is: the plan is always $870 of new money plus the minimums still owed, so the payment steps $1,495, $1,395, $1,270, $1,095 and the snowball's target card is paid $870 plus its own minimum — $970, then $995, then $1,045, then $1,095. The $870 never grows, so the four cards close in months 5, 10, 16 and 24, windows of 5, 5, 6 and 8 months that stretch rather than shrink. Paying the minimums alone takes 81 months and costs $19,718.70.

4 cards · $625 minimums · 16-24% APR · 24 months snowball

$25,000 in 2 years: the $1,495 plan is the same $870 of new money plus the minimums still owed, so the snowball's target card is paid $970, then $995, then $1,045, then $1,095.

How to pay off $30,000 in 2 years

Five cards totalling $30,000 at 14-22% APR, with $750 in minimums. At $1,777 a month the snowball plan clears it in twenty-four months for $6,117.17 in interest — 20.39% of the balance, and $36,117.17 in total. The number worth knowing is what the same two years cost if the minimums go first: two years of the $750 send $18,000, of which $9,883.30 is interest, and you still owe $21,883.30 — 72.94% of the balance; starting the same $1,777 then takes another 17 months and $3,112.66, so the detour runs 41 months and $12,995.96 — 17 months and $6,878.79 more, which is 1.125 times the plan's whole bill. Avalanche at the same $1,777 pays $5,048.21, a gap of $1,068.96, and finishes a month early.

5 cards · $750 minimums · 14-22% APR · 24 months snowball

The same $30,000 under two paths: the $1,777 plan sends $36,117.17 over twenty-four months, while two years of the $750 minimums first, then the same $1,777, takes forty-one months and costs $12,995.96.

How to pay off $40,000 in 2 years

Five cards totalling $40,000 at 15-24% APR, with $1,000 in minimums. At $2,388 a month the snowball plan clears it in twenty-four months for $8,884.86 in interest — 22.21% of the balance, and $48,884.86 in total, which is 1.222 times the balance. The number worth knowing is what the same $40,000 costs on the other path: paying only the $1,000 minimums takes 82 months and sends $68,678.10 — 3.417 times the time, and $19,793.24 more, or 40.5% more than the plan. At the twenty-four-month mark the minimums have sent $24,000, of which $14,502.17 is interest, and they still owe $30,502.17 — 76.26% of the balance. Avalanche at the same $2,388 pays $7,322.78, a gap of $1,562.08, and finishes in the same month.

5 cards · $1,000 minimums · 15-24% APR · 24 months both methods

The same $40,000 under two paths: the $2,388 plan sends $48,884.86 over twenty-four months, while the $1,000 minimums take eighty-two months and send $68,678.10.

How to pay off $80,000 in 2 years

Five cards totalling $80,000 at 15-25% APR, with $2,000 in minimums. At $4,850 a month the snowball plan clears it in twenty-four months for $18,698.13 in interest — 23.37% of the balance. The number worth knowing is what the deadline makes comparable: the plan's first twelve months send $54,775.00, which is $6,775 more than the minimums send in all twenty-four, and they retire $41,235.66 of principal against the minimums' $17,445.17 — 2.364 times as much. At month 12 the plan owes $38,764.34; at month 24 the minimums still owe $62,554.83, a $23,790.49 gap, and the minimums paid $30,554.83 of interest to get there, $11,856.70 more than the whole plan costs. Avalanche at the same $4,850 pays $15,071.42, a gap of $3,626.71, and finishes a month early.

5 cards · $2,000 minimums · 15-25% APR · 24 months both methods

Twelve months of the $80,000 two-year plan against twenty-four months of the minimums: $54,775 sent against $48,000, $41,235.66 of principal retired against $17,445.17, and $38,764.34 left owing against $62,554.83.

How to pay off $70,000 in 2 years

Five cards totalling $70,000 at 15-25% APR, with $1,750 in minimums. At $4,230 a month the snowball plan clears it in twenty-four months for $16,107.08 in interest — 23.01% of the balance. Paying only the minimums is not one 87-month race, it is five races run side by side, because each minimum is 2.5% of its own card: the cards clear in months 56, 60, 66, 73 and 87. The four fastest are all done at month 73, and Card A alone runs the last 14 months and owns $23,389.98 of the $54,288.30 bill — 43.08% of it. Avalanche at the same $4,230 pays $12,914.46, a gap of $3,192.62, and finishes a month early. On the minimums the same portfolio takes 87 months and costs $54,288.30; twenty-four months of minimums move $42,000 out of your account and leave $54,237.99 still owed.

5 cards · $1,750 minimums · 15-25% APR · 24 months both methods

The $70,000 two-year plan against the five minimums-only races: the plan clears in month 24, while the five cards clear in months 56, 60, 66, 73 and 87.

How to pay off $80,000 in 12 months

Five cards totalling $80,000 at 15-25% APR, with $2,000 in minimums. At $8,178 a month the snowball plan clears it in twelve months for $9,774.99 in interest — 12.22% of the balance. The same twelve months can be paid in two orders, and the two orders are mirrors: snowball clears Card E in month 2, Card D in month 4, Card C in month 6, Card B in month 9 and the $25,000 25% card last of all in month 12, while avalanche clears that same 25% card in month 4 and the smallest card in month 12. Card A is 8 months apart, Card E is 10. The 25% card is 31.25% of the balance but 55.51% of the interest bill — $5,426.54 of the $9,774.99 — and taking it in month 4 instead cuts that to $1,287.10. Avalanche at the same $8,178 pays $8,177.65, a gap of $1,597.34. On the minimums the same portfolio takes 87 months and costs $64,021.79; twelve months of minimums move $24,000 out of your account and leave $72,132.63 still owed.

5 cards · $2,000 minimums · 15-25% APR · 12 months both methods

When each of the five cards on the $80,000 twelve-month plan is cleared: Card A in month 12 under snowball and month 4 under avalanche, Card E in month 2 and month 12.

How to pay off $80,000 in 6 months

Five cards totalling $80,000 at 15-25% APR, with $2,000 in minimums. At $14,868 a month the snowball plan clears it in six months for $5,257.39 in interest — 6.57% of the balance. The payments fall every month and the debt does not: they go $14,868, $14,668, $14,343, $13,943, $13,943 and $13,492.39, a drop of 9.25%, while the balance retired is $13,466.33, $13,445.30, $13,325.31, $13,152.31, $13,393.71 and $13,217.04 — a $314.02 band, or 2.33%. 99.96% of the drop in the payment is minimums the plan has stopped owing. Avalanche at the same $14,868 pays $4,495.83, a gap of $761.56. On the minimums the same portfolio takes 87 months and costs $64,021.79; six months of minimums move $12,000 out of your account and leave $76,259.06 still owed.

5 cards · $2,000 minimums · 15-25% APR · 6 months both methods

The $80,000 six-month plan: six bars of nearly the same height showing the balance retired each month ($13,152 to $13,466), against a line that falls from $14,868 in month 1 to $13,492.39 in month 6.

How to pay off $70,000 in 12 months

Five cards totalling $70,000 at 15-25% APR, with $1,750 in minimums. At $7,164 a month the snowball plan clears it in twelve months for $8,442.15 in interest — 12.06% of the balance — and the year's interest is not twelve equal slices: month 1 is charged $1,207.50 and month 12 only $120.67, ten times less. The first six months carry 71.17% of the bill while retiring 50.68% of the balance, and not one of the first six monthly charges falls below the flat average of $703.51, nor one of the last six above it. Avalanche at the same $7,164 pays $6,967.53, a gap of $1,474.62. On the minimums the same portfolio takes 87 months and costs $54,288.30; twelve months of minimums move $21,000 out of your account and leave $62,878.36 still owed.

5 cards · $1,750 minimums · 15-25% APR · 12 months both methods

Interest charged each month on the $70,000 twelve-month plan: month 1 is $1,207.50 and month 12 is $120.67, and the first six months all sit above the flat monthly average of $703.51 while the last six all sit below it.

How to pay off $70,000 in 6 months

Five cards totalling $70,000 at 15-25% APR, with $1,750 in minimums. At $12,992 a month the snowball plan clears it in six months for $4,545.74 in interest, and every one of the six payments stays above $11,700. The page is built around the size of the ask in a unit you can feel: $11,242 a month of new money is 104 hours a week at $25 an hour, about 62% of every hour a week has. The same $70,000 on a twelve-month deadline is 50 hours a week, on twenty-four months 23, on thirty-six months 14 — and on the minimums it is 0 hours a week and 87 months, at a cost of $54,288.30 in interest. Six months of the minimums move $10,500 out of your account and leave $66,610.62 still owed. Avalanche at the same $12,992 pays $3,851.45, a gap of $694.29.

5 cards · $1,750 minimums · 15-25% APR · 6 months both methods

Five deadlines for the same $70,000 measured in extra hours a week at $25: 6 months is 104 hours, 12 months is 50, 24 months is 23, 36 months is 14, and the minimums are 0 hours over 87 months

How to pay off $60,000 in 2 years

Five cards totalling $60,000 at 15-25% APR, with $1,500 in minimums. At $3,616 a month the snowball plan clears it in twenty-four months for $13,943.21 in interest, and the twenty-four payments step down as cards leave, ending at $2,550.21 in the last month. The page is built around what the same twenty-four months do on the minimums: $36,000 out of your account, and $46,725.18 still owed — 77.88% of the balance, because only $13,274.82 of that $36,000 reaches principal. The plan sends $73,943.21 and ends at zero. Avalanche at the same $3,616 finishes a month early, in 23 months for $11,243.80. Minimums only: 87 months and $47,341.20.
5 cards · $1,500 minimums · 15-25% APR · 24 months

Two balance curves from $60,000 over twenty-four months: the $3,616 plan falls to zero while the $1,500 minimums are still at $46,725.18

How to pay off $60,000 in 12 months

Five cards totalling $60,000 at 15-25% APR, with $1,500 in minimums. At $6,148 a month the snowball plan clears it in twelve months for $7,286.11 in interest, and the twelve payments step down as cards leave: $6,148, $6,148, $5,983, $5,983, $5,728, $5,728, $5,428, $5,428, $5,428, $5,098, $5,098 and $5,088.11 — $67,286.11 in total, 12.14% of the balance being interest. The page is built around the size of that payment: it is smaller than every one of the five balances, the smallest of which is $6,600, so the month-1 payment falls $452 short of even that card and no single payment retires a card outright. The same five cards on a six-month clock need $11,166 a month. Minimums only: 87 months and $47,341.20.
5 cards · $1,500 minimums · 15-25% APR · 12 months both methods

Five card balances from $18,000 down to $6,600 with a dashed line at $6,148, one month of the twelve-month plan, sitting below all five

How to pay off $60,000 in 6 months

Five cards totalling $60,000 at 15-25% APR, with $1,500 in minimums. At $11,166 a month the snowball plan clears it in six months for $3,920.79 in interest, and every one of the six payments stays above $10,000. The page is built around what actually sets the clock: on minimums only, $60,000 takes the same 87 months as $50,000 — a card minimum is 2.5% of the balance, so twenty percent more debt brings a twenty percent bigger minimum and no extra month. The six payments run $11,166, $11,001, $10,746, $10,446, $10,446 and $10,115.79 — $63,920.79 in total, 6.53% of the balance being interest. Minimums only: 87 months and $47,341.20.

5 cards · $1,500 minimums · 15-25% APR · 6 months both methods

Snowball and avalanche payoff curves on a $60,000 portfolio at $11,166 a month over six months, with $3,920.79 of interest

How to pay off $50,000 in 12 months

Five cards totalling $50,000 at 15-25% APR, with $1,250 in minimums. At $5,123 a month the snowball plan clears it in twelve months for $6,072.03 in interest. The page is built around the size of that interest bill: the whole year's interest is 1.19 times one month's payment, and the total out of your account is $56,072.03 — 12.14% of it interest. The twelve payments run $5,123, $5,123, $4,986, $4,986, $4,773, $4,773, $4,523, $4,523, $4,523, $4,248, $4,248 and $4,243.03. Minimums only: 87 months and $39,456.55.

5 cards · $1,250 minimums · 15-25% APR · 12 months both methods

Bar chart on a $50,000 portfolio: the first month's interest is $870.00, one month of the twelve-month plan is $5,123, and the whole year's interest is $6,072.03 — longer than the payment

How to pay off $50,000 in 6 months

Five cards totalling $50,000 at 15-25% APR, with $1,250 in minimums. At $9,305 a month the snowball plan clears it in six months for $3,267.29 in interest. The page is built around the size of that single payment: one month of the plan is bigger than the whole of Card D ($8,500) and the whole of Card E ($5,500), so the first two months each retire a card outright. The six payments are $9,305, $9,168, $8,955, $8,705, $8,705 and $8,429.29 — $53,267.29 in total, 6.53% of the balance being interest. Minimums only: 87 months and $39,456.55.

5 cards · $1,250 minimums · 15-25% APR · 6 months both methods

Horizontal bars placing the $9,305 monthly payment of a six-month $50,000 payoff between Card C at $10,000 and Card D at $8,500, with Card E at $5,500 below

How to pay off $40,000 in 6 months

Five cards totalling $40,000 at 15-24% APR, with $1,000 in minimums. At $7,425 a month the snowball plan clears it in six months for $2,510.83 in interest. The page is built around the deadline itself: $7,425 buys six months, and $7,424 — one dollar less — buys seven, for just $0.35 more interest. The seventh payment is $4.18. Avalanche has its own threshold at $7,339, with the same one-dollar cliff at $7,338 costing $0.32. Six months of the plan is 6.28% of the balance and 5.91% of the $42,510.83 that leaves your account. Minimums only: 82 months and $28,678.10.

5 cards · $1,000 minimums · 15-24% APR · 6 months both methods

Two bars of interest on the same $40,000 portfolio: $2,510.83 at the $7,425 six-month payment and $2,511.18 at $7,424, which slips to seven months

How to pay off $30,000 in 6 months

Five cards totalling $30,000 at 14-22% APR, with $750 in minimums. At $5,536 a month the snowball plan clears it in six months for $1,736.74 in interest. The page is built around one yardstick: a balance that never moves would be charged $2,800.00 for half a year at this portfolio's balance-weighted 18.67% APR, and the plan pays 62.03% of that (5.79% of the $30,000). Six months of minimum payments roll up $2,734.93 — 97.68% of the flat half-year, because the interest barely declines when you only pay minimums: $466.67 in month 1, $444.75 in month 6. Minimums only: 73 months and $18,014.10.

5 cards · $750 minimums · 14-22% APR · 6 months both methods

Three bars on one scale: six-month interest of $2,800.00 on a balance that never moves, $2,734.93 on minimum payments, and $1,736.74 on a six-month payoff plan

How to pay off $20,000 in 6 months

Four cards totalling $20,000 at 15-24% APR, with $500 in minimums. At $3,688 a month the snowball plan clears it in six months for $1,216.88 in interest — 6.08% of the balance. The page is built around a single month: month 1 is charged $337.92 of interest whether you send the $500 minimums or the $3,688 plan payment, because interest is charged on the balance and not on the payment. What changes is the share of the payment it eats — 67.58% of $500 against 9.16% of $3,688, a factor of 7.38. Across the six months interest is 5.74% of the $21,216.88 that leaves your account, and the minimums floor thins, so the six months cost $21,216.88, not $22,128. Minimums only: 82 months and $14,727.64.

4 cards · $500 minimums · 15-24% APR · 6 months both methods

Two bars on one dollar scale: month 1 of a $20,000 payoff at the $500 minimums and at the $3,688 six-month payment, with the same $337.92 interest slice in both

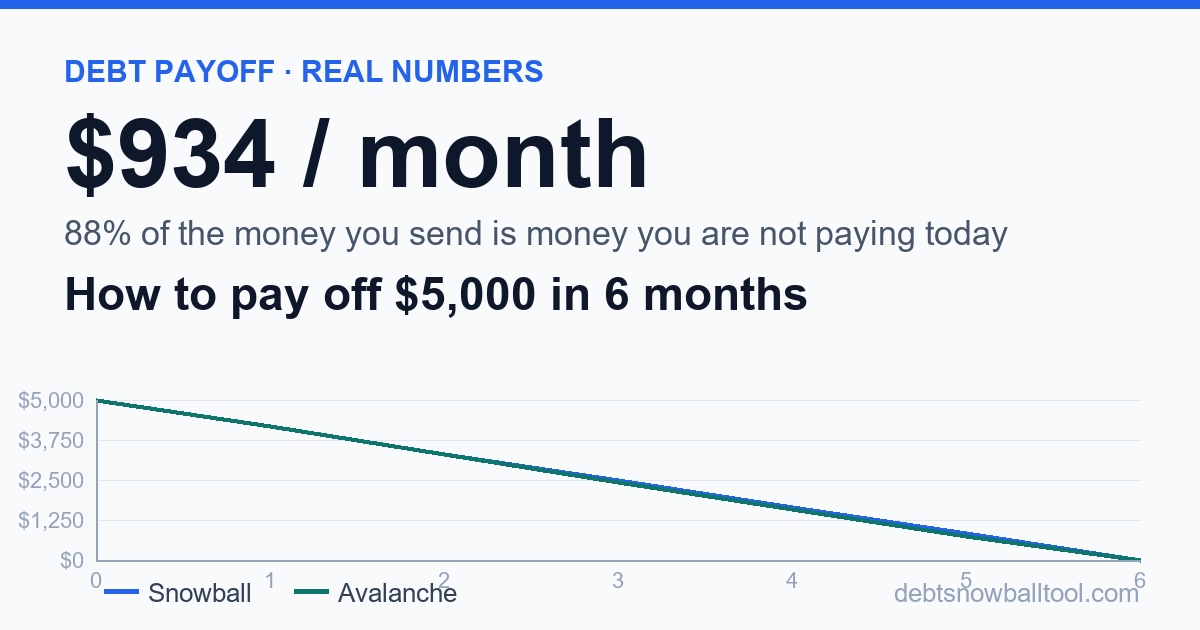
How to pay off $5,000 in 6 months

Three cards totalling $5,000 at 18-26% APR, with $150 in minimums. At $934 a month the snowball plan clears it in six months for $343.42 in interest — 6.87% of the balance. The page is built around the payment instead: of the $5,343.42 that leaves your account, 88.02% ($4,703.42) is money you are not paying today, and there is $13.70 of new money behind every $1 of interest. The minimums line falls from $150 to $60 as cards clear, so the six months cost $5,343.42, not $5,604. Minimums only: 59 months and $3,007.87.

3 cards · $150 minimums · 18-26% APR · 6 months both methods

Stacked bars: the $934 monthly payment on a $5,000 six-month payoff split into the minimums already being paid and the new money to be found

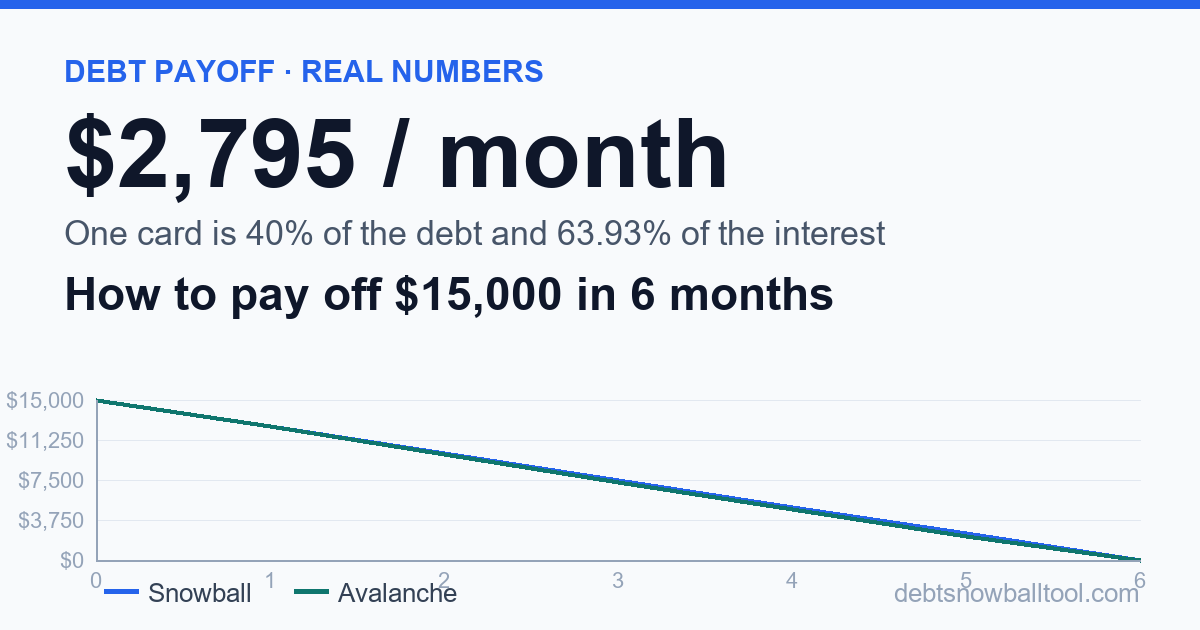
How to pay off $15,000 in 6 months

Four cards totalling $15,000 at 17-24% APR, with $400 in minimums. At $2,795 a month the snowball plan clears it in six months for $977.62 in interest — but the interest is not spread the way the balances are. Card A, the $6,000 balance at 24%, is 40.00% of the debt and carries 63.93% of the plan's interest ($624.99 of $977.62); Card D, the $2,000 balance at 17%, is 13.33% of the debt and 2.90% of the interest. Per $1,000 of balance that is $104.17 against $14.17. The six months cost $15,977.62, not $16,770. Minimums only: 81 months and $11,271.94.

4 cards · $400 minimums · 17-24% APR · 6 months both methods

Bar chart: each card's share of the $15,000 balance against its share of the plan's $977.62 interest

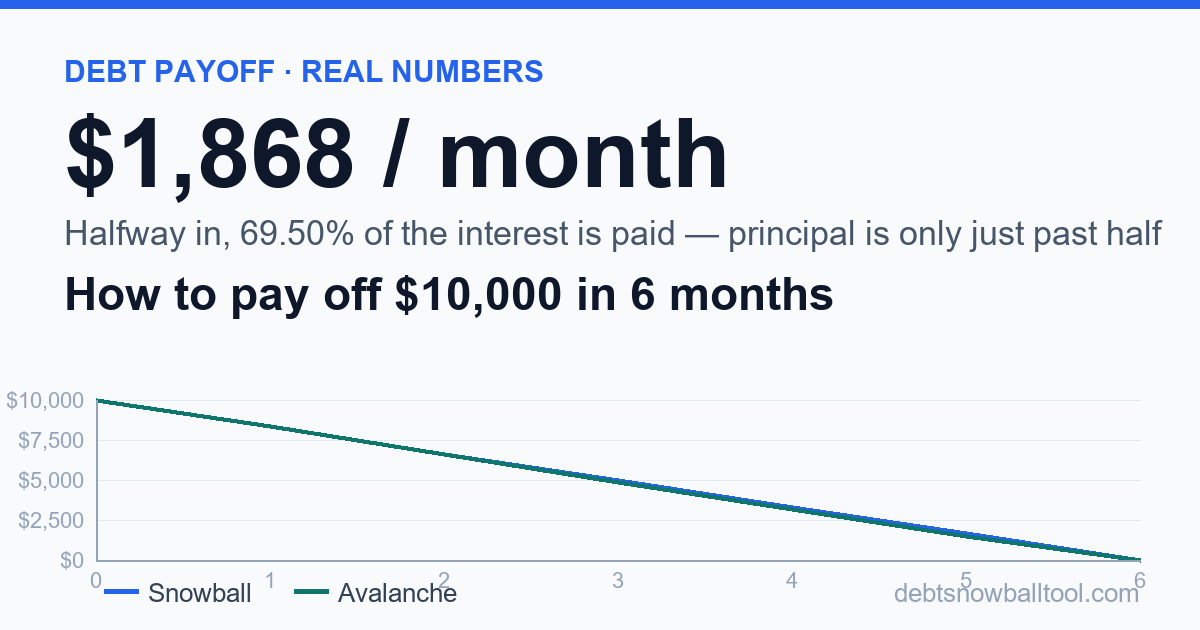
How to pay off $10,000 in 6 months

Three cards totalling $10,000 at 18-26% APR, with $300 in minimums. At $1,868 a month the snowball plan clears it in six months for $686.83 in interest — but the page is built around the halfway point: by the end of month 3 you have already paid 69.50% of the plan's interest ($477.32 of $686.83) while principal is only just past half at 50.47% ($5,046.68 of $10,000). The payment also steps down, so the six months cost $10,686.83, not $11,208. Minimums only: 59 months and $6,015.74.

3 cards · $300 minimums · 18-26% APR · 6 months both methods

Snowball vs avalanche curves on $10,000 at $1,868 a month over 6 months

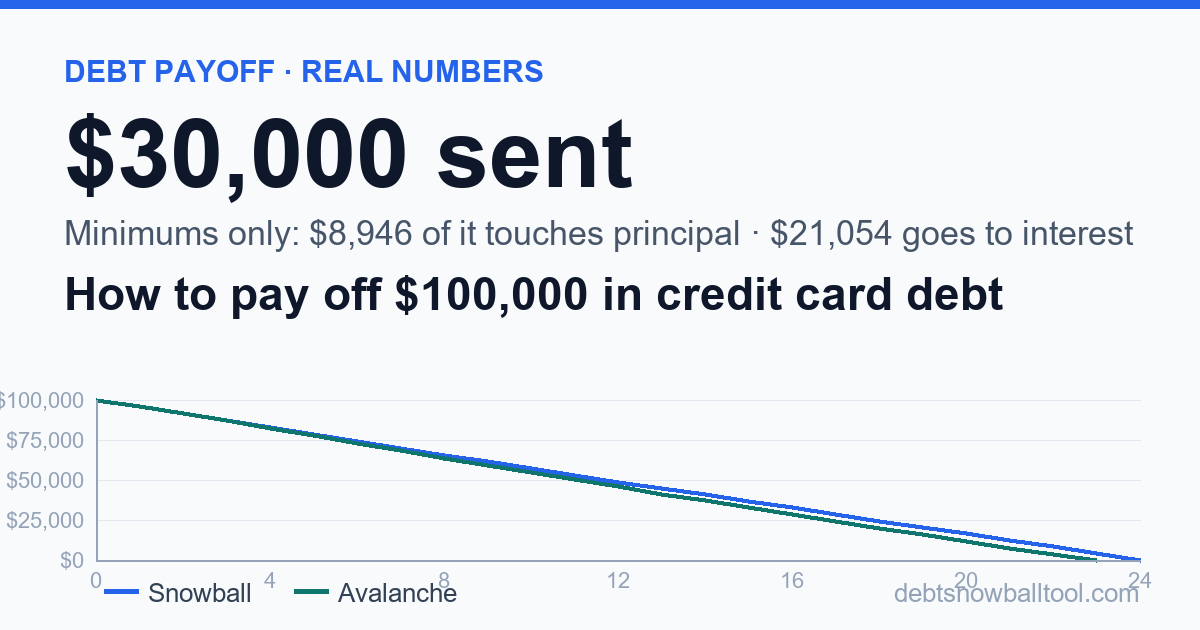
How to pay off $100,000 in credit card debt

Five cards totalling $100,000 at 16-26% APR, with $2,500 in minimums. The page measures where the first year's money actually lands: on minimums you send $30,000 and only $8,946.23 of it reaches principal, while $21,053.77 goes to interest and you still owe $91,053.77. At $6,085 a month (24 months) $51,429.03 of the $69,020 sent reaches principal; at $10,297 (12 months) $100,000 of $112,702.79 does. Minimums only: 94 months and $88,986.65.

5 cards · $2,500 minimums · 16-26% APR · 12 / 24 / 36-month plans

Snowball vs avalanche curves on $100,000 at $6,085 a month over 24 months

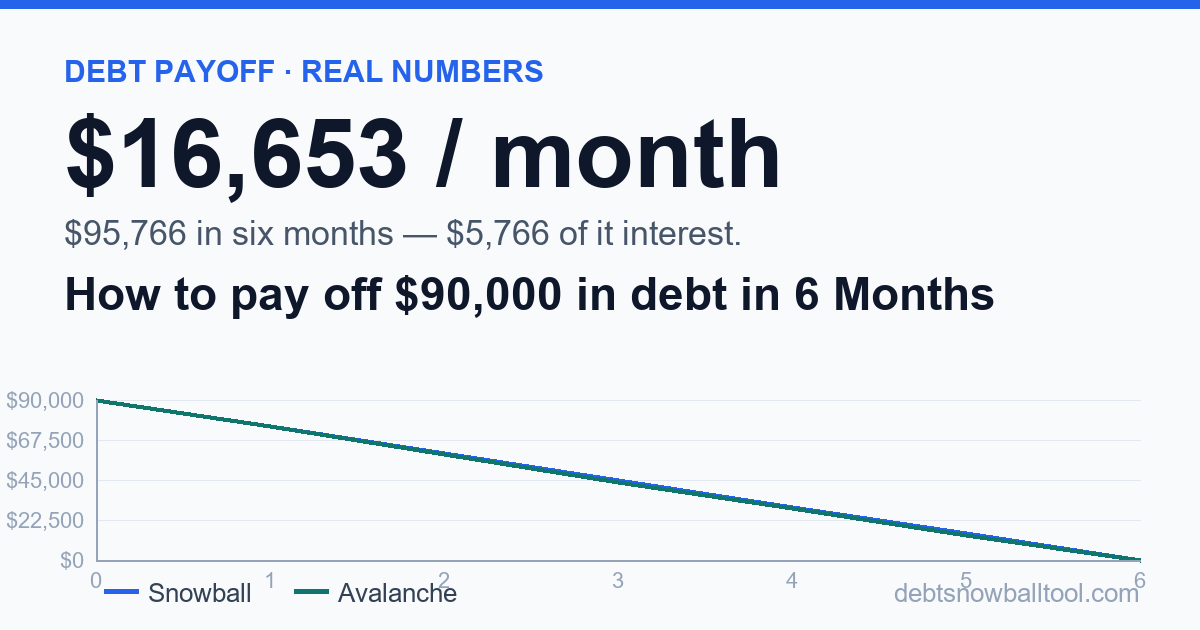
How to pay off $90,000 in debt in 6 months

Four cards totalling $90,000 at 15-24% APR, with $2,250 in minimums. The standout is Card A: $34,000 at 24% is both the largest balance and the highest rate, so snowball saves it for last (cleared month 6) and avalanche attacks it first (month 3). At $16,653 a month snowball finishes in 6 months for $5,766.25 in interest; avalanche at $16,432 lands the same month for $5,082.21 — $684.04 less. Paying the $2,250 minimums only takes 81 months and costs $69,986.41.

4 cards · $2,250 minimums · 15-24% APR · 6 months both methods

$90,000 in 6 months: Card A is $34,000 at 24%, the largest balance and the highest rate, so snowball saves it for last.

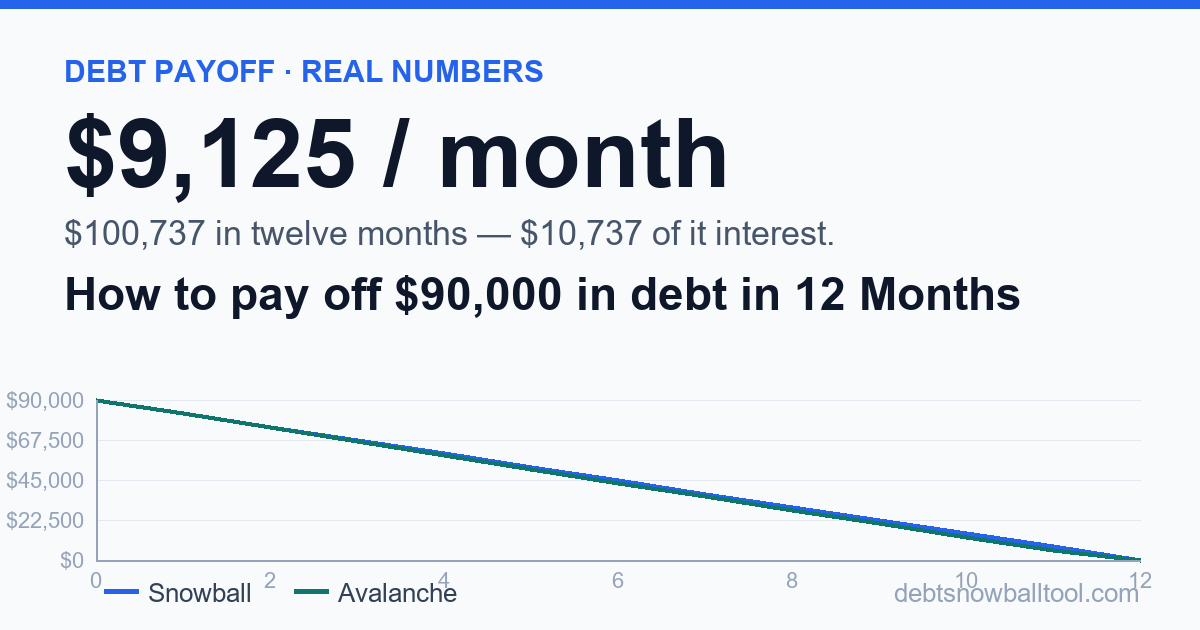
How to pay off $90,000 in debt in 12 months

Four cards totalling $90,000 at 15-24% APR, with $2,250 in minimums. Card A ($34,000 at 24%) is the dominant card — on snowball it is charged $6,825.18 and cleared in month 12; on avalanche it is charged $1,962.54 and cleared in month 5. At $9,125 a month snowball finishes in 12 months for $10,736.74 in interest; avalanche at $8,986 lands the same month for $9,270.16 — $1,466.58 less. Minimums only: 81 months and $69,986.41.

4 cards · $2,250 minimums · 15-24% APR · 12 months both methods

$90,000 in 12 months: snowball charges Card A $6,825.18, avalanche $1,962.54 — the gap is the whole avalanche advantage.

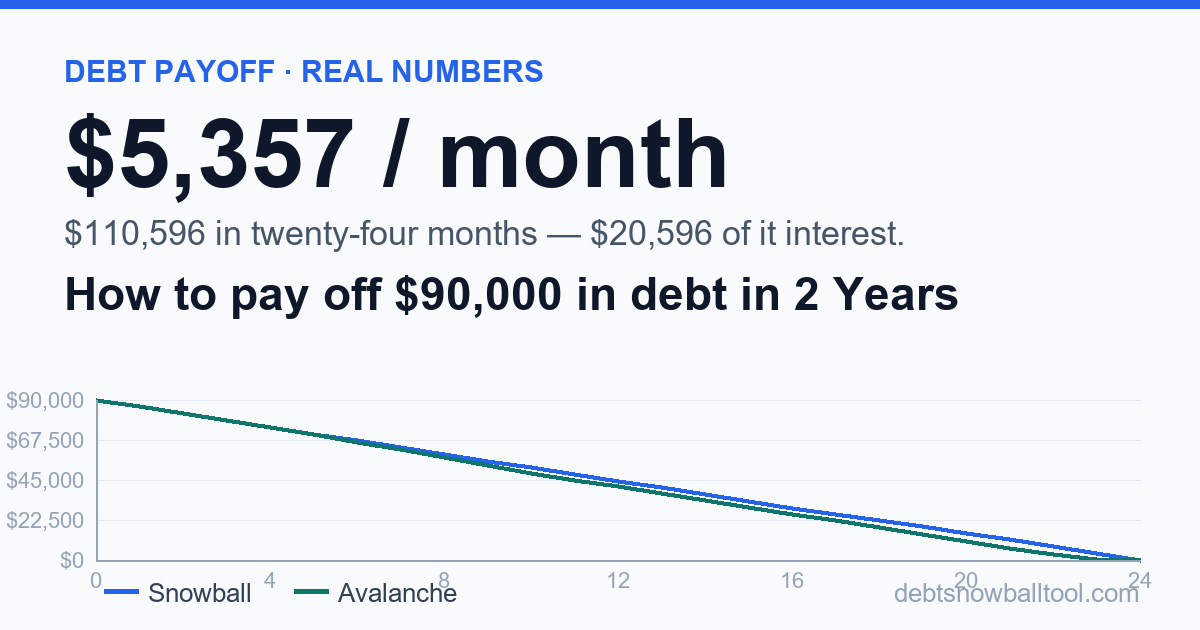
How to pay off $90,000 in debt in 2 years

Four cards totalling $90,000 at 15-24% APR, with $2,250 in minimums. The longer the deadline, the more Card A (the $34,000 at 24%) costs under snowball: it is charged $13,097.23 and cleared in month 24, against $3,687.76 and month 10 on avalanche. At $5,357 a month snowball finishes in 24 months for $20,596.45 in interest; avalanche at $5,165 lands the same month for $17,270.82 — $3,325.63 less. Minimums only: 81 months and $69,986.41.

4 cards · $2,250 minimums · 15-24% APR · 24 months both methods

$90,000 in 2 years: under snowball Card A is charged $13,097.23; under avalanche $3,687.76.

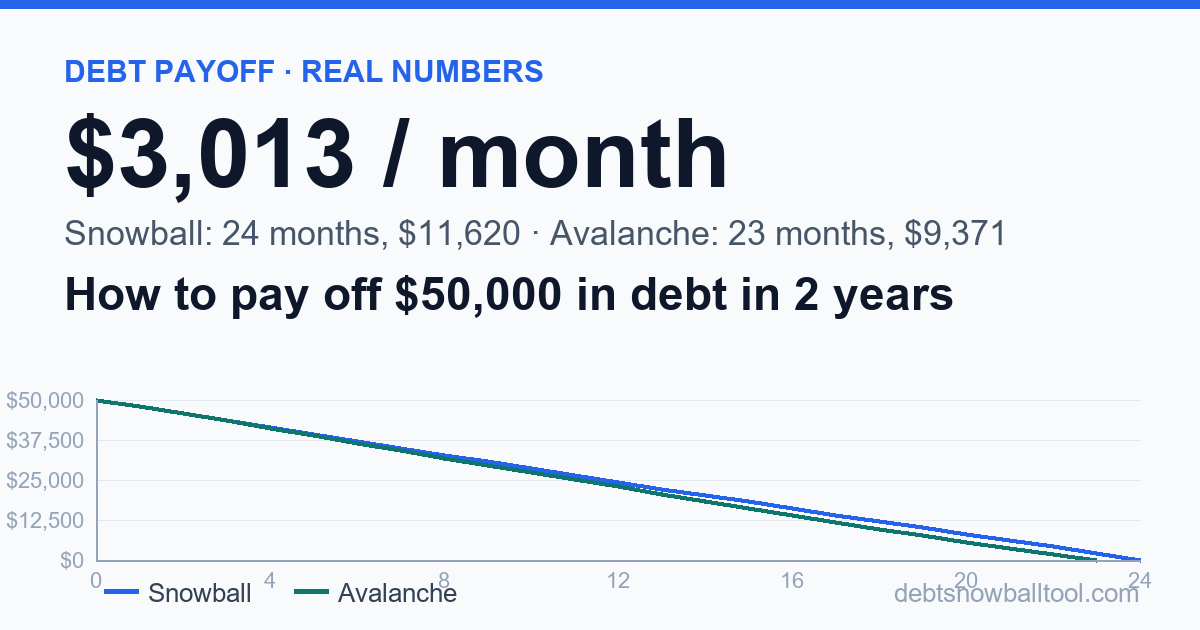
How to pay off $50,000 in debt in 2 years

Five cards totalling $50,000 at 15-25% APR. At $3,013 a month snowball finishes in 24 months and avalanche in 23, and avalanche saves $2,249.17. The page is built around what the second year costs: dropping from a one-year plan at $5,123 a month takes $2,110 off the monthly payment and adds $5,548.32 in interest — $2.63 of extra interest per $1 of monthly relief. Minimums only: 87 months and $39,456.55.

5 cards · $1,250 minimums · 15-25% APR · 24 months snowball, 23 avalanche

Snowball vs avalanche curves on $50,000 at $3,013 a month over 24 months

How to pay off $40,000 in debt in 12 months

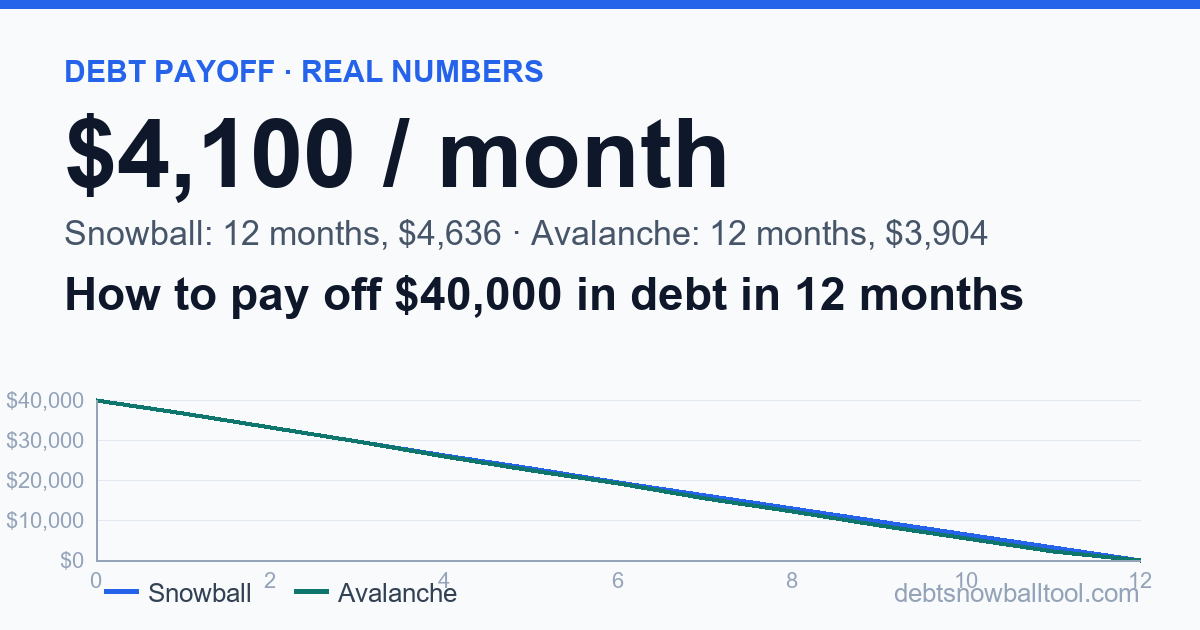
Five cards totalling $40,000 at 15-24% APR. At $4,100 a month both methods finish in 12 months and avalanche saves $731.91 — and unlike the smaller cases, snowball here kills its first card in month 2. Minimums only: 82 months and $28,678.10, which is 71.7% of the balance paid again in interest. The method gap is widest in the middle, at $1,200 a month, where the two methods are 14 months and $4,880.60 apart.

5 cards · $1,000 minimums · 15-24% APR · both methods 12 months

Snowball vs avalanche curves on $40,000 at $4,100 a month

How to pay off $5,000 in debt in 1 year

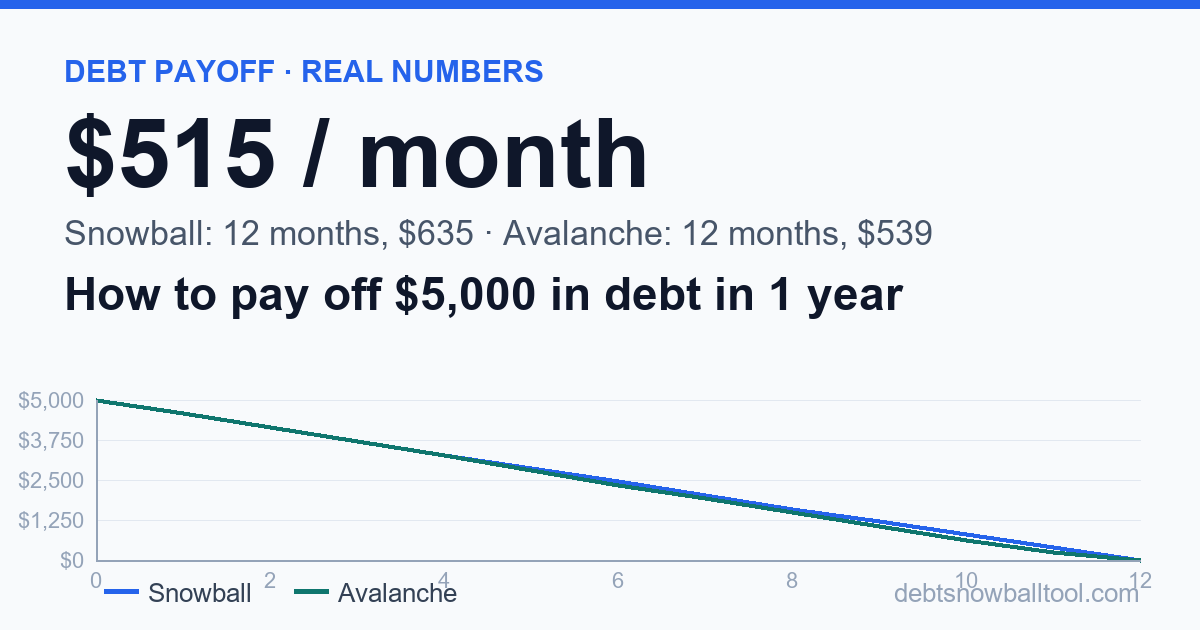
Three cards totalling $5,000 at 18-26% APR. At $515 a month both methods finish in 12 months and avalanche saves $95.93 — but the striking finding is at the bottom: on minimums the two methods are identical, same order, same month, $1.39 apart. Minimums only: 59 months and $3,007.87.

3 cards · $150 minimums · 18-26% APR · both methods 12 months

Snowball vs avalanche curves on $5,000 at $515 a month

How to pay off $30,000 in debt in 1 year

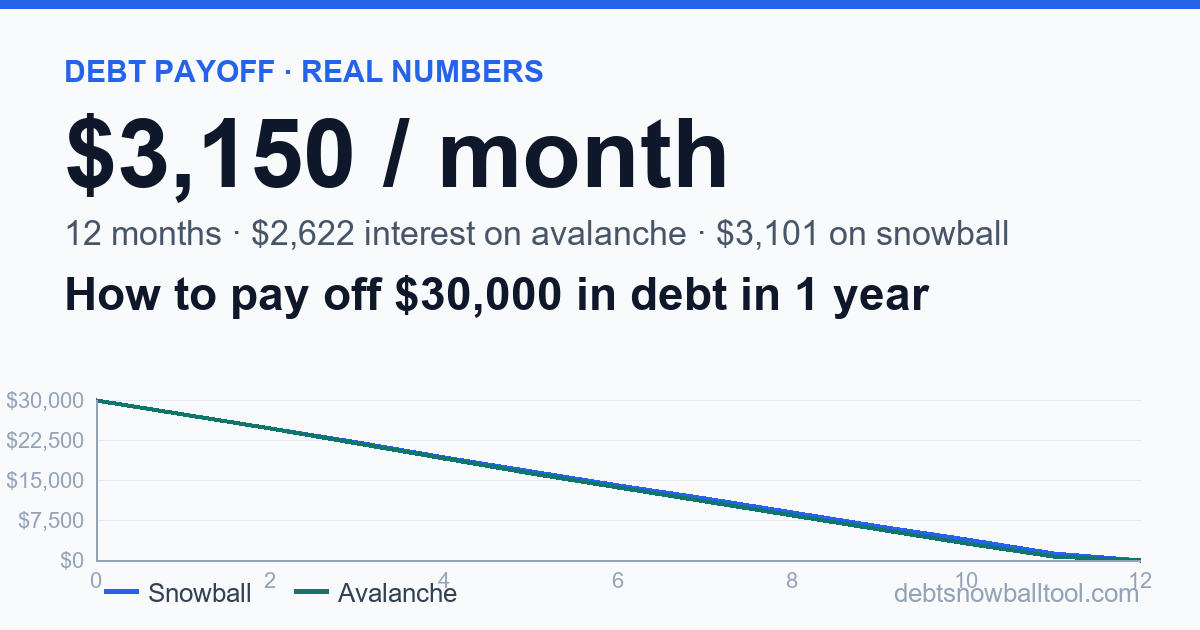
Five cards totalling $30,000 at 14-22% APR. $3,150 a month clears it in 12 months on both methods; avalanche pays $2,622 in interest versus $3,101 on snowball. Paying the $750 minimum only takes 73 months and costs $18,014.

5 cards · $750 minimums · 14-22% APR · 12 months both methods

Snowball vs avalanche curves on $30,000 at $3,150 a month

How to pay off $20,000 in debt in 1 year

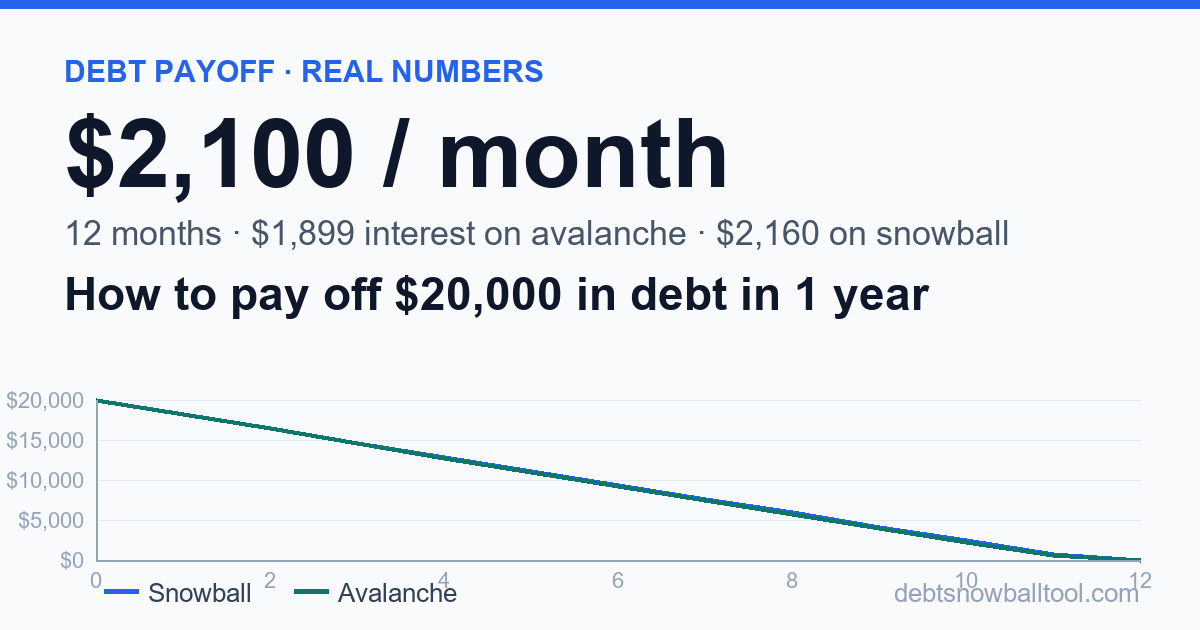
Four cards totalling $20,000 at 15-24% APR. $2,100 a month clears it in 12 months; avalanche pays $1,899 in interest versus $2,160 on snowball. Paying the $500 minimum only takes 82 months and costs $14,728.

4 cards · $500 minimums · 15-24% APR · 12 months both methods

Snowball vs avalanche curves on $20,000 at $2,100 a month

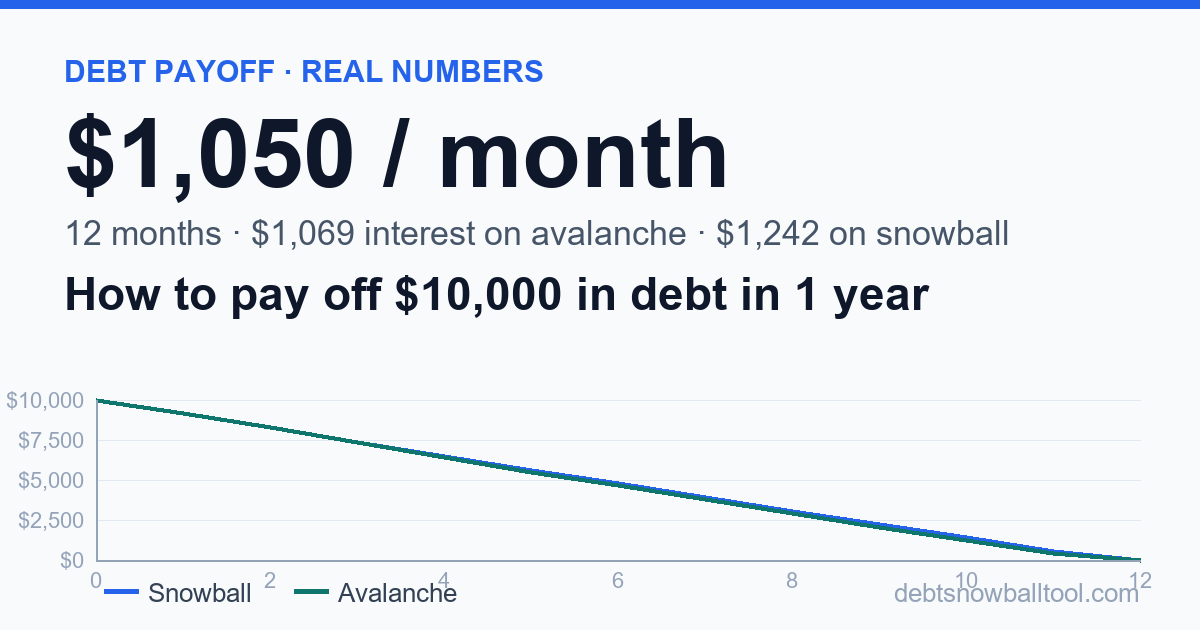
How to pay off $10,000 in debt in 1 year

Three cards totalling $10,000 at 18-26% APR. $1,050 a month clears it in 12 months on both methods; avalanche pays $1,069.09 in interest versus $1,242.01 on snowball. Paying the $300 minimum only takes 59 months and costs $6,015.74.

3 cards · $300 minimums · 18-26% APR · 12 months both methods

Snowball vs avalanche curves on $10,000 at $1,050 a month

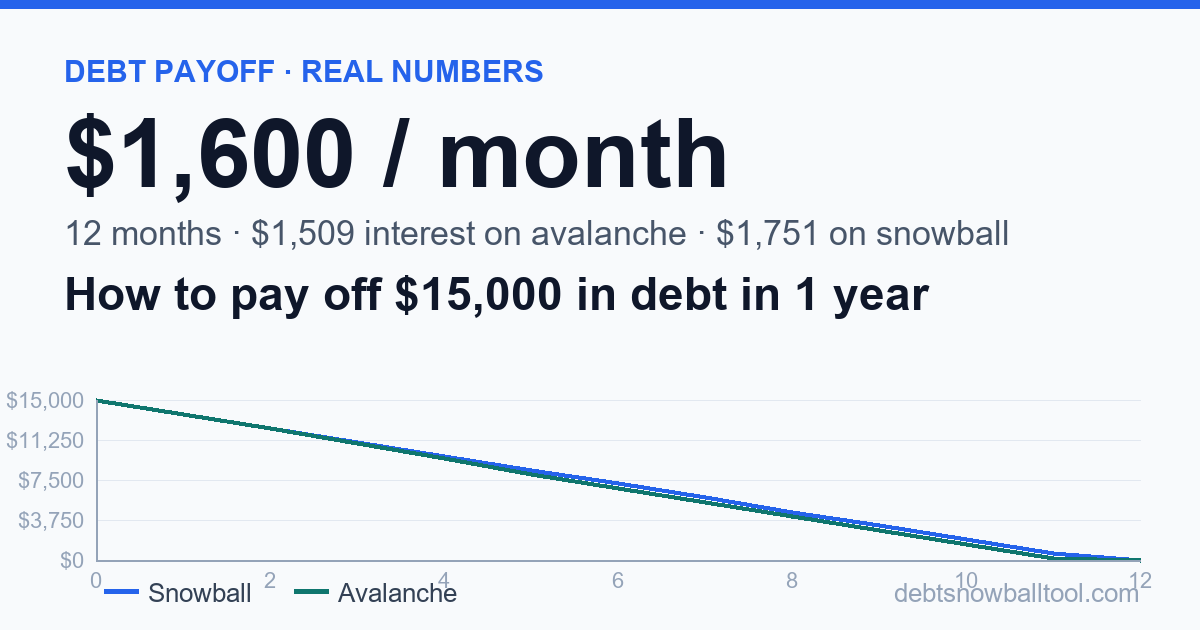
How to pay off $15,000 in debt in 1 year

Four cards totalling $15,000 at 17-24% APR. $1,600 a month clears it in 12 months on both methods; avalanche pays $1,508.69 in interest versus $1,751.42 on snowball. Paying the $400 minimum only takes 81 months and costs $11,271.94.

4 cards · $400 minimums · 17-24% APR · 12 months both methods

Snowball vs avalanche curves on $15,000 at $1,600 a month

How to pay off $25,000 in debt in 1 year

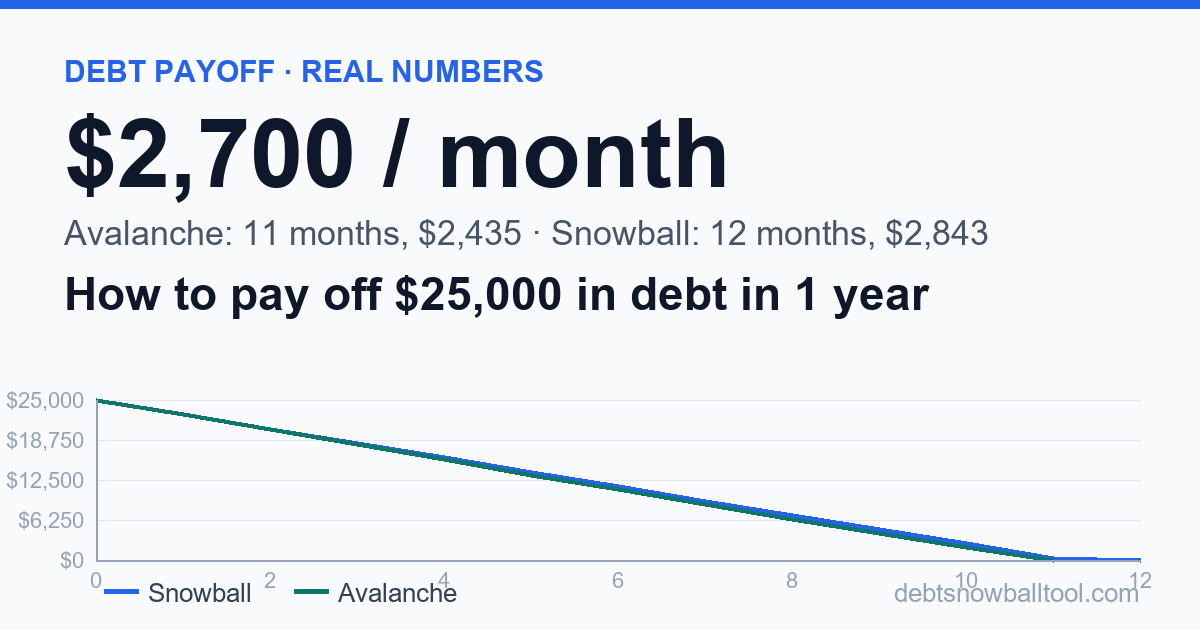
Four cards totalling $25,000 at 16-24% APR. At $2,700 a month snowball finishes in 12 months and avalanche in 11 — the first size in this series where the method changes the finish line. Avalanche pays $2,434.60 in interest versus $2,843.35. Minimums only: 81 months and $19,718.70.

4 cards · $625 minimums · 16-24% APR · avalanche 11 months, snowball 12

Snowball vs avalanche curves on $25,000 at $2,700 a month

Coming next

These are written and published one at a time. The order is set by what people search for (Google Suggest + People Also Ask, 1,000+ queries harvested and ranked by intent).

How each case study is built

  1. A representative credit-card shape for the dollar amount: how many cards, what balances, what minimums, what APRs. Picked from typical US rewards-card stacks, not a worst-case or a best-case.
  2. The monthly payment that fits the time goal (usually 12 months). Found by sweeping extra against this site's public API until both methods finish in the target month.
  3. What minimums-only costs on the same portfolio. Usually 7 to 8 years and an interest number close to the original balance.
  4. The monthly payment sweep, from minimums up to the time-goal payment, with both methods' months and interest. Lets readers locate their own budget without guessing.
  5. Where each card dies month-by-month under both methods. Snowball and avalanche agree at high payments and diverge at low payments; this table shows the actual numbers.
  6. Five concrete sources of the extra cash the case requires — sell something, add income, pause above-match retirement contributions, refinance the biggest monthly line, use a 0% transfer if the math clears.
  7. A copy-pasteable API call so the reader can rerun the same numbers with their own balances and rates.

What these case studies do not cover

Time limits on collections, what happens if you stop paying, changes to debt-collection rules — those depend on your jurisdiction and on rules that change. They are answered in /questions's last section, or by a licensed advisor.