Numbers from this site's public API on a 5-card $40,000 portfolio at 15-24% APR. Open the calculator with your own balances and rates and the same numbers come out in real time.
The example portfolio
$40,000 is the first size in this series where the minimum payments alone cross $1,000 a month, and that single fact changes the shape of the problem. At smaller balances the minimums are an annoyance you pay on the way to the real payment. Here they are a quarter of the whole plan, and they are also the thing that quietly keeps you in debt for seven years if nothing else changes. The example below uses five US credit cards, with the largest balance carrying the highest rate and the smallest carrying the lowest — the shape where snowball and avalanche genuinely disagree.
| Card | Balance | Min payment | APR |
|---|---|---|---|
| Card A | $12,000 | $300 | 24% |
| Card B | $9,000 | $225 | 21% |
| Card C | $8,000 | $200 | 19% |
| Card D | $6,500 | $163 | 17% |
| Card E | $4,500 | $112 | 15% |
| Total | $40,000 | $1,000 | — |
Card E is the smallest and the cheapest. Card A is the largest and the most expensive. Snowball goes after E first because it is small. Avalanche goes after A first because it is expensive. Both reach zero in month 12 at $4,100 a month — and unlike the smaller cases in this series, the two orders do something visibly different on the way there.
What minimums-only actually costs on $40,000
This is the number that almost never appears next to a one-year headline. Sending $1,000 a month — the minimums, nothing more — clears this portfolio in 82 months, which is close to seven years, and interest comes to $28,678.10. You repay the $40,000 and then pay another 71.7% of it again in interest. The total bill is $68,678.10.
| Method | Payoff order | Months | Total interest |
|---|---|---|---|
| Snowball | E (m57) → D (m59) → C (m64) → B (m69) → A (m82) | 82 | $28,678.10 |
| Avalanche | E (m57) → D (m60) → C (m64) → B (m70) → A (m80) | 80 | $28,535.63 |
Note the difference from the smaller cases. On a $5,000 portfolio at minimums, snowball and avalanche are identical — same order, same month, $1.39 apart — because proportional minimums leave nothing to focus. At $40,000 that stops being true. Here the two methods do split: 82 months against 80, and $142.47 of interest. The reason is arithmetic, not magic. Minimums are a percentage of each balance, but on a $12,000 card the interest charge is large enough that the minimum barely outruns it, so which card gets the leftover dollars first finally makes a visible difference.
Two months and $142 is still a rounding error next to the $28,678. The honest reading is this: at minimums, the method question is close to irrelevant at every size — but at $40,000 it is no longer exactly irrelevant, and the direction of the split is the same as everywhere else.
Both methods finish in 12 months at $4,100/month
At $4,100 a month the two payoff orders diverge properly. Snowball kills the $4,500 card in month 2 and works upward. Avalanche goes straight at the 24% card and never touches anything else until month 4. Both finish at month 12. Avalanche costs $731.91 less.
| Method | Payoff order | Months | Total interest |
|---|---|---|---|
| Snowball | E (m2) → D (m4) → C (m6) → B (m9) → A (m12) | 12 | $4,635.85 |
| Avalanche | A (m4) → B (m7) → C (m9) → D (m11) → E (m12) | 12 | $3,903.94 |
Here is the part most method arguments skip. On this portfolio, choosing avalanche over snowball is worth $731.91. Going from minimums to $4,100 a month is worth $24,042.25 and 70 months. The payment size is about 33 times more powerful than the method. If you are arguing about card order while your monthly payment stays flat, you are optimising the wrong variable.
But there is a second, opposite finding at this size, and it is the one that makes the $40,000 case interesting. At $4,100 a month, snowball delivers its first kill in month 2 — a $4,500 card gone before the first quarter is out — and then keeps delivering one every two or three months. That is the opposite of what happens at $5,000, where the first kill does not land until month 4 and there is nothing to celebrate for a third of the year. The behavioural argument for snowball is a weak argument at small balances and a strong one here. It still costs $731.91. Whether that is worth paying for momentum is a judgement call, not a calculation.
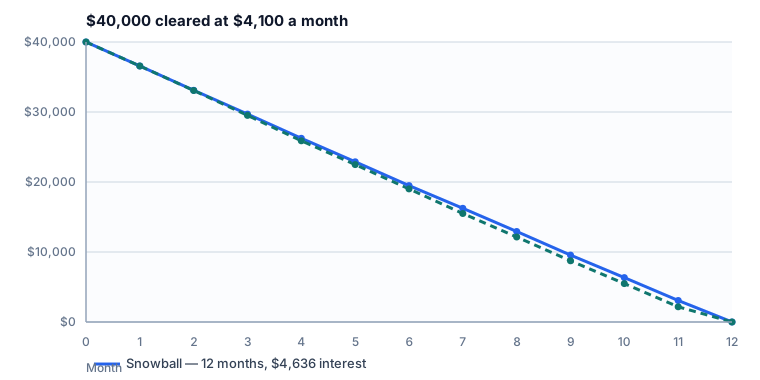
Where each card dies, month by month
The two schedules overlap only at the very start and the very end. After that they are on different cards the entire year.
| Month | Snowball | Avalanche |
|---|---|---|
| 2 | Card E cleared ($4,500, 15%) | — |
| 4 | Card D cleared ($6,500, 17%) | Card A cleared ($12,000, 24%) |
| 6 | Card C cleared ($8,000, 19%) | — |
| 7 | — | Card B cleared ($9,000, 21%) |
| 9 | Card B cleared ($9,000, 21%) | Card C cleared ($8,000, 19%) |
| 11 | — | Card D cleared ($6,500, 17%) |
| 12 | Card A cleared ($12,000, 24%) — debt-free | Card E cleared ($4,500, 15%) — debt-free |
Notice what avalanche leaves for last: the $4,500 card at 15%, the cheapest thing on the list. Leaving the cheapest balance open is the least expensive thing you can leave open. Snowball does the reverse and leaves the 24% card running all year — which is precisely what the $731.91 buys, and precisely what the month-2 kill is paid for with.
What if you can't free up $3,100 a month?
Then the one-year goal is not available and the honest move is to pick a date you can actually hit. The curve below is the whole trade-off: every $500 a month you add takes months off the back end, and the first few hundred dollars above minimums are worth far more than the last few hundred.
| Total monthly | Months (snowball) | Months (avalanche) | Interest (snowball) | Interest (avalanche) |
|---|---|---|---|---|
| $1,000 (minimums) | 82 | 80 | $28,678.10 | $28,535.63 |
| $1,500 | 50 | 44 | $17,509.34 | $13,762.20 |
| $2,000 | 32 | 30 | $11,393.06 | $9,205.91 |
| $2,500 | 23 | 22 | $8,432.80 | $6,881.56 |
| $3,000 | 18 | 18 | $6,669.57 | $5,544.05 |
| $3,500 | 15 | 15 | $5,540.91 | $4,643.65 |
| $3,900 | 13 | 13 | $4,911.45 | $4,133.47 |
| $4,000 | 13 | 13 | $4,783.57 | $4,016.20 |
| $4,100 | 12 | 12 | $4,635.85 | $3,903.94 |
| $4,300 | 12 | 11 | $4,395.97 | $3,690.53 |
| $4,600 | 11 | 11 | $4,085.40 | $3,440.38 |
Three things to read off it. First, the one-year line is not the same for both methods: avalanche reaches 12 months at $4,023, snowball needs $4,081 — a $58 gap that is worth checking before you fix your monthly number. Second, the steps are not linear. Going from $1,000 to $1,500 saves 32 months; going from $4,000 to $4,600 saves 2. Third, at $4,300 avalanche crosses the line a month earlier than snowball, so if you are aiming at a round number slightly above the minimum required, the two methods stop finishing together.
Why the method is worth more at $1,200 than at $4,100
This is the counter-intuitive result, and it is the most useful thing on the page. The gap between the two methods is not biggest at the payment that gets you finished in a year. It is biggest in the middle — above minimums, nowhere near done.
| Monthly payment | Snowball | Avalanche | Months apart | Interest gap |
|---|---|---|---|---|
| $1,000 (minimums) | 82 mo | 80 mo | 2 | $142.47 |
| $1,200 | 71 mo | 57 mo | 14 | $4,880.60 |
| $2,500 | 23 mo | 22 mo | 1 | $1,551.24 |
| $4,100 | 12 mo | 12 mo | 0 | $731.91 |
At $1,200 a month — $200 above the minimums, nowhere close to finishing — the two methods are 14 months and $4,880.60 apart. That is 6.7 times the gap at $4,100. The reason is that a small extra payment has to be aimed somewhere, and the choice of where to aim it compounds for years. A large extra payment finishes the job so fast that the aim barely matters.
The practical rule that falls out of this: if you can finish in a year, method is a minor detail. If you are stuck in the middle, paying something above minimums but not enough to finish soon, the method is the one lever you control without earning a single extra dollar — and at $40,000 it is worth nearly $5,000.
How to actually free up $3,100 extra each month
Let's be straight about the size of this. $3,100 a month is $37,200 across the year. At $25 an hour after tax that is about 1,488 hours — roughly 28.6 extra hours a week for 52 weeks. At $30 an hour it is 1,240 hours, or 23.8 a week. At $5,000 the same exercise was 4.2 hours a week; at $40,000 it is a second income or a structural change, not a weekend shift. That is why most people who clear this in a year do it by changing something big rather than by trimming.
- Sell the second car or the big-ticket item. A $9,000 sale covers 24% of the entire year's requirement in one move, and it lands in month one, when a lump sum does the most damage to the interest curve. At this size, one large asset sale is the single biggest lever most households have.
- Make the extra payment structural, not voluntary. Set the $3,100 to transfer automatically on payday. A payment this large does not survive being decided 12 times; it survives being automated once.
- Pause retirement contributions above the match. Redirecting $500 a month for one year frees $6,000 — 16% of what the year needs — at the cost of one year of above-match contributions. Keep everything up to the employer match; that part is free money and stopping it is a real loss.
- Attack the biggest non-card payment. Cutting a $650 car payment to $300 frees $350 a month with no change to your cards at all. One refinanced loan can cover more of the requirement than any spending cut.
- 0% balance transfer — the maths works, the logistics usually don't. A 3% to 5% fee on $40,000 is $1,200 to $2,000, against $4,635.85 of interest on the snowball plan, so on paper it wins. In practice very few single offers cover $40,000, so it means splitting the balance across several promotional offers, each with its own fee, its own window and its own go-to rate. Anything still standing when a window closes starts accruing at the standard rate, and that is what erases the gain. Model it in the calculator before you apply.
Two cautions. First, none of this works if new charges keep landing on the cards, and at $40,000 the tolerance is thinner than the size of the payment suggests: adding just $1,000 to the largest card turns the 12-month snowball plan into a 13-month one, while avalanche still finishes inside the year. Second, if your APRs run higher than the 15-24% range used here, every month figure above gets longer and every interest figure gets bigger. Rerun it with your real numbers rather than borrowing these.
Run your own numbers
Everything on this page came out of this site's API, so you can reproduce it or change it. The endpoint takes your cards and the extra you can pay:
POST https://debtsnowballtool.com/api/payoff
{
  "debts": [
    {"name":"Card A","balance":12000,"apr":24,"minPayment":300},
    {"name":"Card B","balance":9000,"apr":21,"minPayment":225},
    {"name":"Card C","balance":8000,"apr":19,"minPayment":200},
    {"name":"Card D","balance":6500,"apr":17,"minPayment":163},
    {"name":"Card E","balance":4500,"apr":15,"minPayment":112}
  ],
  "extra": 3100
}
Two things that trip people up: APR goes in as a percentage (24, not 0.24), and extra is the amount above your total minimums, not your total payment. Or just open the calculator and type your balances in — same engine, no payload.
If your balance is smaller, the same analysis at that size is in the $5K, $10K, $15K, $20K, $25K and $30K case studies, and if your balance is larger, the same analysis stretched over two years is in the $50K in 2 years case study. There is also a 36-second walkthrough of the $25K case on YouTube. Shorter answers to the most common payoff questions live in the payoff questions hub.
Frequently asked questions
Can you pay off $40,000 in debt in 12 months?
Yes. With five cards totalling $40,000 at 15% to 24% APR, paying $4,100 a month clears the balance in 12 months on both the snowball and the avalanche method. Interest comes to $3,903.94 on avalanche and $4,635.85 on snowball.
How much do I have to pay each month to clear $40,000 in a year?
$4,100 a month total on the example portfolio. That is $3,100 on top of the $1,000 in minimum payments across the five cards. Avalanche actually reaches 12 months at $4,023 and snowball at $4,081 — a $58 gap. Below that the plan stretches: $4,000 still needs 13 months and $3,500 needs 15.
What happens if I only pay the minimums on $40,000?
On the five-card example it takes 82 months, close to seven years, and costs $28,678.10 in interest on the snowball method. That is 71.7% of the original balance paid again in interest alone, and $68,678.10 in total. Avalanche does the same job in 80 months and $28,535.63. Unlike at smaller balances, the two methods are not identical here — but two months and $142 apart is still small next to $28,678.
Is it better to use the snowball or avalanche method on $40,000?
Avalanche is cheaper by $731.91 over the 12 months on this portfolio. That is real money, but it is small next to the payment size: going from minimums to $4,100 a month saves $24,042.25 and 70 months, roughly 33 times more than the method choice is worth. The method gap is widest nowhere near the finish line — at $1,200 a month it opens to $4,880.60 and 14 months.
Is a 0% balance transfer realistic on a $40,000 balance?
The fee maths works: 3% to 5% of $40,000 is $1,200 to $2,000, against $4,635.85 of interest on the snowball plan. The constraint is the credit limit. Very few single offers cover $40,000, so it usually means splitting the balance across several promotional offers, each with its own fee, its own window and its own go-to rate when the window closes. Any balance still standing when a window closes starts accruing at the standard rate, and that is what erases the gain.
Do I need to stop using the cards while paying them off?
Yes. Every number on this page assumes zero new charges. At $40,000 the tolerance is thin even though the payment is large: adding $1,000 to the largest card turns the 12-month snowball plan into a 13-month one, while avalanche still finishes inside the year. A common trick is to remove the cards from your mobile wallet and freeze the physical cards so using one takes effort.
How many extra hours a week would clearing $40,000 in a year take?
You need $3,100 a month above minimums, which is $37,200 across the year. At $25 an hour after tax that is about 1,488 hours, or roughly 28.6 extra hours a week for 52 weeks. At $30 an hour it is about 1,240 hours, or 23.8 hours a week. That is a second income rather than extra shifts.
What if I can only pay $2,500 a month instead of $4,100?
The plan becomes a two-year plan, not a failed one-year plan. At $2,500 a month the snowball method takes 23 months and costs $8,432.80 in interest; avalanche takes 22 months and costs $6,881.56. That is still 59 months and about $20,000 cheaper than paying minimums only — so a missed one-year target is a reason to reset the date, not to abandon the plan.