Numbers from this site's public API on a 5-card $70,000 portfolio at 15-25% APR. Open the calculator with your own balances and rates and the same numbers come out in real time.
The example portfolio
$70,000 is the size where the minimum payments alone cross $1,750 a month. This page uses five US credit cards — the same five-card shape as the $60K in 6 months case study, scaled up by a sixth. Card A carries $20,000 at 25% APR with a $500 minimum; Card B $15,000 at 22% with a $375 minimum; Card C $14,000 at 20% with a $350 minimum; Card D $12,000 at 17% with a $300 minimum; Card E $9,000 at 15% with a $225 minimum. Every minimum is exactly 2.5% of its balance, and the five of them add up to $1,750 a month.
The rates run from 25% down to 15%, and the largest balance carries the highest rate. Weighted by balance, the portfolio's rate is 20.70% a year: $20,000 × 25%, $15,000 × 22%, $14,000 × 20%, $12,000 × 17% and $9,000 × 15% come to $14,490.00 of annual interest on a $70,000 balance. One twelfth of that is 1.725%, which on the opening balance is $1,207.50 for the first month — $416.67 on Card A, $275.00 on Card B, $233.33 on Card C, $170.00 on Card D and $112.50 on Card E.
To clear all five in six months, the snowball method needs $12,992 a month, which is $11,242 above the minimums. Avalanche needs less — $12,833 — because it goes straight at the 25% card. Every figure on this page is for the snowball plan unless it says otherwise.
The deadline is an hours question: 104 hours a week, or none at all
Here is the part that decides whether a six-month plan is worth doing at all. Six months on this portfolio means $11,242 a month above the minimums. At $25 an hour after tax that is 449.68 hours a month — 104 hours a week. A week has 168 hours, so the six-month plan asks for about 62% of every hour the week contains.
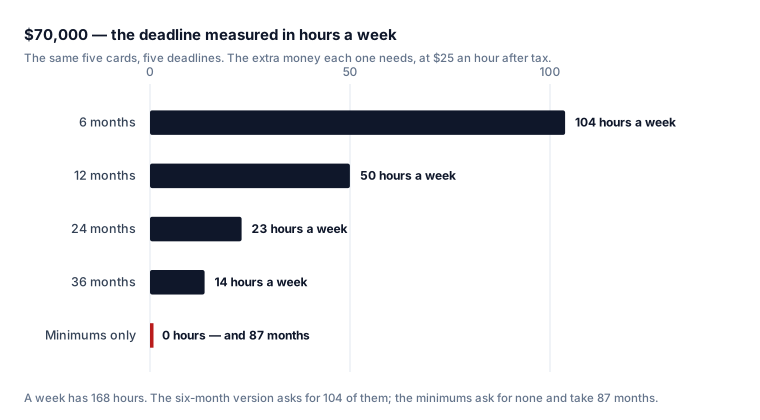
Now stretch the same $70,000 over longer deadlines and watch what happens to that number. Nothing about the debt changes; only the deadline does. The extra money needed falls, and so do the hours — until you reach the minimums, which ask for no extra hours at all and take 87 months.
| The deadline | Extra a month | Hours a week at $25 | Months to zero |
|---|---|---|---|
| 6 months | $11,242 | 104 | 6 |
| 12 months | $5,414 | 50 | 12 |
| 24 months | $2,480 | 23 | 24 |
| 36 months | $1,478 | 14 | 36 |
| Minimums only | $0 | 0 | 87 |
The ladder halves as the deadline doubles at first: 104 hours a week for six months, 50 for twelve, 23 for twenty-four, 14 for thirty-six. The hours are not free. Halving the weekly ask from 104 to 50 means the twelve-month version is charged $8,442.15 of interest against the six-month plan's $4,545.74 — $3,896.41 more for the same debt. Stretch to two years and the weekly ask is 23 hours and the interest is $16,107.08; to three years, 14 hours and $23,559.72. The minimums are the only row that asks for nothing, and they cost $54,288.30.
What the six months cost
The six months cost $4,545.74 of interest, and the total that leaves your account is $74,545.74 — the $70,000 balance plus that interest. The interest is 6.49% of the balance you started with and 6.10% of everything you send.
The payment is $12,992 in month 1 and it steps down as cards leave: $12,992, $12,767, $12,467, $12,467, $12,117 and $11,735.74 — every one of the six above $11,700. Only part of that is fixed. The $11,242 of new money never moves; the floor inside the payment does, because it is the sum of the minimums still owed on the cards that are still open — $1,750 while all five are open, $1,525 once Card E is gone, $1,225 while Cards A, B and C are still open, $875 once Card C is gone and $500 for the last month with only Card A left. The six payments add to $74,545.74, which is $3,406.26 less than six flat $12,992 payments would cost. The last payment is the only one that breaks the pattern, and it breaks it downward: $500 plus $11,242 would be $11,742, but the balance runs out first, so month 6 pays $11,735.74 — $6.26 less than the pattern.
The interest inside the payment falls faster than the payment does: $1,207.50 in month 1, then $1,054.29, $882.34, $688.73, $473.37 and $239.51 in month 6. The principal barely notices: it runs $11,784.50, $11,712.71, $11,584.66, $11,778.27, $11,643.63 and $11,496.23, a spread of just $288.27 from best month to worst. The balance goes $58,215.50, $46,502.79, $34,918.13, $23,139.86, $11,496.23 and zero. In month 1, 90.71% of what you send reaches principal; in month 6 it is 97.96%, because there is so little interest left to charge.
Snowball is not the cheapest way to spend those six months. Avalanche, run at the same $12,992 a month, is charged $3,851.45 — $694.29 less, which is 15.27% of the snowball interest bill — and it also finishes in six months. Avalanche can also clear the balance at its own lower threshold of $12,833, and at that smaller payment it costs $3,892.15; the $3,851.45 above is the equal-payment figure, so the two numbers differ by the payment they are measured at, not by the method. What the method changes is the order the cards leave in: snowball clears Card E in month 1, Card D in month 2, Card C in month 4, Card B in month 5 and Card A in month 6, while avalanche clears Card A in month 2, Card B in month 4, Card C in month 5 and finishes Cards D and E together in month 6.
The deadline itself is exact. $12,992 a month lands the payoff in six months; $12,991 takes seven and costs $4,546.02. One dollar is the whole difference between finishing on time and finishing late.
Where the $11,242 comes from
This is the part that decides whether the plan happens, so it is worth stating plainly: you need $11,242 a month above the $1,750 you already pay — 6.42 times the minimums — and over the six months the new money alone is $67,452, which is 96.36% of the balance. At $25 an hour after tax that is 104 extra hours a week. The plan pays 7.42 times the minimums and finishes the job in 6 months instead of 87 — 14.5 times faster.
Two comparisons make the size of the ask concrete. One payment of the plan, $12,992, is more than the minimums take out of your account in all six months combined — the minimums send $10,500 over that stretch, $2,492 less than the plan's first payment alone. And the whole six-month plan, at $74,545.74, is 59.98% of the $124,288.30 the minimums-only path would cost over 87 months: less than two-thirds of the money, in a fourteenth of the time.
What the minimums do in those same six months is worth reading against the plan. They move $10,500 out of your account, of which $7,110.62 is interest and only $3,389.38 reaches principal, and they leave $66,610.62 still owed — 95.16% of the original balance. The plan, over the same six months, sends $74,545.74 and ends at zero.
Reproduce these numbers
Every figure on this page comes from this site's public API. Post the five balances, their rates, their minimums and extra: 11242 to /api/payoff and you get the same months, the same $4,545.74 and the same per-card breakdown. Two things that trip people up: APR goes in as a percentage (25, not 0.25), and extra is the amount above your total minimums, not your total payment — $11,242 here, which is what turns the $1,750 in minimums into $12,992 a month. Or just open the calculator and type your balances in — same engine, no payload.
If your target is a different size or a different deadline, the same analysis is in the $60K in 6 months, $60K in 12 months, $60K in 2 years, $50K in 6 months, $50K in 12 months, $50K in 2 years, $40K in 1 year, $40K in 6 months, $30K in 6 months, $20K in 6 months, $15K in 6 months, $10K in 6 months, $5K in 6 months, $5K in 1 year, $10K, $15K, $20K, $25K, $30K and $100K case studies, plus a 36-second walkthrough of the $25K case on YouTube. Shorter answers to the most common payoff questions live in the payoff questions hub.
Frequently asked
How much do I have to pay a month to clear $70,000 in six months?
On the five-card example here, $12,992 a month clears the $70,000 in six months on the snowball method, which is $11,242 above the $1,750 in minimums. Avalanche needs less — $12,833 — because it goes at the 25% card first.
How much interest do I pay on $70,000 over six months?
The snowball plan is charged $4,545.74 and the total that leaves your account is $74,545.74 — the $70,000 balance plus that interest. The interest is 6.49% of the balance you started with and 6.10% of everything you send. Run at the same $12,992 a month, avalanche is charged $3,851.45, which is $694.29 less — 15.27% of the snowball interest bill.
How many hours a week does a six-month $70,000 payoff take?
104 hours a week. The plan needs $11,242 a month above the $1,750 minimums, and at $25 an hour after tax that is 449.68 hours a month, or 103.77 a week — about 62% of all the hours a week has. The same $70,000 on a twelve-month deadline needs $5,414 a month, which is 50 hours a week; the twenty-four-month deadline needs $2,480, or 23 hours; the thirty-six-month deadline needs $1,478, or 14 hours. The minimums ask for no extra hours at all and take 87 months.
Why is the payment $12,992 in month 1 and less later on?
Because only part of it is fixed. The $11,242 of new money never moves, but the floor inside the payment does: it is the sum of the minimums still owed on the cards that are still open, so it is $1,750 while all five are open, $1,525 once Card E is gone, $1,225 while Cards A, B and C are still open, $875 once Card C is gone and $500 for the last month with only Card A left. That turns into payments of $12,992, $12,767, $12,467, $12,467, $12,117 and $11,735.74, which add to $74,545.74 — $3,406.26 below the $77,952 that six flat $12,992 payments would total. The last payment is the only one that breaks the pattern, and it breaks it downward by $6.26, because the balance runs out before the payment does.
Does snowball versus avalanche matter on $70,000 over six months?
It is worth $694.29, which is 15.27% of the snowball interest bill. Both figures are for the same $12,992 a month: snowball takes 6 months and pays $4,545.74, avalanche takes 6 months and pays $3,851.45. Avalanche can also clear the balance at its own lower threshold of $12,833, and at that smaller payment it costs $3,892.15 — a different payment, not a different answer. The payoff orders differ: snowball clears Card E in month 1, Card D in month 2, Card C in month 4, Card B in month 5 and Card A in month 6, while avalanche clears Card A in month 2, Card B in month 4, Card C in month 5 and finishes Cards D and E together in month 6.
What if I only pay the minimums on $70,000?
The $1,750 in minimums clears the balance in 87 months — more than seven years — and costs $54,288.30 in interest, a total bill of $124,288.30. That is a saving of $49,742.56 against the six-month plan's $4,545.74. The same-term comparison is the sharper one: six months of the minimums move $10,500 out of your account, of which $7,110.62 is interest and only $3,389.38 reaches principal, and leave $66,610.62 still owed — while one payment of the plan is $12,992.
What is the blended interest rate on this portfolio?
20.70% a year, weighted by balance: $20,000 at 25%, $15,000 at 22%, $14,000 at 20%, $12,000 at 17% and $9,000 at 15% work out to $14,490.00 of annual interest on $70,000. One twelfth of that is 1.725%, which is $1,207.50 on the opening balance — and $1,207.50 divided by $70,000 is exactly 20.70% divided by twelve. By month 6, under the plan, the monthly interest is down to $239.51.
What does the same $70,000 cost on a longer deadline?
The extra money falls as the deadline stretches. Six months needs $11,242 a month above the minimums — 104 hours a week at $25 — and costs $4,545.74 in interest. Twelve months needs $5,414 a month, 50 hours a week, and costs $8,442.15. Twenty-four months needs $2,480 a month, 23 hours a week, and costs $16,107.08. Thirty-six months needs $1,478 a month, 14 hours a week, and costs $23,559.72. Paying the minimums needs nothing extra and costs $54,288.30, over 87 months.