Numbers from this site's public API on a 3-card $5,000 portfolio at 18-26% APR. Open the calculator with your own balances and rates and the same numbers come out in real time.
The example portfolio
$5,000 is the size where the minimum payments alone come to $150 a month. This page uses three US credit cards — the same three-card shape and the same 26 / 21 / 18 APR set as the $5K in 1 year and $5K in 6 months case studies. Card A carries $2,000 at 26% APR with a $60 minimum; Card B $1,750 at 21% with a $50 minimum; Card C $1,250 at 18% with a $40 minimum. The three minimums add up to $150 a month. Card A pays 3.000% of its balance and Card B 2.857%; Card C pays 3.200%, so the smallest card is the one paying itself down hardest and the middle card the least.
Weighted by balance, the portfolio's rate is 22.25% a year: $2,000 × 26%, $1,750 × 21% and $1,250 × 18% come to $1,112.50 of annual interest on a $5,000 balance. One twelfth of that is 1.85417%, which on the opening balance is $92.71 for the first month — $43.33 on Card A, $30.63 on Card B and $18.75 on Card C, $92.71 in all.
To clear all three in twenty-four months, the snowball method needs $304 a month, which is $154 above the minimums. Avalanche needs less — $291 — because it goes straight at the 26% card. Every figure on this page is for the snowball plan unless it says otherwise.
The line: what two years of principal costs
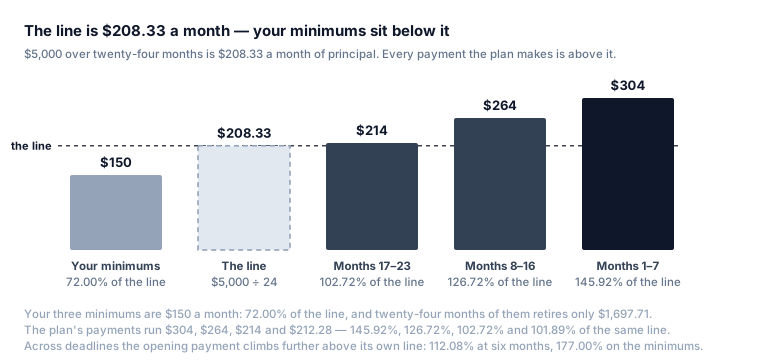
Before any interest is charged there is one number that decides this page. $5,000 spread over twenty-four months is $208.33 a month. Call it the line — the payment that retires the balance and nothing else. Every deadline has its own line, and the line is the only part of this problem that does not depend on a rate.
Your three minimums are $150 a month, which is 72.00% of the line. Even with no interest charged at all, $150 for twenty-four months retires $3,600 and leaves $1,400 of the balance standing. With the interest charged the way it actually is, twenty-four months of minimums retires $1,697.71 and leaves $3,302.29 — 66.05% of what you started with. That is the whole gap in one pair of numbers: the minimums are close to the line on paper and nowhere near it in practice, because the interest is taken before the principal is. The split of a single payment shows the same thing at the level of one card: on $5,000 at 24% with a $125 minimum, $25 of the first payment is principal.
The two-year plan is $304 a month, which is 145.92% of the line — 45.92% above it. The plan's payments step down as each card closes, and measured against the same fixed $208.33 they are 145.92%, 126.72%, 102.72% and 101.89%. So the plan opens 45.92% above the line and its final payment ends 1.89% above it, and its average payment of $258.93 is 124.29% of it.
| The stretch | The payment | The line | Over the line | Share of the bill |
|---|---|---|---|---|
| Months 1–7 | $304 | $208.33 | 145.92% | 47.53% |
| Months 8–16 | $264 | $208.33 | 126.72% | 39.68% |
| Months 17–23 | $214 | $208.33 | 102.72% | 12.42% |
| Month 24 | $212.28 | $208.33 | 101.89% | 0.37% |
Every deadline has a line, and the further out the deadline the further above its own line the payment sits. A six-month run needs $934 a month against a $833.33 line — 112.08%. A twelve-month run needs $514 against $416.67 — 123.36% (the $5K in 1 year page rounds that payment up to $515, which is charged $634.84). Twenty-four months is 145.92% of its line, thirty-six months 166.32%, and the minimums-only run 177.00% of the $84.75 line its own fifty-nine months draw. The smaller the payment, the larger the share of it that is not principal.
What the plan does over the twenty-four months
The payments step down as each card closes: $304 in months 1 to 7, $264 in months 8 to 16, $214 in months 17 to 23, and $212.28 in month 24. Each drop is exactly the minimum of the card that just closed — $40 for Card C, $50 for Card B — and the third drop, Card A's $60, never arrives: the plan ends at $212.28 instead of $214.
Card C is the first target. It is paid $194 a month — the $154 of new money plus its own $40 minimum — and it is gone in month 7. Card B takes the money from month 8 at $204 a month and finishes in month 16 on a final payment of $73.71. Card A pays its own $60 minimum for the first fifteen months, picks up $190.29 in month 16 when Card B closes, and then takes every payment from month 17 on.
Card by card the plan charges Card A $800.57, Card B $339.07 and Card C $74.65 — 65.93%, 27.92% and 6.15% of the bill, against balance shares of 40%, 35% and 25%. The monthly charge falls from $92.71 in month 1 to $4.50 in month 24, 20.60 times less, and by the last payment 97.88% of the $212.28 reaches principal against 30.50% of the first one. Of the $1,214.28 bill, 47.53% is charged in the first seven months and 0.37% in the last one.
Avalanche is cheaper and faster here. At the same $304 a month it is charged $1,006.23 — $208.05 less, so the snowball bill is 1.207 times the avalanche bill — and it lands in twenty-three months, one short of the plan. Avalanche can clear the balance at its own lower threshold of $291. The deadline itself is exact: $304 a month lands the payoff in twenty-four months, and $303 adds a twenty-fifth and takes the interest to $1,221.16.
The first twelve months send $3,448.00 and the last twelve $2,766.28 — 19.77% less — and they retire $2,565.68 against $2,434.32, so the balance crosses the halfway mark in month 12. Paying a flat $304 for all twenty-four months would cost $7,296; the plan actually sends $6,214.28, $1,081.72 less, because the floor underneath it keeps falling.
The same twenty-four months on the minimums
Leave the plan and pay the $150 instead, and the same twenty-four months go very differently. You send $3,600 and are charged $1,902.29 of interest — 52.84% of everything you send — so only $1,697.71 reaches the balance and you still owe $3,302.29, 66.05% of what you started with. The balance path is $4,640.59 at month 6, $4,241.00 at month 12, $3,796.61 at month 18 and $3,302.29 at month 24.
Not one of the three cards is cleared in those twenty-four months. Card C is the first to go, in month 43; Card B follows in month 55 and Card A in month 59. The whole minimums-only run is fifty-nine months and $3,007.87 of interest, a total bill of $8,007.87 — 60.16% of the balance you started with. Card by card the minimums charge Card A $1,580.80, Card B $977.65 and Card C $449.42. Avalanche on the same $150 takes the same fifty-nine months and is charged $3,006.48, so on this portfolio the two methods are $1.39 apart when the payment is only the minimums.
The minimums are not a flat $150 for fifty-nine months either. Each card's minimum dies with the card, so the run is $150 for the first 43 months, $110 for the next 12, and $60 at the end — which is why fifty-nine months of minimums sends $8,007.87 rather than the $8,850 that fifty-nine flat payments of $150 would come to.
Where the $154 comes from
This is the part that decides whether the plan happens, so it is worth stating plainly: you need $154 a month above the $150 you already pay — 1.027 times the minimums — and over the twenty-four months the new money is $3,696, which is 73.92% of the balance. The plan pays 2.027 times the minimums and finishes the job in 24 months instead of 59 — 2.458 times faster. Measured against the line, the $154 is 73.92% of the $208.33 the principal alone needs: the new money is what closes the distance between your minimums and the line, and the interest is what the line does not cover.
Two comparisons make the size of the ask concrete. Month 1 of the minimums is charged the same $92.71 the plan is, but of that $150 only $57.29 reaches principal — 38.19%. And the whole two years of interest is 8.095 of the $150 minimum payments, while the same two years of the minimums, at $3,600, is charged $1,902.29 — more than the plan's entire bill.
The plan's $6,214.28 is 77.60% of the $8,007.87 the minimums-only path costs, so you spend about three quarters of the money and save $1,793.59.
Reproduce these numbers
Every figure on this page comes from this site's public API. Post the three balances, their rates, their minimums and extra: 154 to /api/payoff and you get the same months, the same $1,214.28 and the same per-card breakdown — including the remaining on each month of the timeline, once with extra: 154 and once with extra: 0. Two things that trip people up: APR goes in as a percentage (26, not 0.26), and extra is the amount above your total minimums, not your total payment — $154 here, which is what turns the $150 in minimums into $304 a month. Or just open the calculator and type your balances in — same engine, no payload.
If your target is a different size or a different deadline, the same analysis is in the $5K in 1 year, $5K in 6 months, $10K in 2 years, $10K in 1 year, $10K in 6 months, $15K in 2 years, $15K in 1 year, $15K in 6 months, $20K in 2 years, $20K in 1 year, $20K in 6 months, $25K in 2 years, $25K in 1 year, $30K in 2 years, $30K in 1 year, $30K in 6 months, $40K in 2 years, $40K in 1 year, $40K in 6 months, $80K in 2 years, $80K in 12 months, $80K in 6 months, $70K in 2 years, $70K in 12 months, $70K in 6 months, $60K in 2 years, $60K in 12 months, $60K in 6 months, $50K in 2 years, $50K in 12 months, $50K in 6 months and $100K case studies, plus a 36-second walkthrough of the $25K case on YouTube. Shorter answers to the most common payoff questions live in the payoff questions hub.
Frequently asked
How much do I have to pay a month to clear $5,000 in two years?
On the three-card example here, $304 a month clears the $5,000 in twenty-four months on the snowball method, which is $154 above the $150 in minimums. Avalanche needs less — $291 — because it goes at the 26% card first.
What is the principal line on $5,000 over two years?
$208.33 a month. That is $5,000 divided by twenty-four, with no interest in it at all — the payment that retires the balance and nothing else. Your three minimums add up to $150 a month, which is 72.00% of the line, and the two-year plan is $304 a month, which is 145.92% of it.
Do my minimums reach the line?
No. $150 a month is 72.00% of the $208.33 line, and with interest charged the way it actually is, twenty-four months of minimums retires $1,697.71 of the $5,000 and leaves $3,302.29 — 66.05% of the balance you started with. The minimums-only route clears all three cards in 59 months and is charged $3,007.87 of interest, a total bill of $8,007.87.
How much interest does $5,000 cost over two years?
The snowball plan is charged $1,214.28 and the total that leaves your account is $6,214.28 — the $5,000 balance plus that interest. The interest is 24.29% of the balance you started with and 19.54% of everything you send, and it is 8.095 of the $150 minimum payments. Run at the same $304 a month, avalanche finishes in twenty-three months and is charged $1,006.23, which is $208.05 less.
Why does the plan's payment step down?
Because each drop is exactly the minimum of the card that just closed. The plan pays $304 in months 1 to 7 while all three cards are open, $264 in months 8 to 16 after Card C is gone, and $214 in months 17 to 23 after Card B is gone. Measured against the same $208.33 line, that is 145.92%, 126.72% and 102.72% — the plan opens 45.92% above the line and its final payment ends 1.89% above it.
Does it matter which card I pay off first on a two-year plan?
It is worth $208.05 at the same $304 a month, and one month of time: snowball lands in twenty-four months and avalanche in twenty-three. Snowball clears Card C in month 7, Card B in month 16 and Card A in month 24; avalanche clears Card A in month 11, Card B in month 19 and Card C in month 23.
What if I only pay the minimums on $5,000?
The $150 in minimums clears the balance in 59 months — nearly five years — and costs $3,007.87 in interest, a total bill of $8,007.87. The twenty-four-month plan is charged $1,214.28, a saving of $1,793.59. The plan also finishes 2.458 times faster: 24 months against 59. Not one of the three cards is cleared inside the first twenty-four months of minimums — Card C is the first to go, in month 43. Avalanche on the minimums takes the same 59 months and costs $3,006.48 — just $1.39 less.
How long does it take to pay off $5,000 in 2 years?
Two years, by definition — but only if you send $304 a month, which is 2.027 times the $150 in minimums. The deadline is exact: $304 lands the payoff in twenty-four months and $303 adds a twenty-fifth and takes the interest to $1,221.16. Avalanche's own deadline sits lower, at $291, and $290 pushes it to twenty-five months. The minimums alone take 59 months on the same portfolio and cost $3,007.87 in interest.