Numbers from this site's public API on a 4-card $15,000 portfolio at 17-24% APR. The per-card figures come from the API's own perDebt breakdown. Open the calculator with your own balances and rates and the same numbers come out in real time.
The example portfolio
"Can I pay off $15,000 in six months" depends on how the balance is split and what each piece costs you. This page uses four US credit cards totalling $15,000. Card A carries $6,000 at 24% APR with a $150 minimum; Card B carries $4,000 at 21% with a $100 minimum; Card C carries $3,000 at 19% with an $80 minimum; Card D carries $2,000 at 17% with a $70 minimum. The four minimums add up to $400 a month. The rates are stacked so the largest balance is also the most expensive card — the shape that makes the order question matter, and a shape most real $15,000 stacks take: one card near its limit, three in the middle.
To clear all four in six months, the snowball method needs $2,795 a month, which is $2,395 above the minimums. Avalanche needs less — $2,739 — because it goes straight at the 24% card. Both land in month 6. Every figure on this page is for the snowball plan unless it says otherwise.
Where the interest actually comes from
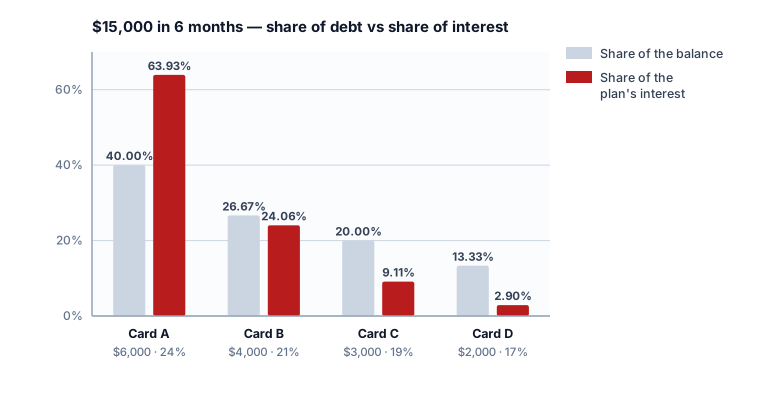
Six months, $2,795 in month 1, on the snowball method. The interesting column is not the balance — it is how much of the $977.62 interest bill each card is responsible for:
| Card | Balance | APR | Interest | Share of interest | Per $1,000 |
|---|---|---|---|---|---|
| Card A mo 6 | $6,000 | 24% | $624.99 | 63.93% | $104.17 |
| Card B mo 4 | $4,000 | 21% | $235.21 | 24.06% | $58.80 |
| Card C mo 3 | $3,000 | 19% | $89.09 | 9.11% | $29.70 |
| Card D mo 1 | $2,000 | 17% | $28.33 | 2.90% | $14.17 |
| All four | $15,000 | 17-24% | $977.62 | 100.00% | $65.17 |
Read the two percentages in the subhead together, because they are measured against two different things. The 63.93% is $624.99 divided by the plan's total interest of $977.62 — how much of the interest bill that one card is responsible for. The 40.00% is $6,000 divided by the original balance of $15,000 — how much of the debt that card is. Neither share is measured against the monthly payment, and neither is measured against the other; one is a share of the cost, the other is a share of the principal, and on this portfolio they are twenty-four points apart.
The last column is the cleanest way to see it. Every $1,000 sitting on the 24% card costs $104.17 across these six months. The same $1,000 on the 17% card costs $14.17 — a factor of 7.35. The four cards are not four equal slices of the same debt; they are four different prices for borrowing, and the plan's total is set by how much sits at the expensive end.
Why one card costs $104.17 per $1,000 and another costs $14.17
Three things multiply to produce that gap, and all three point the same way on this portfolio. The first is the rate: 24% against 17%, which on its own is a factor of 1.41. The second is the balance: the 24% card is three times the size of the 17% card, so there are three times as many dollars accruing at the higher rate. The third, and the one people miss, is time — the 24% card is the last one cleared, in month 6, so it accrues interest for all six months, while the $2,000 card is cleared in month 1 and stops accruing almost immediately.
Multiply the three together and $1,000 on the expensive card is not 1.4 times as costly as $1,000 on the cheap one — it is 7.35 times as costly. That is why a payoff plan is not really about paying off the debt; it is about deciding which dollars stop accruing first, and how soon.
It also explains why the snowball order produces this particular split. Snowball goes smallest first, so the two cheapest, smallest cards are cleared in months 1 and 3 and the 24% card sits there for the whole plan. The order is not wrong — it produces the early wins that keep a plan alive — but the cost of that order is concentrated in exactly one place, and this is the table that shows where.
Why the payment is $2,795 in month 1 and less later
Take $2,795 and multiply by six and you get $16,770. The six months do not cost that — they cost $15,977.62 — because a card's minimum payment is part of your monthly total only while that card still has a balance. The month a card is cleared, its minimum drops out of the budget, and the money leaving your account steps down.
On this portfolio it steps down three times. Card D, the $2,000 balance, is cleared in month 1, taking $70 off from month 2. Card C, $3,000, is cleared in month 3, taking $80 off from month 4. Card B, $4,000, is cleared in month 4, taking $100 off from month 5. So the plan is really $2,795 once, $2,725 twice, $2,645 once, $2,545 once, and then $2,542.62 in month 6 to finish the last card — $15,977.62 in total, exactly $792.38 less than the flat multiplication.
The same card under avalanche: $213.53 instead of $624.99
The per-card breakdown makes the method question unusually concrete. At the same $2,795 a month, avalanche clears Card A first, in month 3, and that single change takes the 24% card's interest from $624.99 down to $213.53 — a difference of $411.46 on one card. Nothing else about the debt changes; the balance, the rates and the six months are identical.
The total gap is smaller than that, $112.37 ($977.62 on snowball against $865.25 on avalanche), because the cards avalanche leaves for last — the cheap ones — cost slightly more than they did under snowball. That is the trade: avalanche moves the expensive card to the front and pays a little more on the cheap cards to do it, and on this portfolio it nets out $112.37 ahead. The per-card view shows where the money actually moves, which the totals alone hide.
Where the extra $2,395 a month comes from
The plan needs $2,395 above the $400 in minimums, which is $14,370 over six months — 95.80% of the balance. At $25 an hour after tax that is about 22.1 extra hours a week; at $30 an hour it is about 18.4.
- Make it a transfer, not a decision. Six months is short enough to automate. Set the payment for payday and let it run; re-deciding it every month is how these plans die.
- Kill the biggest non-card payment. A $500 car payment refinanced to $320 frees $180 a month — nearly a tenth of the requirement, from one phone call.
- Pause retirement contributions above the match. Redirecting $450 a month for six months frees $2,700, more than a quarter of the $10,294.32 the plan saves in interest. Keep contributing up to the employer match; that part is free money and stopping it is a real loss.
- Attack the 24% card from both ends. Card A is the single most expensive thing on this list at $104.17 per $1,000, so a rate cut there is worth more than anywhere else — and if you are on the snowball plan it is also the last card you touch, which is exactly why it is worth a phone call.
- Watch the 0% balance-transfer arithmetic. A 3% to 5% fee on $15,000 is $450 to $750 against $977.62 of interest on this plan, so one offer can cover most of the cost — but only if the whole $15,000 moves and the balance is cleared before the promotional window closes. Anything still standing when it closes starts accruing at the standard rate. Model it in the calculator before you apply.
Run your own numbers
Everything on this page came out of this site's API, so you can reproduce it or change it. The endpoint takes your cards and the extra you can pay, and now returns a per-card breakdown as well:
POST https://debtsnowballtool.com/api/payoff
{
  "debts": [
    {"name":"Card A","balance":6000,"apr":24,"minPayment":150},
    {"name":"Card B","balance":4000,"apr":21,"minPayment":100},
    {"name":"Card C","balance":3000,"apr":19,"minPayment":80},
    {"name":"Card D","balance":2000,"apr":17,"minPayment":70}
  ],
  "extra": 2395
}
Two things that trip people up: APR goes in as a percentage (24, not 0.24), and extra is the amount above your total minimums, not your total payment — $2,395 here, which is what turns the $400 in minimums into $2,795 a month. The response's perDebt array is where the table above comes from: each card's interest, principal and clearedMonth, and those interest figures sum to the plan's totalInterest. Or just open the calculator and type your balances in — same engine, no payload.
If your target is a different size or a different deadline, the same analysis is in the $5K, $10K, $10K in 6 months, $15K, $20K, $25K, $30K, $40K, $50K and $100K case studies, plus a 36-second walkthrough of the $25K case on YouTube. Shorter answers to the most common payoff questions live in the payoff questions hub.
Frequently asked questions
How much do I have to pay a month to clear $15,000 in 6 months?
On the four-card example here, $2,795 a month clears the $15,000 in six months on the snowball method, which is $2,395 above the $400 in minimums. Avalanche needs less — $2,739 — because it goes at the highest-rate card first.
How much of a six-month payoff on $15,000 is interest?
$977.62 on the snowball method and $865.25 on the avalanche, a gap of $112.37. The total that leaves your account over the six months is $15,977.62 on snowball — the $15,000 balance plus $977.62 of interest.
Is the interest split evenly across the cards?
No. Card A, the $6,000 balance at 24%, is 40.00% of the debt but carries $624.99 of the plan's $977.62 interest, which is 63.93%. Card D, the $2,000 balance at 17%, is 13.33% of the debt and carries $28.33, or 2.90%. The two shares use different denominators — 63.93% against the plan's total interest and 40.00% against the $15,000 balance — and neither is against the monthly payment.
Why does one card cost so much more per $1,000 than another?
Three things multiply: the 24% card carries the highest rate, the largest balance and the longest life — it is the last card cleared, in month 6 — so its dollars accrue at the highest rate for all six months. The 17% card is the smallest, the cheapest and the first one cleared, in month 1. Per $1,000 of balance that is $104.17 against $14.17, a factor of 7.35.
Why is the payment $2,795 in month 1 and less later on?
Because each card's minimum drops out of your budget the month that card is cleared. The $2,000 card goes in month 1, the $3,000 card in month 3 and the $4,000 card in month 4, removing $70, $80 and $100 from the monthly total. So the plan is really $2,795 once, $2,725 twice, $2,645 once, $2,545 once and $2,542.62 to finish — $15,977.62 in total, which is $792.38 less than multiplying the starting payment by six.
Is snowball or avalanche better on a six-month plan?
At $2,795 a month avalanche pays $865.25 in interest and snowball pays $977.62, so the gap is $112.37. The gap is concentrated in one card: Card A costs $624.99 under snowball, because it is cleared last, and $213.53 under avalanche, because it is cleared first — $411.46 on a single card, offset by the other cards costing slightly more.
What if I only pay the minimums on $15,000?
The $400 in minimums clears the balance in 81 months — nearly seven years — and costs $11,271.94 in interest, a total bill of $26,271.94, which is 75.1% of the original balance. The six-month plan's $977.62 is 8.67% of that, a saving of $10,294.32.
Do I need to stop using the cards while paying off $15,000 in six months?
Yes. Every number here assumes zero new charges. On a six-month plan the margin is thin: the whole plan spends $977.62 on interest, and a single new balance on the 24% card is charged at the highest rate on the list for the whole time it is carried. A common approach is to remove the cards from your mobile wallet and freeze the physical ones so using one takes deliberate effort.