Numbers from this site's public API on a 5-card $70,000 portfolio at 15-25% APR. Open the calculator with your own balances and rates and the same numbers come out in real time.
The example portfolio
$70,000 is the size where the minimum payments alone cross $1,750 a month. This page uses five US credit cards — the same five-card shape as the $70K in 6 months case study, on a longer clock. Card A carries $20,000 at 25% APR with a $500 minimum; Card B $15,000 at 22% with a $375 minimum; Card C $14,000 at 20% with a $350 minimum; Card D $12,000 at 17% with a $300 minimum; Card E $9,000 at 15% with a $225 minimum. Every minimum is exactly 2.5% of its balance, and the five of them add up to $1,750 a month.
The rates run from 25% down to 15%, and the largest balance carries the highest rate. Weighted by balance, the portfolio's rate is 20.70% a year: $20,000 × 25%, $15,000 × 22%, $14,000 × 20%, $12,000 × 17% and $9,000 × 15% come to $14,490.00 of annual interest on a $70,000 balance. One twelfth of that is 1.725%, which on the opening balance is $1,207.50 for the first month — $416.67 on Card A, $275.00 on Card B, $233.33 on Card C, $170.00 on Card D and $112.50 on Card E.
To clear all five in twelve months, the snowball method needs $7,164 a month, which is $5,414 above the minimums. Avalanche needs less — $7,029 — because it goes straight at the 25% card. Every figure on this page is for the snowball plan unless it says otherwise.
The year's interest is not twelve equal slices
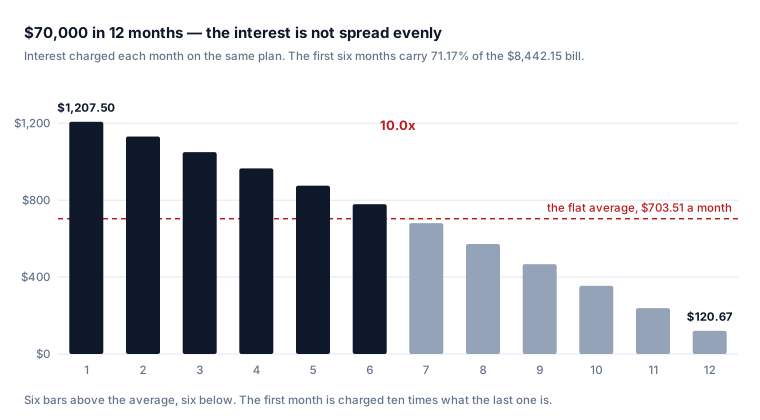
A twelve-month plan sounds like twelve of the same thing. The interest is not. Month 1 is charged $1,207.50 and month 12 is charged $120.67 — the first month costs 10.0 times what the last one does, on the same plan, for the same debt.
The reason is that interest is charged on whatever balance is still standing, and this plan takes that balance down quickly. Month 1 opens with the whole $70,000 outstanding. Month 12 opens with $5,792.48 — one card, four months from the end. Split the year in half and the shape is stark: the first six months are charged $6,008.10, which is 71.17% of the year's $8,442.15, while the last six are charged $2,434.05, or 28.83%. Over those same halves the plan retires $35,475.90 and $34,524.10 of the balance — 50.68% and 49.32%. So the principal is close to a coin flip and the interest is not: seven tenths of the interest is charged in the half of the year that retires half the balance.
| The slice | Interest charged | Share of the year | Balance retired |
|---|---|---|---|
| Month 1 | $1,207.50 | 14.30% | $5,956.50 |
| Month 12 | $120.67 | 1.43% | $5,792.48 |
| First six months | $6,008.10 | 71.17% | $35,475.90 |
| Last six months | $2,434.05 | 28.83% | $34,524.10 |
| The twelve months | $8,442.15 | 100.00% | $70,000.00 |
The flat monthly average of the bill is $703.51 — $8,442.15 split twelve ways. Not one of the first six months is charged below that line, and not one of the last six is charged above it. That is the whole shape of a twelve-month payoff in one sentence: you pay for the balance you are still carrying, so the expensive months are the early ones.
What the twelve months cost
The twelve months cost $8,442.15 of interest, and the total that leaves your account is $78,442.15 — the $70,000 balance plus that interest. The interest is 12.06% of the balance you started with and 10.76% of everything you send.
The payment is $7,164 in month 1 and it steps down as cards leave: $7,164, $7,164, $6,939, $6,939, $6,639, $6,639, $6,639, $6,289, $6,289, $5,914, $5,914 and $5,913.15. Every one of the twelve is above $5,900. Only part of that is fixed. The $5,414 of new money never moves; the floor inside the payment does, because it is the sum of the minimums still owed on the cards that are still open — $1,750 while all five are open, $1,525 once Card E is gone, $1,225 while Cards A, B and C are still open, $875 once Card C is gone and $500 for the last two months with only Card A left. The twelve payments add to $78,442.15, which is $7,525.85 less than twelve flat $7,164 payments would cost, and the first payment is $1,250.85 larger than the last. The final payment is the only one that breaks the pattern, and it breaks it downward: $500 plus $5,414 would be $5,914, but the balance runs out first, so month 12 pays $5,913.15 — $0.85 less than the pattern.
In month 1, 83.14% of what you send reaches principal; in month 12 it is 97.96%, because there is so little interest left to charge. The balance goes $64,043.50, $58,010.56, $52,121.66, $46,148.02, $40,384.37, $34,524.10, $28,565.59, $22,848.74, $17,026.84, $11,467.57, $5,792.48 and zero.
Snowball is not the cheapest way to spend those twelve months. Avalanche, run at the same $7,164 a month, is charged $6,967.53 — $1,474.62 less, which is 17.47% of the snowball interest bill — and it also finishes in twelve months. Avalanche can also clear the balance at its own lower threshold of $7,029, and at that smaller payment it costs $7,118.60; the $6,967.53 above is the equal-payment figure, so the two numbers differ by the payment they are measured at, not by the method. What the method changes is the order the cards leave in: snowball clears Card E in month 2, Card D in month 4, Card C in month 7, Card B in month 9 and Card A in month 12, while avalanche clears Card A in month 4, Card B in month 7, Card C in month 9, Card D in month 11 and Card E in month 12.
The deadline itself is exact. $7,164 a month lands the payoff in twelve months; $7,163 takes thirteen and costs $8,443.72. A single dollar separates finishing on time from finishing late.
Where the $5,414 comes from
This is the part that decides whether the plan happens, so it is worth stating plainly: you need $5,414 a month above the $1,750 you already pay — 3.09 times the minimums — and over the twelve months the new money alone is $64,968, which is 92.81% of the balance. The plan pays 4.09 times the minimums and finishes the job in 12 months instead of 87 — 7.25 times faster.
Two comparisons make the size of the ask concrete. The whole twelve-month plan, at $78,442.15, is 63.11% of the $124,288.30 the minimums-only path would cost over 87 months: about three-fifths of the money, in a seventh of the time. And what the minimums do in those same twelve months is worth reading against the plan. They move $21,000 out of your account, of which $13,878.36 is interest and only $7,121.64 reaches principal, and they leave $62,878.36 still owed — 89.83% of the original balance. The plan, over the same twelve months, sends $78,442.15 and ends at zero. Month 1 of the minimums is charged the same $1,207.50 the plan is, but of that $1,750 only $542.50 reaches principal — 31.00%, against 83.14% for the plan's first payment.
Reproduce these numbers
Every figure on this page comes from this site's public API. Post the five balances, their rates, their minimums and extra: 5414 to /api/payoff and you get the same months, the same $8,442.15 and the same per-card breakdown. Two things that trip people up: APR goes in as a percentage (25, not 0.25), and extra is the amount above your total minimums, not your total payment — $5,414 here, which is what turns the $1,750 in minimums into $7,164 a month. Or just open the calculator and type your balances in — same engine, no payload.
If your target is a different size or a different deadline, the same analysis is in the $70K in 6 months, $60K in 6 months, $60K in 12 months, $60K in 2 years, $50K in 6 months, $50K in 12 months, $50K in 2 years, $40K in 1 year, $40K in 6 months, $30K in 6 months, $20K in 6 months, $15K in 6 months, $10K in 6 months, $5K in 6 months, $5K in 1 year, $10K, $15K, $20K, $25K, $30K and $100K case studies, plus a 36-second walkthrough of the $25K case on YouTube. Shorter answers to the most common payoff questions live in the payoff questions hub.
Frequently asked
How much do I have to pay a month to clear $70,000 in twelve months?
On the five-card example here, $7,164 a month clears the $70,000 in twelve months on the snowball method, which is $5,414 above the $1,750 in minimums. Avalanche needs less — $7,029 — because it goes at the 25% card first.
How much interest do I pay on $70,000 over twelve months?
The snowball plan is charged $8,442.15 and the total that leaves your account is $78,442.15 — the $70,000 balance plus that interest. The interest is 12.06% of the balance you started with and 10.76% of everything you send. Run at the same $7,164 a month, avalanche is charged $6,967.53, which is $1,474.62 less — 17.47% of the snowball interest bill.
Why is month 1 charged ten times the interest of month 12?
Because interest is charged on whatever balance is still standing, and the plan takes that balance down fast. Month 1 opens with the whole $70,000 outstanding, so the charge is $1,207.50. Month 12 opens with $5,792.48 — one card, near the end — so the charge is $120.67. That is 10.0 times less, and it is why the first six months carry $6,008.10 of the $8,442.15 bill, or 71.17%, while the last six carry $2,434.05, or 28.83%. The first six months retire $35,475.90 of the balance, 50.68% of it, so the interest is front-loaded well ahead of the principal.
Why is the payment $7,164 in month 1 and less later on?
Because only part of it is fixed. The $5,414 of new money never moves, but the floor inside the payment does: it is the sum of the minimums still owed on the cards that are still open, so it is $1,750 while all five are open, $1,525 once Card E is gone, $1,225 while Cards A, B and C are still open, $875 once Card C is gone and $500 for the last two months with only Card A left. That turns into payments of $7,164, $7,164, $6,939, $6,939, $6,639, $6,639, $6,639, $6,289, $6,289, $5,914, $5,914 and $5,913.15, which add to $78,442.15 — $7,525.85 below the $85,968 that twelve flat $7,164 payments would total. The last payment is the only one that breaks the pattern, and it breaks it downward by $0.85, because the balance runs out before the payment does.
Does snowball versus avalanche matter on $70,000 over twelve months?
It is worth $1,474.62, which is 17.47% of the snowball interest bill. Both figures are for the same $7,164 a month: snowball takes 12 months and pays $8,442.15, avalanche takes 12 months and pays $6,967.53. Avalanche can also clear the balance at its own lower threshold of $7,029, and at that smaller payment it costs $7,118.60 — a different payment, not a different answer. The payoff orders differ: snowball clears Card E in month 2, Card D in month 4, Card C in month 7, Card B in month 9 and Card A in month 12, while avalanche clears Card A in month 4, Card B in month 7, Card C in month 9, Card D in month 11 and Card E in month 12.
What if I only pay the minimums on $70,000?
The $1,750 in minimums clears the balance in 87 months — more than seven years — and costs $54,288.30 in interest, a total bill of $124,288.30. The twelve-month plan is charged $8,442.15, a saving of $45,846.15. The plan also finishes 7.25 times faster: 12 months against 87. Month 1 of the minimums is charged the same $1,207.50 the plan is, but only $542.50 of that $1,750 reaches principal, against $5,956.50 of the plan's first payment.
What do twelve months of the minimums actually retire?
A whole year of minimums moves $21,000 out of your account. Of that, $13,878.36 is interest and only $7,121.64 reaches principal, so after twelve months you still owe $62,878.36 — 89.83% of the balance you started with. The plan, over the same twelve months, sends $78,442.15 and ends at zero.
What is the blended interest rate on this portfolio?
20.70% a year, weighted by balance: $20,000 at 25%, $15,000 at 22%, $14,000 at 20%, $12,000 at 17% and $9,000 at 15% work out to $14,490.00 of annual interest on $70,000. One twelfth of that is 1.725%, which is $1,207.50 on the opening balance — and $1,207.50 divided by $70,000 is exactly 20.70% divided by twelve. By month 12, under the plan, the monthly interest is down to $120.67.