Numbers from this site's public API on a 3-card $10,000 portfolio at 18-26% APR. Open the calculator with your own balances and rates and the same numbers come out in real time.
The example portfolio
"Can I pay off $10,000 in a year" is not answerable in the abstract — it depends on how the balance is split and what each piece costs you. The example below uses three US credit cards, with the rates deliberately stacked so the smallest balance is not the most expensive one. That is the shape that makes the snowball-versus-avalanche argument actually matter, and it is also the shape most real $10,000 stacks take: one card near its limit, two in the middle.
| Card | Balance | Min payment | APR |
|---|---|---|---|
| Card A | $4,000 | $120 | 26% |
| Card B | $3,500 | $100 | 21% |
| Card C | $2,500 | $80 | 18% |
| Total | $10,000 | $300 | — |
Read that table once more before the numbers below. Card C is the smallest and the cheapest. Card A is the largest and the most expensive. Snowball will go after C first because it is small. Avalanche will go after A first because it is expensive. Both will get you to zero in the same month here — and that is exactly why the method argument is worth less than people think.
What minimums-only actually costs on $10,000
This is the number that rarely gets printed next to the one-year headline. Sending $300 a month — the minimums, nothing more — clears this portfolio in 59 months on both methods, which is almost five years. Interest comes to $6,015.74 on snowball and $6,012.97 on avalanche. That means you repay the $10,000 and then pay another 60% of it again in interest.
So the honest framing of a one-year $10,000 payoff is not "I need $1,050 a month." It is "the gap between doing nothing extra and doing the one-year plan is $4,773.73 in interest and 47 months of your life." The monthly payment is just the lever.
One detail worth flagging, because it surprises people: at the minimums-only payment, the two methods land within $2.77 of each other over five years. Both take 59 months. The method argument is essentially switched off at that payment level, and it only wakes up once you start sending real extra money.
Both methods finish in 12 months at $1,050/month
At $1,050 a month the two methods land on the same month, and the payoff orders are genuinely different rather than cosmetic. Snowball kills the $2,500 card first. Avalanche goes straight at the 26% card. Both finish at month 12; avalanche costs $172.92 less.
| Method | Payoff order | Months | Total interest |
|---|---|---|---|
| Snowball | C (m4) → B (m8) → A (m12) | 12 | $1,242.01 |
| Avalanche | A (m5) → B (m9) → C (m12) | 12 | $1,069.09 |
Here is the part most method arguments skip. On this portfolio, choosing avalanche over snowball is worth $172.92. Going from minimums to $1,050 a month is worth $4,773.73. The payment size is about 28 times more powerful than the method. If you are spending your energy arguing about which order to pay cards in while your monthly payment stays flat, you are optimizing the wrong variable.
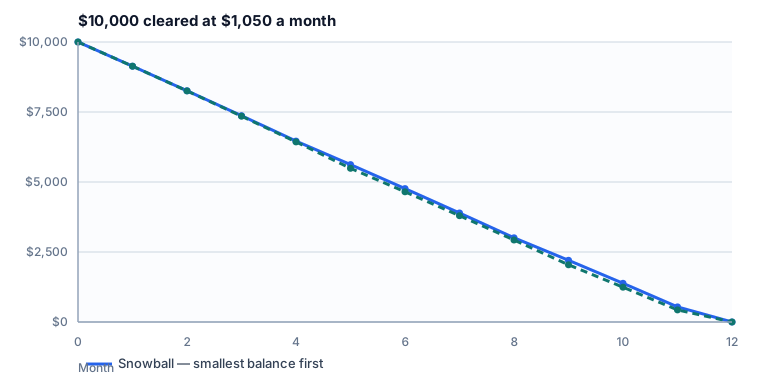
Where each card dies, month by month
The psychological case for snowball is the early win, and on this portfolio it is real: the first card is gone at month 4, one month before avalanche kills its first one. Avalanche's first card takes five months because it is the $4,000 balance. What avalanche gives you instead is a cheaper back half — its remaining balance is lower than snowball's every single month from month 2 to month 11.
| Month | Snowball | Avalanche |
|---|---|---|
| 4 | Card C cleared ($2,500, 18%) | — |
| 5 | — | Card A cleared ($4,000, 26%) |
| 8 | Card B cleared ($3,500, 21%) | — |
| 9 | — | Card B cleared ($3,500, 21%) |
| 12 | Card A cleared ($4,000, 26%) | Card C cleared ($2,500, 18%) |
Notice which card avalanche leaves for last: the $2,500 one at 18%. It is the cheapest card on the list, so leaving it open for twelve months is the least expensive card to leave open. Snowball does the opposite and leaves the 26% card open for all twelve months — which is precisely why it costs an extra $172.92.
What if you can't free up $750 a month?
Then the plan becomes a 15-month, a 20-month or a 32-month plan, and all three are still dramatically better than 59 months. The curve is steepest at the bottom: the first $100 above minimums cuts 14 months off the timeline. The last $50 before the one-year mark cuts one month.
| Total monthly | Months (snowball) | Months (avalanche) | Interest (snowball) | Interest (avalanche) |
|---|---|---|---|---|
| $300 (minimums) | 59 | 59 | $6,015.74 | $6,012.97 |
| $400 | 45 | 39 | $4,339.72 | $3,550.79 |
| $500 | 32 | 30 | $3,155.71 | $2,603.23 |
| $600 | 25 | 24 | $2,483.80 | $2,054.55 |
| $700 | 20 | 19 | $2,017.76 | $1,686.62 |
| $800 | 17 | 16 | $1,710.28 | $1,432.51 |
| $900 | 15 | 14 | $1,498.14 | $1,266.94 |
| $1,000 | 13 | 13 | $1,318.78 | $1,115.55 |
| $1,050 | 12 | 12 | $1,242.01 | $1,069.09 |
| $1,100 | 12 | 11 | $1,194.40 | $1,012.04 |
| $1,200 | 10 | 10 | $1,076.72 | $919.44 |
Note what happens at $400 a month: the methods stop agreeing. Snowball takes 45 months, avalanche takes 39 — a six-month gap worth $788.93. That is the largest method gap anywhere on this table, larger than the $172.92 gap at the one-year payment. The method matters most in the messy middle, where you are paying meaningfully more than the minimum but nowhere near enough to finish quickly. At minimums only it is worth $2.77. At $1,050 it is worth $172.92. At $400 it is worth $788.93.
How to actually free up $750 extra each month
$10,000 is the size where a one-year payoff is genuinely reachable without selling a house. $750 a month is $9,000 across the year, and at $20 an hour after tax that is about 450 hours — roughly 8.6 extra hours a week for 52 weeks. Framed that way, it is a fixed-term project with an end date, not a permanent second job. In practice people assemble it from a mix, usually from the top of this list:
- Sell something. A second car, a motorcycle, an unused instrument, a camera kit, a console and game library. One asset sale of $3,000 is a third of what the whole year needs, and it arrives as a lump you can throw at the first card in month one — which is also the month where a lump does the most damage to the interest curve.
- Twelve months of overtime or a fixed-term second income. 8 extra hours a week at $20/hour after tax is close to the full $750. The end date is what makes it survivable.
- Pause retirement contributions above the match. Redirecting $250 a month for one year costs you one year of contributions and saves roughly $4,770 in interest. The match itself is free money — keep contributing at least up to it.
- Attack the biggest non-card payment. If you have an auto loan, refinancing or downgrading it usually frees more per month than any card minimum. Cutting a $400 car payment to $250 frees $150 a month for a year with no change to your cards.
- A 0% balance transfer, only if the math clears. A 3% to 5% fee on $10,000 is $300 to $500. That is more than the entire $172.92 the method choice is worth, so the transfer has to save you more than the fee in interest to be worth doing. Model it in the calculator before you apply — do not assume the transfer wins.
Two cautions. First, none of this works if new charges keep landing on the cards; a one-year plan assumes the balance only moves in one direction. Second, if your APRs are higher than the 18-26% range used here — and store cards often run 29% or more — every month figure above gets longer and every interest figure gets bigger. Rerun it with your real numbers instead of borrowing these.
Run your own numbers
Everything on this page came out of this site's API, so you can reproduce it or change it. The endpoint takes your cards and the extra you can pay:
POST https://debtsnowballtool.com/api/payoff
{
  "debts": [
    {"name":"Card A","balance":4000,"apr":26,"minPayment":120},
    {"name":"Card B","balance":3500,"apr":21,"minPayment":100},
    {"name":"Card C","balance":2500,"apr":18,"minPayment":80}
  ],
  "extra": 750
}
Two things that trip people up: APR goes in as a percentage (26, not 0.26), and extra is the amount above your total minimums, not your total payment. Or just open the calculator and type your balances in — same engine, no payload.
If your balance is closer to $15,000 than $10,000, the same analysis at that size is in the $15K in 1 year case study. There is also a $20K version and a $30K version. And if a year is too slow, the same $10,000 on a six-month deadline is worked out in the $10K in 6 months case study. Shorter answers to the most common payoff questions live in the payoff questions hub.
Frequently asked questions
Can you pay off $10,000 in debt in 1 year?
Yes. With three cards totalling $10,000 at 18% to 26% APR, paying $1,050 a month clears the balance in 12 months on both the snowball and the avalanche method. Interest comes to $1,069.09 on avalanche and $1,242.01 on snowball.
How much do I have to pay each month to clear $10,000 in a year?
$1,050 a month total on the example portfolio. That is $750 on top of the $300 in minimum payments across the three cards. At $1,000 a month both methods land on 13 months, so the one-year line sits between $1,000 and $1,050.
What happens if I only pay the minimums on $10,000?
On the three-card example it takes 59 months, which is almost five years, and costs $6,015.74 in interest on the snowball method. That is 60% of the original balance paid again in interest alone — and at that payment level the two methods finish within $2.77 of each other.
Is it better to use the snowball or avalanche method on $10,000?
Avalanche is cheaper by $172.92 over the 12 months on this portfolio. That is real money but it is small next to the payment size: going from minimums to $1,050 a month saves $4,773.73, which is about 28 times more than the method choice is worth. The exception is the $400-a-month range, where the gap opens to $788.93.
Should I use a 0% balance transfer to pay off $10,000 faster?
Only if you can move most of the balance and clear it inside the promotional window. The transfer fee usually runs 3% to 5%, which is $300 to $500 on $10,000 — more than the entire method gap. Run both scenarios in the calculator before you apply.
Do I need to stop using the cards while paying them off?
Yes. Every number on this page assumes zero new charges. If you keep spending on the cards, the balances stop shrinking no matter how much extra you send. A common trick is to remove the cards from your mobile wallet and freeze the physical cards so using one takes effort.
How many hours of overtime would it take to clear $10,000 in a year?
You need $750 a month above minimums, which is $9,000 across the year. At $20 an hour after tax that is roughly 450 hours, or about 8.6 extra hours a week for 52 weeks. At $25 an hour it is about 360 hours, or 7 hours a week.