Numbers from this site's public API on a 4-card $90,000 portfolio at 15-24% APR. Open the calculator with your own balances and rates and the same numbers come out in real time.
The example portfolio
$90,000 is the size where the minimum payments alone come to $2,250 a month. This page uses four US credit cards — Card A carries $34,000 at 24% APR with an $850 minimum; Card B $26,000 at 19% with $650; Card C $18,000 at 22% with $450; Card D $12,000 at 15% with $300. The four minimums add up to $2,250 a month. Card A is the largest balance and the highest rate at the same time, which is the whole reason snowball and avalanche land in different places.
Weighted by balance, the portfolio's rate is 20.9556% a year: $34,000 × 24%, $26,000 × 19%, $18,000 × 22% and $12,000 × 15% work out to $18,860 of annual interest on a $90,000 balance. One twelfth of that is 1.7463, which on the opening balance is $1,572 for the first month.
To clear all four in twelve months, the snowball method needs $9,125 a month, which is $6,875 above the minimums. Avalanche needs less — $8,986 — because it goes straight at the 24% card. Every figure on this page is for the snowball plan unless it says otherwise.
One card is both the biggest and the costliest
Card A carries $34,000 at 24% APR — larger than any other card and a higher rate than any other card. Snowball ranks debts by balance, so it leaves Card A for last and clears it in month 12. Avalanche ranks by rate, so it attacks Card A first and clears it in month 5. The two methods do not just reorder the middle; they flip the most expensive card in the portfolio.
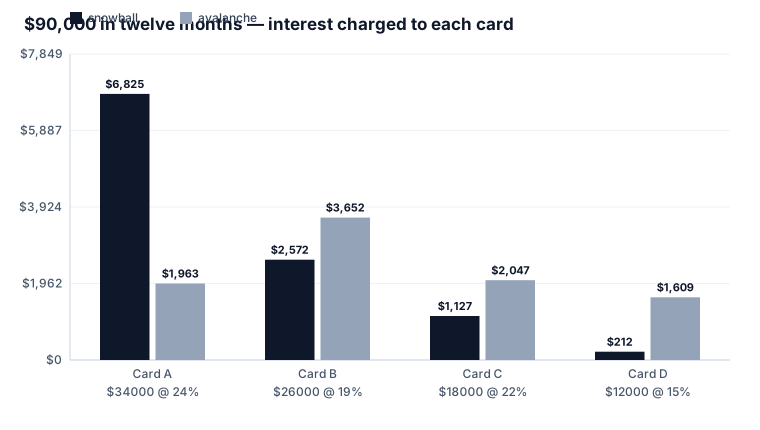
On the snowball plan Card A is charged $6,825 of interest — 63.57% of the entire $10,737 interest bill — because it sits there accruing 24% while the three smaller cards are cleared first. On avalanche the same card is charged only $1,963, because it dies in month 5 before its rate has time to work. That gap, $4,863, is the whole of the avalanche advantage at this payment.
| The card | Its rate | Minimums only | On the plan | Cleared |
|---|---|---|---|---|
| Card A — $34,000 | 24% | $35,030 | $6,825 | month 12 |
| Card B — $26,000 | 19% | $15,514 | $2,572 | month 8 |
| Card C — $18,000 | 22% | $14,703 | $1,127 | month 5 |
| Card D — $12,000 | 15% | $4,740 | $212 | month 2 |
What the twelve months cost
The twelve months cost $10,737 of interest, and the total that leaves your account is $100,737. The interest is 11.93% of the balance you started with and 10.66% of everything you send. The whole period of interest is $4.77 of the $2,250 minimum payments, and the plan pays 4.056 times the minimums and finishes the job in 12 months instead of 81 — 6.75 times faster.
Avalanche is cheaper here, but it is not faster. Run at the same $9,125 a month it is charged $9,270 — $1,467 less — and it also lands in twelve months. Avalanche can clear the balance at its own lower threshold of $8,986.
Card by card, the plan is charged $6,825 on Card A, $2,572 on Card B, $1,127 on Card C and $212 on Card D. Card A is 37.78% of the balance but 63.57% of the plan's interest bill, which is why paying it first is the whole of the avalanche advantage. On the minimums-only path the same four cards are charged $35,030 (Card A), $15,514 (Card B), $14,703 (Card C) and $4,740 (Card D).
Reproduce these numbers
Every figure on this page comes from this site's public API. Post the four balances, their rates, their minimums and extra: 6875 to /api/payoff and you get the same months, the same $10,737 and the same per-card breakdown — including the remaining on each month of the timeline, once with extra: 6875 and once with extra: 0. Two things that trip people up: APR goes in as a percentage (24, not 0.24), and extra is the amount above your total minimums, not your total payment — $6,875 here, which is what turns the $2,250 in minimums into $9,125 a month. Or just open the calculator and type your balances in — same engine, no payload.
If your target is a different size, the same analysis is in the $90000$90000 and all case studies hub, plus the payoff questions hub for shorter answers.
Frequently asked
How much do I have to pay a month to clear $90,000 in 12 Months?
On the four-card example here, $9,125 a month clears the $90,000 in twelve months on the snowball method, which is $6,875 above the $2,250 in minimums. Avalanche needs less — $8,986 — because it goes at the 24% card first.
How much interest does $90,000 cost over 12 Months?
The snowball plan is charged $10,737 and the total that leaves your account is $100,737 — the $90,000 balance plus that interest. The interest is 11.93% of the balance you started with and 10.66% of everything you send. Run at the same $9,125 a month, avalanche is charged $9,270, which is $1,467 less — and it lands in the same twelve months.
Why is the biggest, highest-rate card the one the two methods fight over?
Card A carries $34,000 at 24% APR — it is both the largest balance and the highest rate in the portfolio. Snowball saves it for last and clears it in month 12; avalanche attacks it first and clears it in month 5. On the snowball plan Card A alone is charged $6,825, which is 63.57% of the whole $10,737 interest bill; on avalanche it is charged only $1,963. The dominant card is exactly where the two methods disagree most.
Does it matter which card I pay off first on the 12 Months plan?
It is worth $1,467 at the same $9,125 a month, and here it is not worth any time — both methods land in twelve months. Snowball clears Card D in month 2, Card C in month 5, Card B in month 8, Card A in month 12; avalanche clears Card A in month 5, Card C in month 8, Card B in month 11, Card D in month 12. Card A is 37.78% of the balance but 63.57% of the snowball interest bill — $6,825 of the $10,737.
What if I only pay the minimums on $90,000?
The $2,250 in minimums clears the balance in 81 months and costs $69,986 in interest, a total bill of $159,986. The twelve months plan is charged $10,737, a saving of $59,250. The plan also finishes 6.75 times faster: 12 months against 81. Month 1 of the minimums is charged the same $1,572 the plan is, but only $678 of that $2,250 reaches principal.
How long does it take to pay off $90,000 in 12 Months?
$9,125, by definition — but only if you send $9,125 a month, which is 4.056 times the $2,250 in minimums. The deadline is exact: twelve months lands the payoff in twelve months and one dollar less adds a month. Avalanche's own deadline sits lower, at $8,986. The minimums alone take 81 months on the same portfolio and cost $69,986 in interest.
What is the blended interest rate on this portfolio?
20.9556% a year, weighted by balance: $34,000 × 24%, $26,000 × 19%, $18,000 × 22% and $12,000 × 15% work out to $18,860 of annual interest on a $90,000 balance. One twelfth of that is 1.7463, which on the opening balance is $1,572 for the first month.