Numbers from this site's public API on a 5-card $30,000 portfolio at 14-22% APR. Open the calculator with your own balances and rates and the same numbers come out in real time.
The example portfolio
$30,000 is the size where the minimum payments alone come to $750 a month. This page uses five US credit cards — the same five-card shape and the same 22 / 20 / 18 / 16 / 14 APR ladder as the $30K in 1 year and $30K in 6 months case studies. Card A carries $8,000 at 22% APR with a $200 minimum; Card B $7,000 at 20% with a $175 minimum; Card C $6,000 at 18% with a $150 minimum; Card D $5,000 at 16% with a $125 minimum; Card E $4,000 at 14% with a $100 minimum. The five minimums add up to $750 a month.
The rates run a ladder from 22% down to 14%, and the largest balance carries the highest rate. Weighted by balance, the portfolio's rate is 18.6667% a year: $8,000 × 22%, $7,000 × 20%, $6,000 × 18%, $5,000 × 16% and $4,000 × 14% come to $5,600.00 of annual interest on a $30,000 balance. One twelfth of that is 1.55556%, which on the opening balance is $466.67 for the first month — $146.67 on Card A, $116.67 on Card B, $90.00 on Card C, $66.67 on Card D and $46.67 on Card E.
To clear all five in twenty-four months, the snowball method needs $1,777 a month, which is $1,027 above the minimums. Avalanche needs less — $1,724 — because it goes straight at the 22% card. Every figure on this page is for the snowball plan unless it says otherwise.
The detour: two years of the minimums first, then the same $1,777
A two-year deadline has an obvious shape: $1,777 a month for twenty-four months. But there is a second way to spend the same money — pay the minimums for two years first, then point the same $1,777 at whatever is left. Both paths end at zero. Only one of them ends in two years.
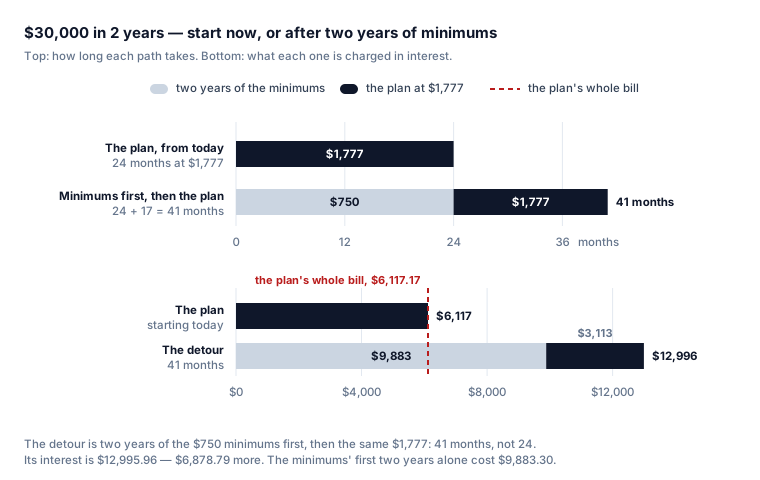
The plan, starting today. Twenty-four months at $1,777 sends $36,117.17 in total: the $30,000 balance plus $6,117.17 of interest. The interest is 20.39% of what you owed and 16.94% of everything you send, and the twenty-fourth payment takes the balance to zero.
The detour. Two years of the $750 minimum moves $18,000 out of your account and retires $8,116.70 of the balance — barely more than Card A's whole $8,000. $9,883.30 of what you sent was interest, which is 54.91%. So after twenty-four months you still owe $21,883.30, or 72.94% of the balance: Card A $6,410.09, Card B $5,295.80, Card C $4,281.99, Card D $3,362.79 and Card E $2,532.63. Then the same $1,777 clears that in 17 more months for $3,112.66 of interest — so the detour ends at 41 months and $12,995.96.
The premium is $6,878.79 and 17 months. The extra interest alone is 1.125 times the plan's entire interest bill, and the minimums' first two years on their own ($9,883.30) are already 161.57% of it. The detour is still far better than paying the minimums all the way — 41 months and $12,995.96 against 73 months and $18,014.10, which is 32 months and $5,018.14 saved — but the cheapest way to buy this deadline is to start now.
| The path | Months | Sent | Interest | Balance at the end |
|---|---|---|---|---|
| The plan, starting today | 24 | $36,117.17 | $6,117.17 | $0.00 |
| Minimums only, months 1-24 | 24 | $18,000.00 | $9,883.30 | $21,883.30 |
| Then the plan's $1,777, months 25-41 | 17 | $24,995.96 | $3,112.66 | $0.00 |
| The detour, months 1-41 | 41 | $42,995.96 | $12,995.96 | $0.00 |
Read the first line against the last and the whole page is there: the same $30,000, bought back for $36,117.17 in twenty-four months or $42,995.96 in forty-one. The middle two lines are the trap: two years of minimums retires $8,116.70, which is one card's worth of balance, and then the plan's own $1,777 still needs seventeen more months to finish the job it would have done in twenty-four.
What the two years cost
The twenty-four months cost $6,117.17 of interest, and the total that leaves your account is $36,117.17. The interest is 20.39% of the balance you started with and 16.94% of everything you send. The whole two years of interest is 8.156 of the $750 minimum payments, and the monthly charge falls from $466.67 in month 1 to $21.98 in month 24 — 21.23 times less. By the last payment, 98.20% of the $1,221.17 reaches principal and only 1.80% is interest.
Avalanche is cheaper and faster on this portfolio. Run at the same $1,777 a month it is charged $5,048.21 — $1,068.96 less, so the snowball bill is 1.212 times the avalanche bill — and it finishes in month 23, a month before the snowball. Avalanche can also clear the balance at its own lower threshold of $1,724, and at that smaller payment it lands in twenty-four months for $5,258.75; the $5,048.21 above is the equal-payment figure, so the two numbers differ by the payment they are measured at, not by the method. This portfolio loses one month to the order; across what the two orders cost on twelve portfolios the snowball ran 5.1 months behind on average, because a longer payoff gives the expensive card more time to charge interest.
The payments step down four times as cards close: $1,777 in months 1 to 4, $1,677 in months 5 to 8, $1,552 in months 9 to 13, $1,402 in months 14 to 19, $1,227 in months 20 to 23, and $1,221.17 in month 24. Each drop is exactly the minimum of the card that just cleared — $100 for Card E, $125 for Card D, $150 for Card C, $175 for Card B — and the fifth drop, Card A's $200, never arrives: the plan ends at $1,221.17 instead of $1,027. The balance path is $28,689.67, $27,363.10, $26,020.10, $24,660.45, $23,383.29, $22,088.50, $20,775.83, $19,445.04, $18,220.71, $16,977.69, $15,715.71, $14,434.47, $13,133.68, $11,962.61, $10,771.92, $9,561.27, $8,330.32, $7,078.74, $5,806.17, $4,685.62, $3,544.52, $2,382.51, $1,199.19 and zero.
The deadline itself is exact. $1,777 a month lands the payoff in twenty-four months; $1,776 adds a twenty-fifth and takes the interest to $6,122.77. Avalanche's own deadline sits lower: $1,724 finishes in twenty-four months, and $1,723 pushes it to twenty-five and $5,263.44. The first twelve months send $20,024.00 and the last twelve $16,093.17 — 19.63% less — and they retire $15,565.53 against $14,434.47. Twenty-four flat payments of $1,777 would come to $42,648; the plan sends $36,117.17, so $6,530.83 of those flat payments never happens.
Where the $1,027 comes from
This is the part that decides whether the plan happens, so it is worth stating plainly: you need $1,027 a month above the $750 you already pay — 1.369 times the minimums — and over the twenty-four months the new money alone is $24,648, which is 82.16% of the balance. The plan pays 2.369 times the minimums and finishes the job in 24 months instead of 73 — 3.042 times faster.
Two comparisons make the size of the ask concrete. The plan's $36,117.17 is 75.22% of the $48,014.10 the minimums-only path costs, so you spend about three quarters of the money and save $11,896.93. And month 1 of the minimums is charged the same $466.67 the plan is, but of that $750 only $283.33 reaches principal — 37.78%, against 73.74% for the plan's first payment, where the other 26.26% is interest.
Stretching the same $30,000 across different deadlines is a separate trade, and it is worth naming. The six-month plan on this portfolio is $5,536 a month and $1,736.74 of interest; the twelve-month plan is $3,041 a month and $3,214.65; the twenty-four-month plan is $1,777 a month and $6,117.17; the thirty-six-month plan is $1,346 a month and $8,899.09. Going from one year to two cuts the payment by $1,264 a month and adds $2,902.52 of interest, which is 90.3% of the twelve-month bill. You are buying cash flow, and you are paying for it in interest.
Card by card, the plan is charged $2,923.75 on Card A, $1,744.78 on Card B, $931.75 on Card C, $406.44 on Card D and $110.45 on Card E. Card A is 26.67% of the balance but 47.80% of the plan's interest bill, which is why paying it first is the whole of the avalanche advantage.
Reproduce these numbers
Every figure on this page comes from this site's public API. Post the five balances, their rates, their minimums and extra: 1027 to /api/payoff and you get the same months, the same $6,117.17 and the same per-card breakdown — including the remaining on each month of the timeline, once with extra: 1027 and once with extra: 0. Two things that trip people up: APR goes in as a percentage (22, not 0.22), and extra is the amount above your total minimums, not your total payment — $1,027 here, which is what turns the $750 in minimums into $1,777 a month. For the detour, run it twice: first with extra: 0, which leaves $21,883.30 owing after month 24, then post the balances the calculator shows at that point — $6,410.09, $5,295.80, $4,281.99, $3,362.79 and $2,532.63 — with extra: 1027 again, and the rest takes 17 months for $3,112.66. Or just open the calculator and type your balances in — same engine, no payload.
If your target is a different size or a different deadline, the same analysis is in the $30K in 1 year, $30K in 6 months, $40K in 2 years, $40K in 1 year, $40K in 6 months, $80K in 2 years, $80K in 12 months, $80K in 6 months, $70K in 2 years, $70K in 12 months, $70K in 6 months, $60K in 2 years, $60K in 12 months, $60K in 6 months, $50K in 2 years, $50K in 12 months, $50K in 6 months, $20K in 6 months, $15K in 6 months, $10K in 6 months, $5K in 6 months, $5K in 1 year, $10K, $15K, $20K, $25K and $100K case studies, plus a 36-second walkthrough of the $25K case on YouTube. Shorter answers to the most common payoff questions live in the payoff questions hub.
Frequently asked
How much do I have to pay a month to clear $30,000 in two years?
On the five-card example here, $1,777 a month clears the $30,000 in twenty-four months on the snowball method, which is $1,027 above the $750 in minimums. Avalanche needs less — $1,724 — because it goes at the 22% card first.
How much interest do I pay on $30,000 over two years?
The snowball plan is charged $6,117.17 and the total that leaves your account is $36,117.17 — the $30,000 balance plus that interest. The interest is 20.39% of the balance you started with and 16.94% of everything you send, and it is 8.156 of the $750 minimum payments. Run at the same $1,777 a month, avalanche is charged $5,048.21, which is $1,068.96 less — 1.212 times the avalanche bill — and it finishes a month earlier, in month 23.
What if I pay the minimums for two years first and then start?
That detour takes 41 months, not 24, and costs $12,995.96 of interest instead of $6,117.17 — $6,878.79 more, which is 1.125 times the whole plan's interest bill. Two years of the $750 minimums sends $18,000 and retires $8,116.70, so you still owe $21,883.30 — 72.94% of the balance — with Card A at $6,410.09, Card B at $5,295.80, Card C at $4,281.99, Card D at $3,362.79 and Card E at $2,532.63. The same $1,777 then clears that in 17 months for $3,112.66.
What do two years of the minimums actually retire?
Twenty-four months of minimums moves $18,000 out of your account. Of that, $9,883.30 is interest — 54.91% of what you sent — and only $8,116.70 reaches principal, which is barely more than Card A's whole $8,000 balance. So after two years you still owe $21,883.30, which is 72.94% of the balance you started with. The plan, over the same twenty-four months, sends $36,117.17 and ends at zero. Finishing the rest on the minimums takes another 49 months.
Does it matter which card I pay off first on a two-year plan?
It is worth $1,068.96 at the same $1,777 a month, and it is also worth a month: avalanche finishes in month 23 where the snowball needs 24. Snowball clears Card E in month 4, Card D in month 8, Card C in month 13, Card B in month 19 and Card A in month 24; avalanche clears Card A in month 8, Card B in month 13, Card C in month 18, Card D in month 21 and Card E in month 23. Card A is 26.67% of the balance but 47.80% of the snowball interest bill — $2,923.75 of the $6,117.17.
What if I only pay the minimums on $30,000?
The $750 in minimums clears the balance in 73 months — a little over six years — and costs $18,014.10 in interest, a total bill of $48,014.10. The twenty-four-month plan is charged $6,117.17, a saving of $11,896.93. The plan also finishes 3.042 times faster: 24 months against 73. Month 1 of the minimums is charged the same $466.67 the plan is, but only $283.33 of that $750 reaches principal, against $1,310.33 of the plan's first payment.
How long does it take to pay off $30,000 in 2 years?
Two years, by definition — but only if you send $1,777 a month, which is 2.369 times the $750 in minimums. The deadline is exact: $1,777 lands the payoff in twenty-four months and $1,776 adds a twenty-fifth. The minimums alone take 73 months on the same portfolio and cost $18,014.10 in interest.
What is the blended interest rate on this portfolio?
18.6667% a year, weighted by balance: $8,000 at 22%, $7,000 at 20%, $6,000 at 18%, $5,000 at 16% and $4,000 at 14% work out to $5,600.00 of annual interest on $30,000. One twelfth of that is 1.55556%, which is $466.67 on the opening balance — $146.67 on Card A, $116.67 on Card B, $90.00 on Card C, $66.67 on Card D and $46.67 on Card E. By month 24, under the plan, the monthly interest is down to $21.98 — 21.23 times less than month 1.